INCOME TAX
Overview on Private Trusts, Trust Taxation & Family Governance
RJA 08 Oct, 2026
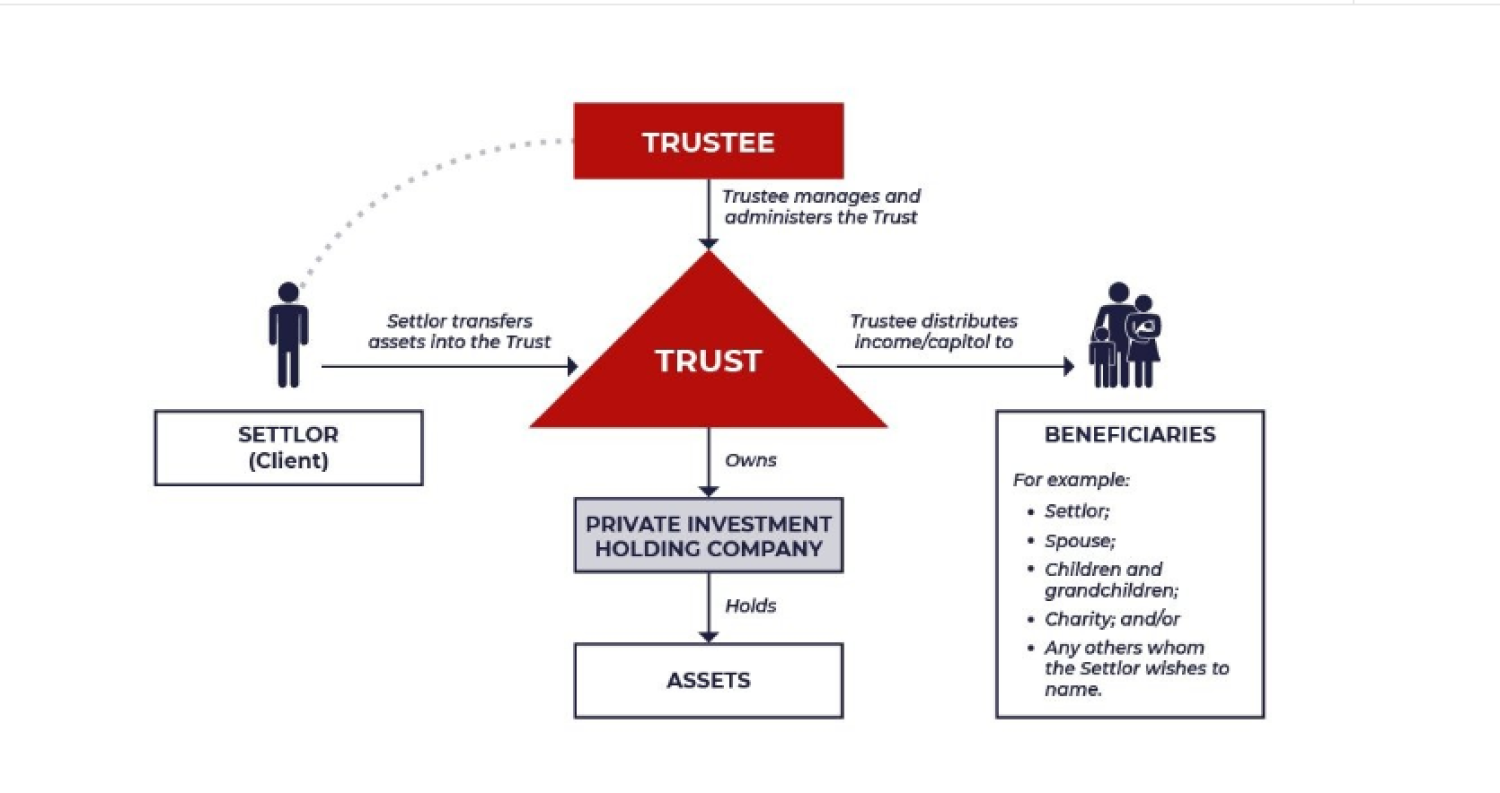
Private Trusts, Trust Taxation & Family Governance: A Comprehensive Guide for Business Families In India, many business families focus intensely on wealth creation but often overlook an equally important challenge: preserving wealth across generations. As family businesses expand and family trees become larger, issues relating to ownership, succession, governance, and ...
INCOME TAX
Overview of The Family Office – More Than Wealth Management
RJA 08 Oct, 2026
Overview of The Family Office – More Than Wealth Management The Family Office—More Than Wealth Management a Family Office is not merely an investment management platform. Instead, it is a comprehensive structure designed to manage a family's wealth, succession planning, governance, taxation, philanthropy, and long-term legacy. Key ...
INCOME TAX
Taxation of Family Office and Alternative Family Office Vehicles
RJA 08 Oct, 2026
Taxation of Family Office and Alternative Family Office Vehicles This is blog explain about on family office structures. It introduces different legal vehicles through which a wealthy family can manage investments, succession planning, governance, asset protection, and inter-generational wealth transfer. Main Objective : The family must choose the most suitable ...
INCOME TAX
Typical Trust Structure or Types of Trusts: An Overview
RJA 08 Oct, 2026
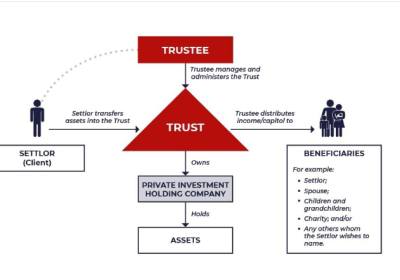
Typical Trust Structure or Types of Trusts: An Overview Trusts can be structured in different ways depending on the objectives of the settlor, the needs of the beneficiaries, and the level of control or flexibility desired. The following are some of the most commonly used types of trusts: 1. Discretionary ...
AUDIT
Highlights Importance of Mandatory Disclosures in Audits
RJA 08 Oct, 2026
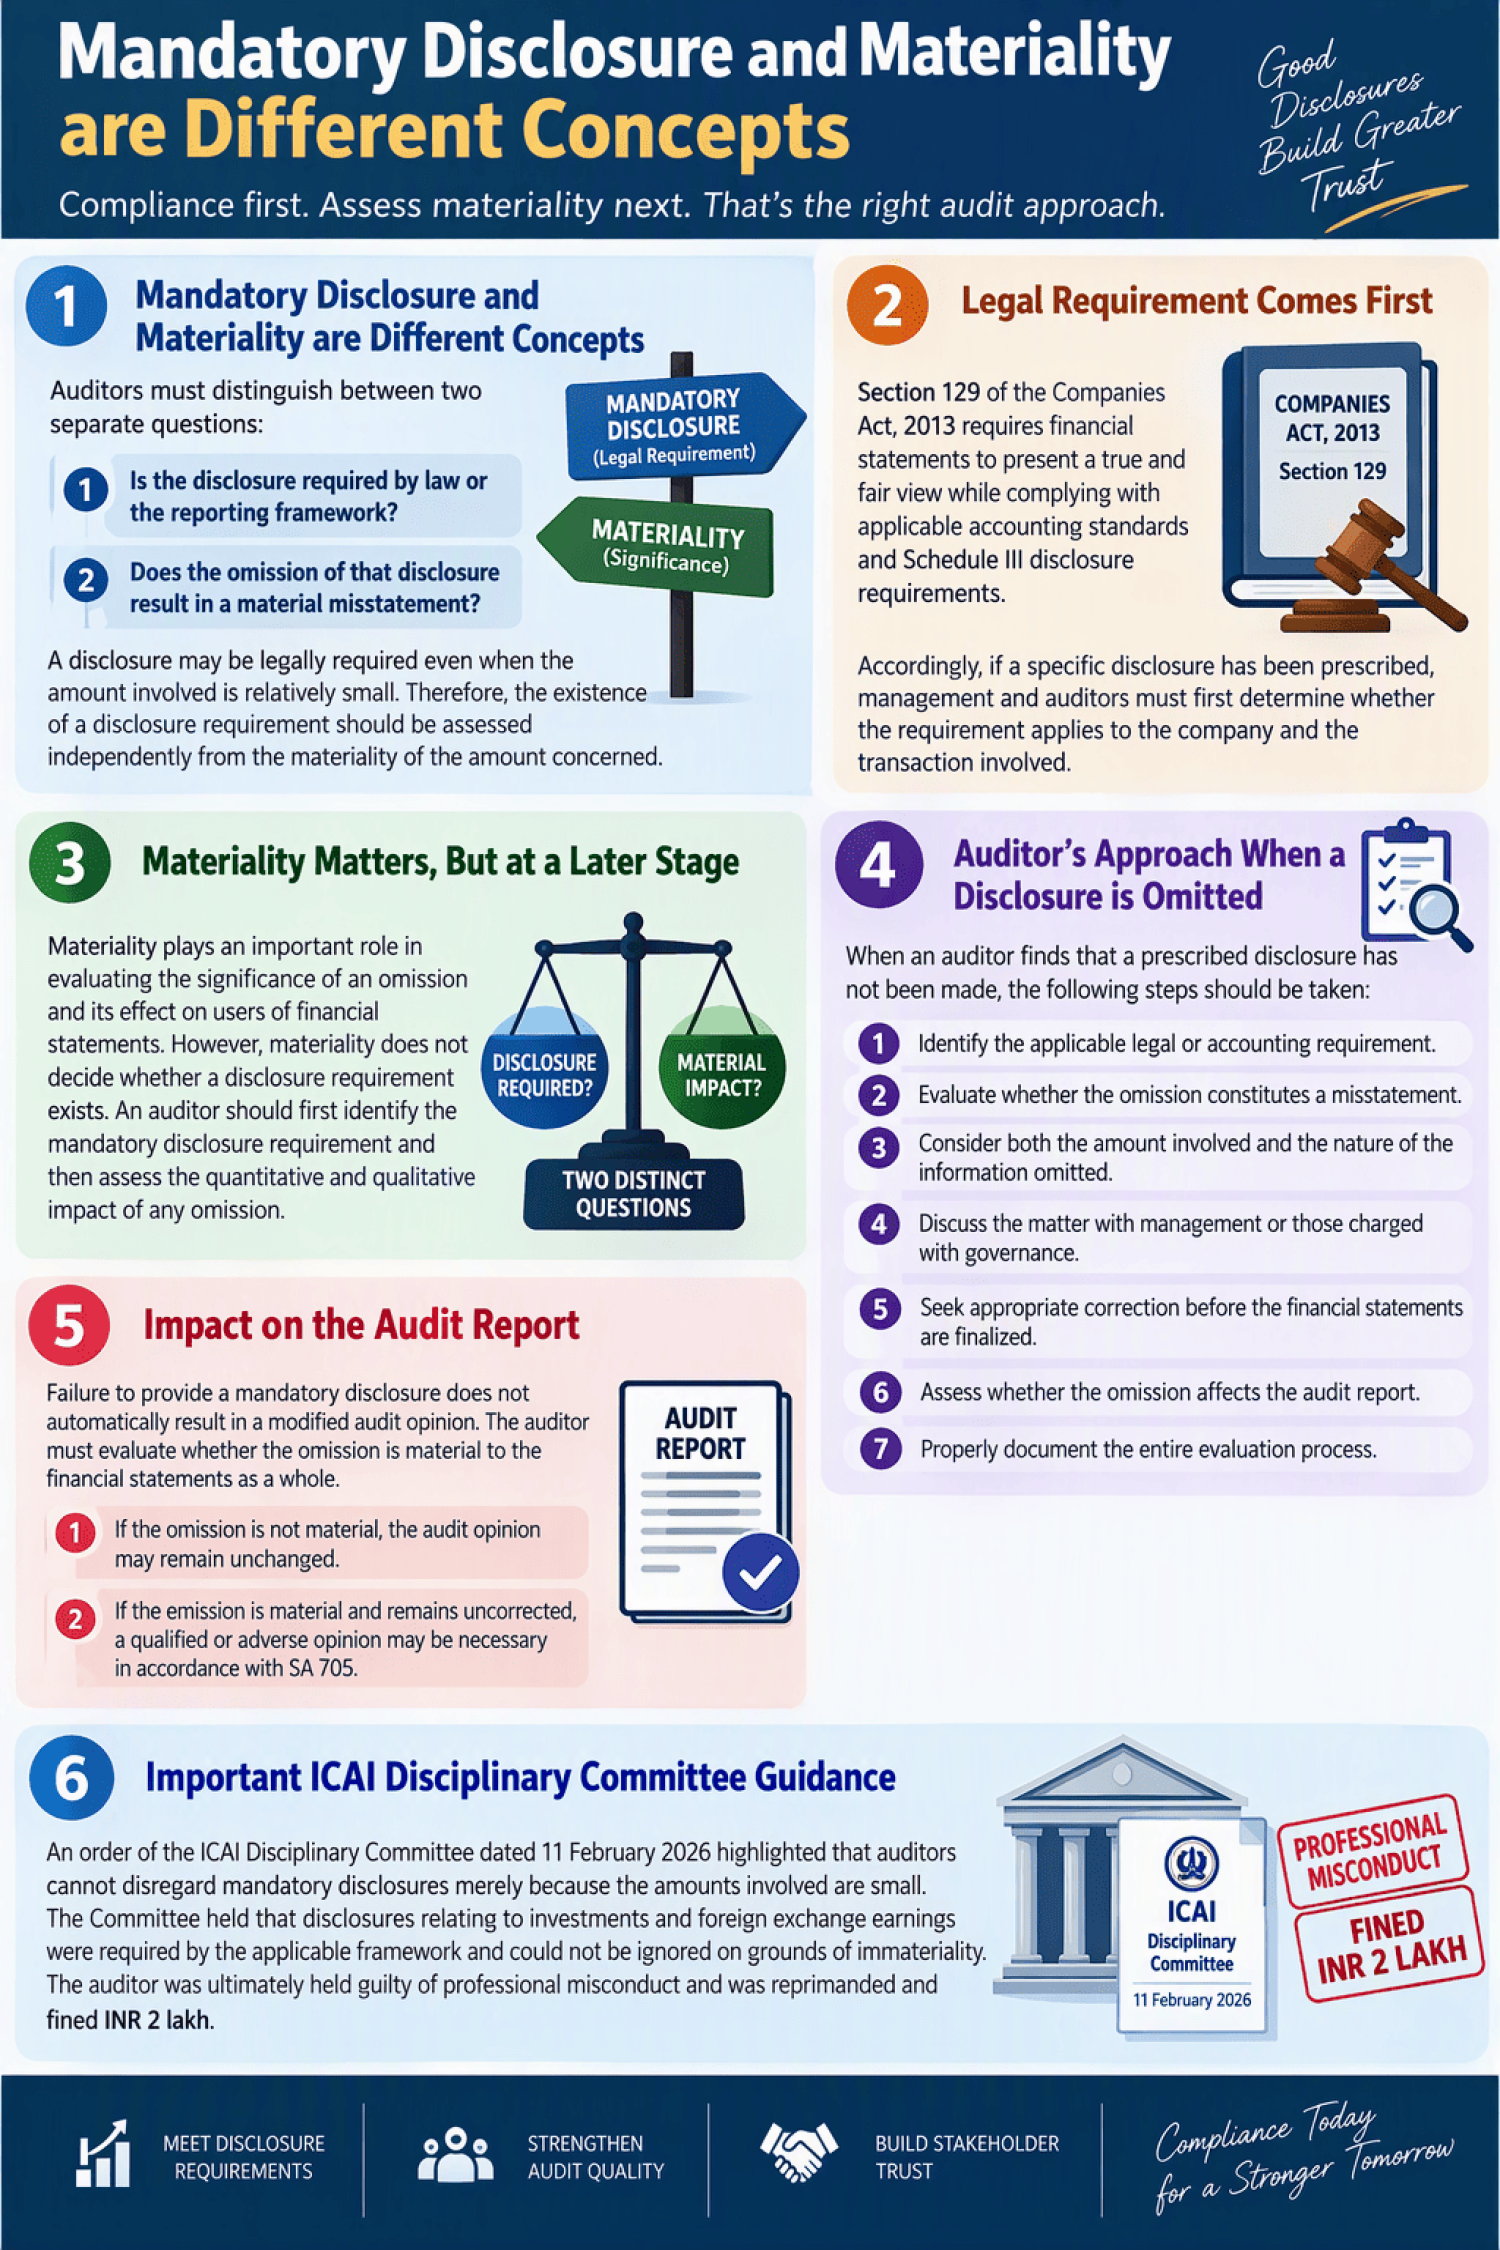
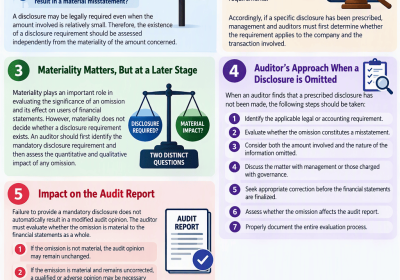
Materiality Cannot Override Mandatory Disclosure Requirements: Auditor's Responsibilities Explained A common question during the preparation and audit of financial statements is whether a disclosure prescribed by law can be omitted simply because the amount involved is insignificant. The answer is generally no. While materiality is a key audit ...
Goods and Services Tax
Detailed Analysis of 57th GST Council Meeting (8 Oct 2026)
RJA 08 Oct, 2026
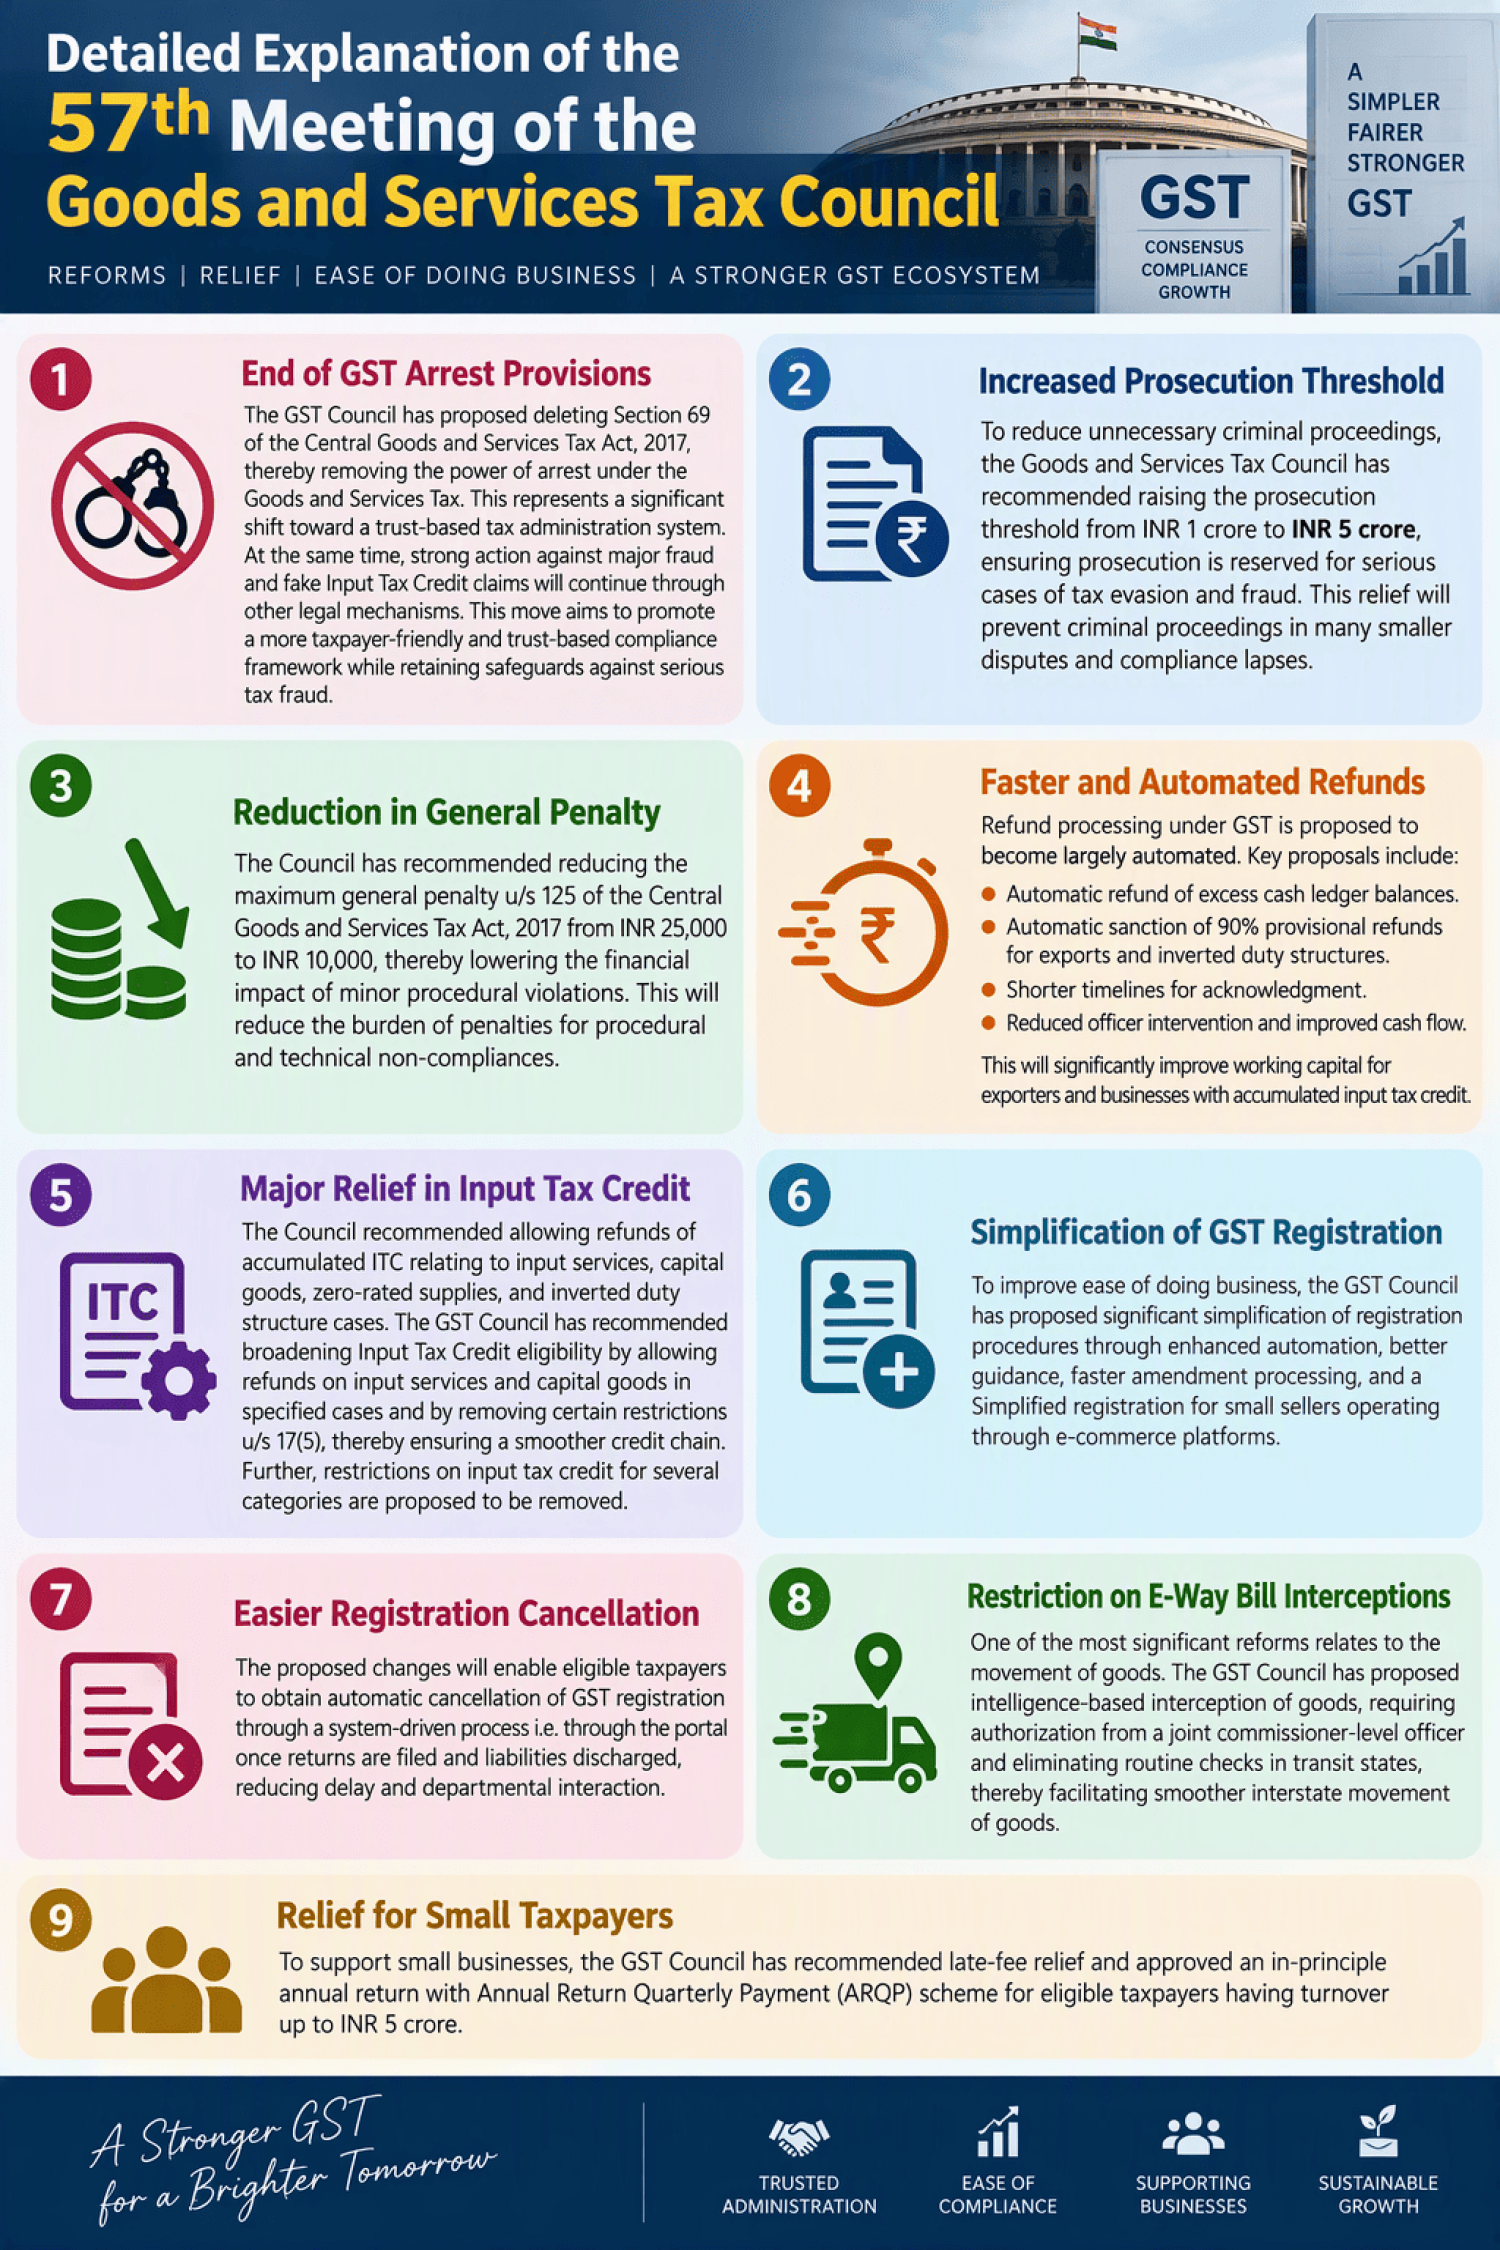
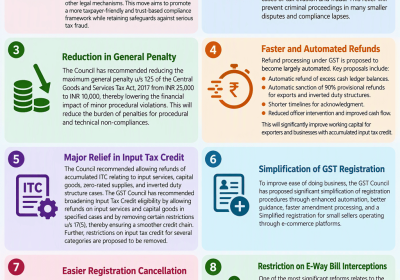
Detailed Analysis of the 57th GST Council Meeting (8 October 2026) The 57th GST Council Meeting is one of the most significant reform-oriented GST meetings since the introduction of GST. Unlike earlier meetings that focused heavily on GST rate changes, this meeting concentrated on ease of doing business, faster refunds, wider Input ...
COMPANY LAW
Overview of filling in an Auditor appointment & MCA clarification
RJA 07 Oct, 2026
Overview of Filing of Auditor Appointment (Form ADT-1) & Recent MCA Clarifications Form ADT-1 is a statutory form filed by a company with the Registrar of Companies (ROC) to intimate the appointment or re-appointment of its auditor under Section 139(1) of the Companies Act, 2013. It serves as a notice to the ...
NGO
Taxation of NPOs under I Tax Act, 2025: Guide for Trusts, Societies etc
RJA 04 Oct, 2026
Taxation of NPOs under the Income-tax Act, 2025: A Practical Guide for Trusts, Societies and Section 8 Companies A new rulebook for charities from Tax Year 2026-27 From Tax Year 2026-27, every charitable and religious trust, society and section 8 company in India is taxed under a new framework in the Income-tax Act, 2025. ...
Goods and Services Tax
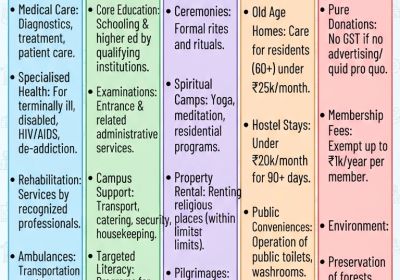
GST Exemptions for Charitable Trusts – Quick Summary
RJA 04 Oct, 2026
GST Exemptions for Charitable Trusts – Quick Summary Being a charitable trust does not automatically make all income GST-exempt. Exemption depends on the specific nature of the activity. Sale of books, souvenirs, marathon participation fees, commercial renting, sponsorship arrangements, or other business-like activities may still attract GST. the following major ...
Goods and Services Tax
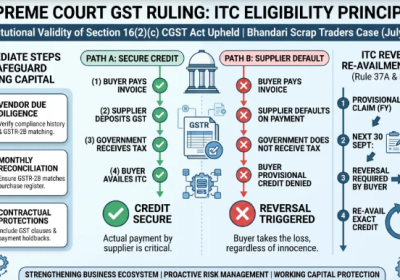
Landmark Ruling on GST Input Tax Credit u/s 16(2)(c)
RJA 03 Oct, 2026
Landmark Ruling on GST Input Tax Credit under Section 16(2)(c) Introduction One of the most persistent grievances of GST-registered businesses has been the denial or reversal of Input Tax Credit (ITC) on genuine purchases, only because the supplier failed to deposit the tax, filed nil or short returns, or had ...
GST Filling
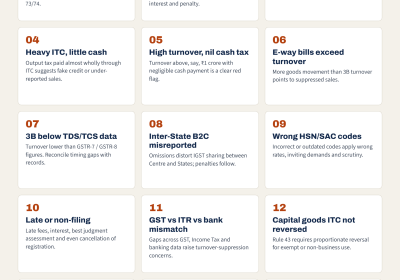
GSTR Errors That Commonly Lead to Notices, Audits & Demand
RJA 03 Oct, 2026
GST Return Errors That Commonly Lead to Scrutiny Notices, Audits and Demands Small errors in Goods and Services tax returns rarely stay small. Figures that don't match across returns, or Input tax credit claimed without the right support, are now picked up quickly by the department's data analytics. ...
GST Filling
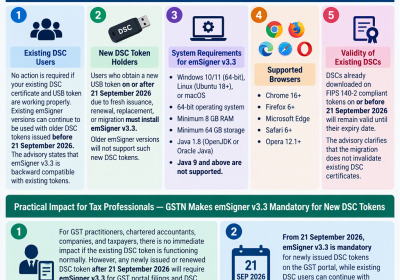
GSTN Makes emSigner v3.3 Mandatory for New DSC Tokens from 21 09.2026
RJA 02 Oct, 2026
GSTN Makes emSigner v3.3 Mandatory for New DSC Tokens from 21 September 2026 GSTN has released an advisory requiring users with newly issued DSC USB tokens (dongles) issued on or after 21 September 2026 to upgrade to emSigner version 3.3. The change is intended to ensure compatibility with new-generation DSC tokens. Key Points—GSTN ...
IBC
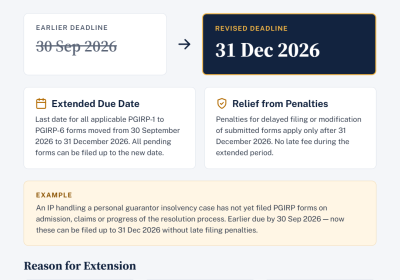
IBBI Further Extends Deadline for Filing PGIRP Forms
RJA 02 Oct, 2026
IBBI Further Extends Deadline for Filing PGIRP Forms The Insolvency and Bankruptcy Board of India (IBBI) has issued Circular No. IBBI/II/108/2026 dated 24 September 2026, granting a further extension for filing electronic Forms PGIRP-1 to PGIRP-6 relating to insolvency resolution processes of Personal Guarantors to Corporate Debtors. Key Highlights of IBBI ...
IBC
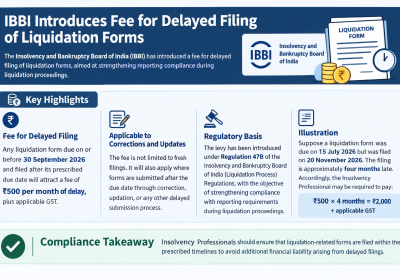
IBBI Introduces Fee for Delayed Filing of Liquidation Forms
RJA 02 Oct, 2026
IBBI Introduces Fee for Delayed Filing of Liquidation Forms The Insolvency and Bankruptcy Board of India (IBBI) has issued Circular No. IBBI/LIQ/107/2026 dated 24 September 2026, notifying the commencement of fees for delayed filing of forms under Regulation 47B of the IBBI (Liquidation Process) Regulations, 2016. The circular applies to all Registered ...
IBC
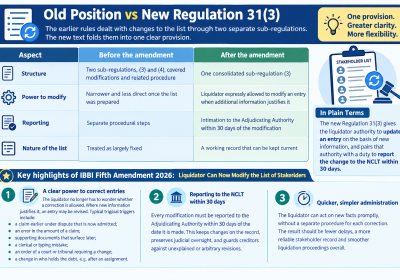
IBBI Fifth Amendment 2026: Liquidator Can Now Modify the List of Stakeholders
RJA 02 Oct, 2026
Overview of IBBI Fifth Amendment 2026: Liquidator Can Now Modify the List of Stakeholders A liquidator can now correct any entry in the List of Stakeholders when fresh information supports it, provided the Adjudicating Authority is told within 30 days. This is the core of the IBBI (Liquidation Process) (Fifth Amendment) ...
IBC
Cessation of Interim Moratorium for PG's to Corporate Debtors
RJA 02 Oct, 2026
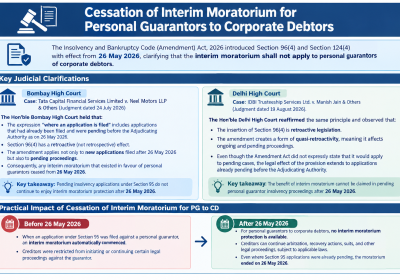
Cessation of Interim Moratorium for Personal Guarantors to Corporate Debtors The Insolvency and Bankruptcy Code (Amendment) Act, 2026 introduced Section 96(4) and Section 124(4) with effect from 26 May 2026, clarifying that the interim moratorium shall not apply to personal guarantors of corporate debtors. Following are Key Judicial Clarifications Bombay High Court : Case: Tata ...
IBC
Due Diligence by Insolvency Professionals to Identify and Prevent Misuse of the IBC Framework
RJA 02 Oct, 2026
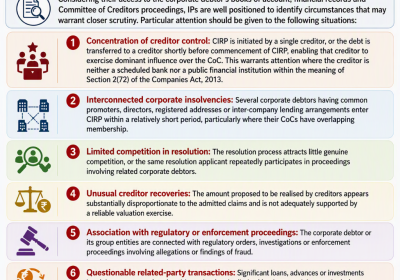
Due Diligence by Insolvency Professionals to Identify and Prevent Misuse of the IBC Framework The Insolvency and Bankruptcy Board of India (IBBI), based on information received from law enforcement and regulatory authorities, has highlighted concerns regarding the potential misuse of the Insolvency and Bankruptcy Code, 2016 (IBC). In certain cases, insolvency ...
IBC
IBBI Valuation Guidelines under IBC 2026: Complete Guide
RJA 02 Oct, 2026
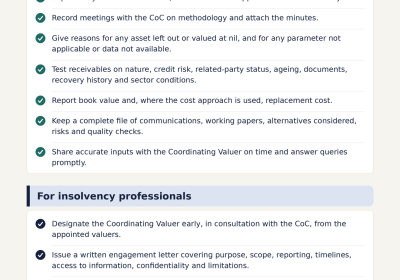
IBBI Valuation Guidelines under IBC, 2026: Complete Explained Guide From 15 June 2026, every registered valuer working under the Insolvency and Bankruptcy Code, 2016 must prepare reports and keep working papers in the format IBBI has now prescribed. The rules come from IBBI Circular No. IBBI/RV/103/2026, which also creates a Coordinating Valuer to ...
AUDIT
44AB(a), (b), (c), (d)/(e): Which Tax Audit (FY 2025-26) Clause Applies?
RJA 01 Oct, 2026
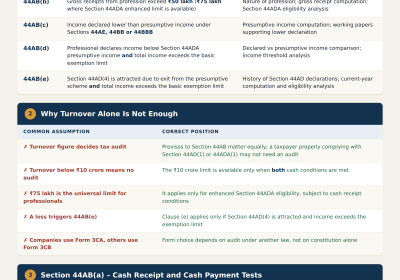
44AB(a), (b), (c), (d) or (e): Which Tax Audit Clause Applies? (FY 2025-26 / AY 2026-27) Selecting the correct clause under Section 44AB is the first step in a tax audit. The clause reported in Clause 8 of Form 3CD reflects why the audit applies, while the choice between Form 3CA ...
COMPANY LAW
Compliance Planning Checklist for October 2026
RJA 01 Oct, 2026
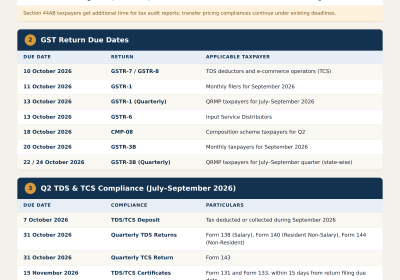
October 2026 Compliance Calendar: Key Tax, GST, TDS, ROC & Payroll Due Dates October 2026 is one of the most critical compliance months for businesses, professionals, companies, LLPs, and tax practitioners. With revised tax audit timelines, quarterly TDS/TCS filings, GST returns, ROC compliances, and payroll obligations falling in the same month, ...
INCOME TAX
Salary Tax Planning for Tax Year 2026-27: New Regime vs Old Regime
RJA 30 Sep, 2026
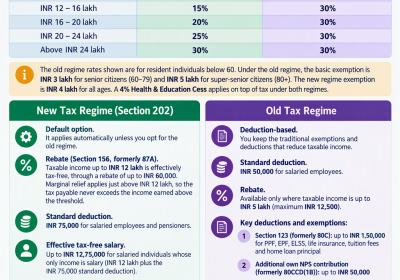
Salary Tax Planning for Tax Year 2026-27: New Regime vs Old Regime under the Income-tax Act, 2025 From "FY/AY" to "Tax Year": what has changed The Income-tax Act, 2025 came into force on 1 April 2026, replacing the Income-tax Act, 1961. One of its most visible changes is terminology. The ...
IBC
Liquidator's compliance under IBC underwent changes in 2026.
RJA 30 Sep, 2026
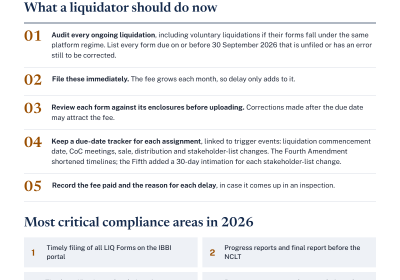
Liquidator's compliance under IBC underwent changes in 2026. The compliance framework for liquidators has undergone substantial changes during 2026. The most significant amendments were introduced through the Insolvency and Bankruptcy Board of India (Liquidation Process) (Fourth Amendment) Regulations, 2026, notified on 1 June 2026 and brought into force from 3 June 2026 through publication in the ...
NRI
TDS on Buying Property from an NRI: TAN Requirement Removed From 1 Oct 2026
RJA 27 Sep, 2026
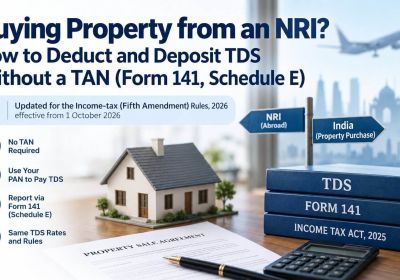
TDS on Buying Property from an NRI: TAN Requirement Removed From 1 October 2026 Starting 1 October 2026, a resident individual or HUF who purchases immovable property from a non-resident will not have to obtain a TAN to deduct and deposit TDS. The CBDT has notified the Income-tax (Fifth Amendment) Rules, 2026 (Notification No. 121/2026, G....
Chartered Accountants
ICAI's 60 Tax Audit Limit Now Enforced via UDIN: What Every CA Must Know
RJA 24 Sep, 2026
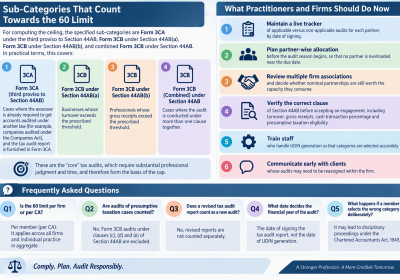
ICAI's 60 Tax Audit Limit Now Enforced Through UDIN: What Every Chartered Accountant Must Know Introduction For many years, the ceiling on the number of tax audits that a chartered accountant could undertake functioned largely as a matter of professional self-regulation. That position is now set to change. The Institute ...