Table of Contents
GST Exemptions for Charitable Trusts – Quick Summary
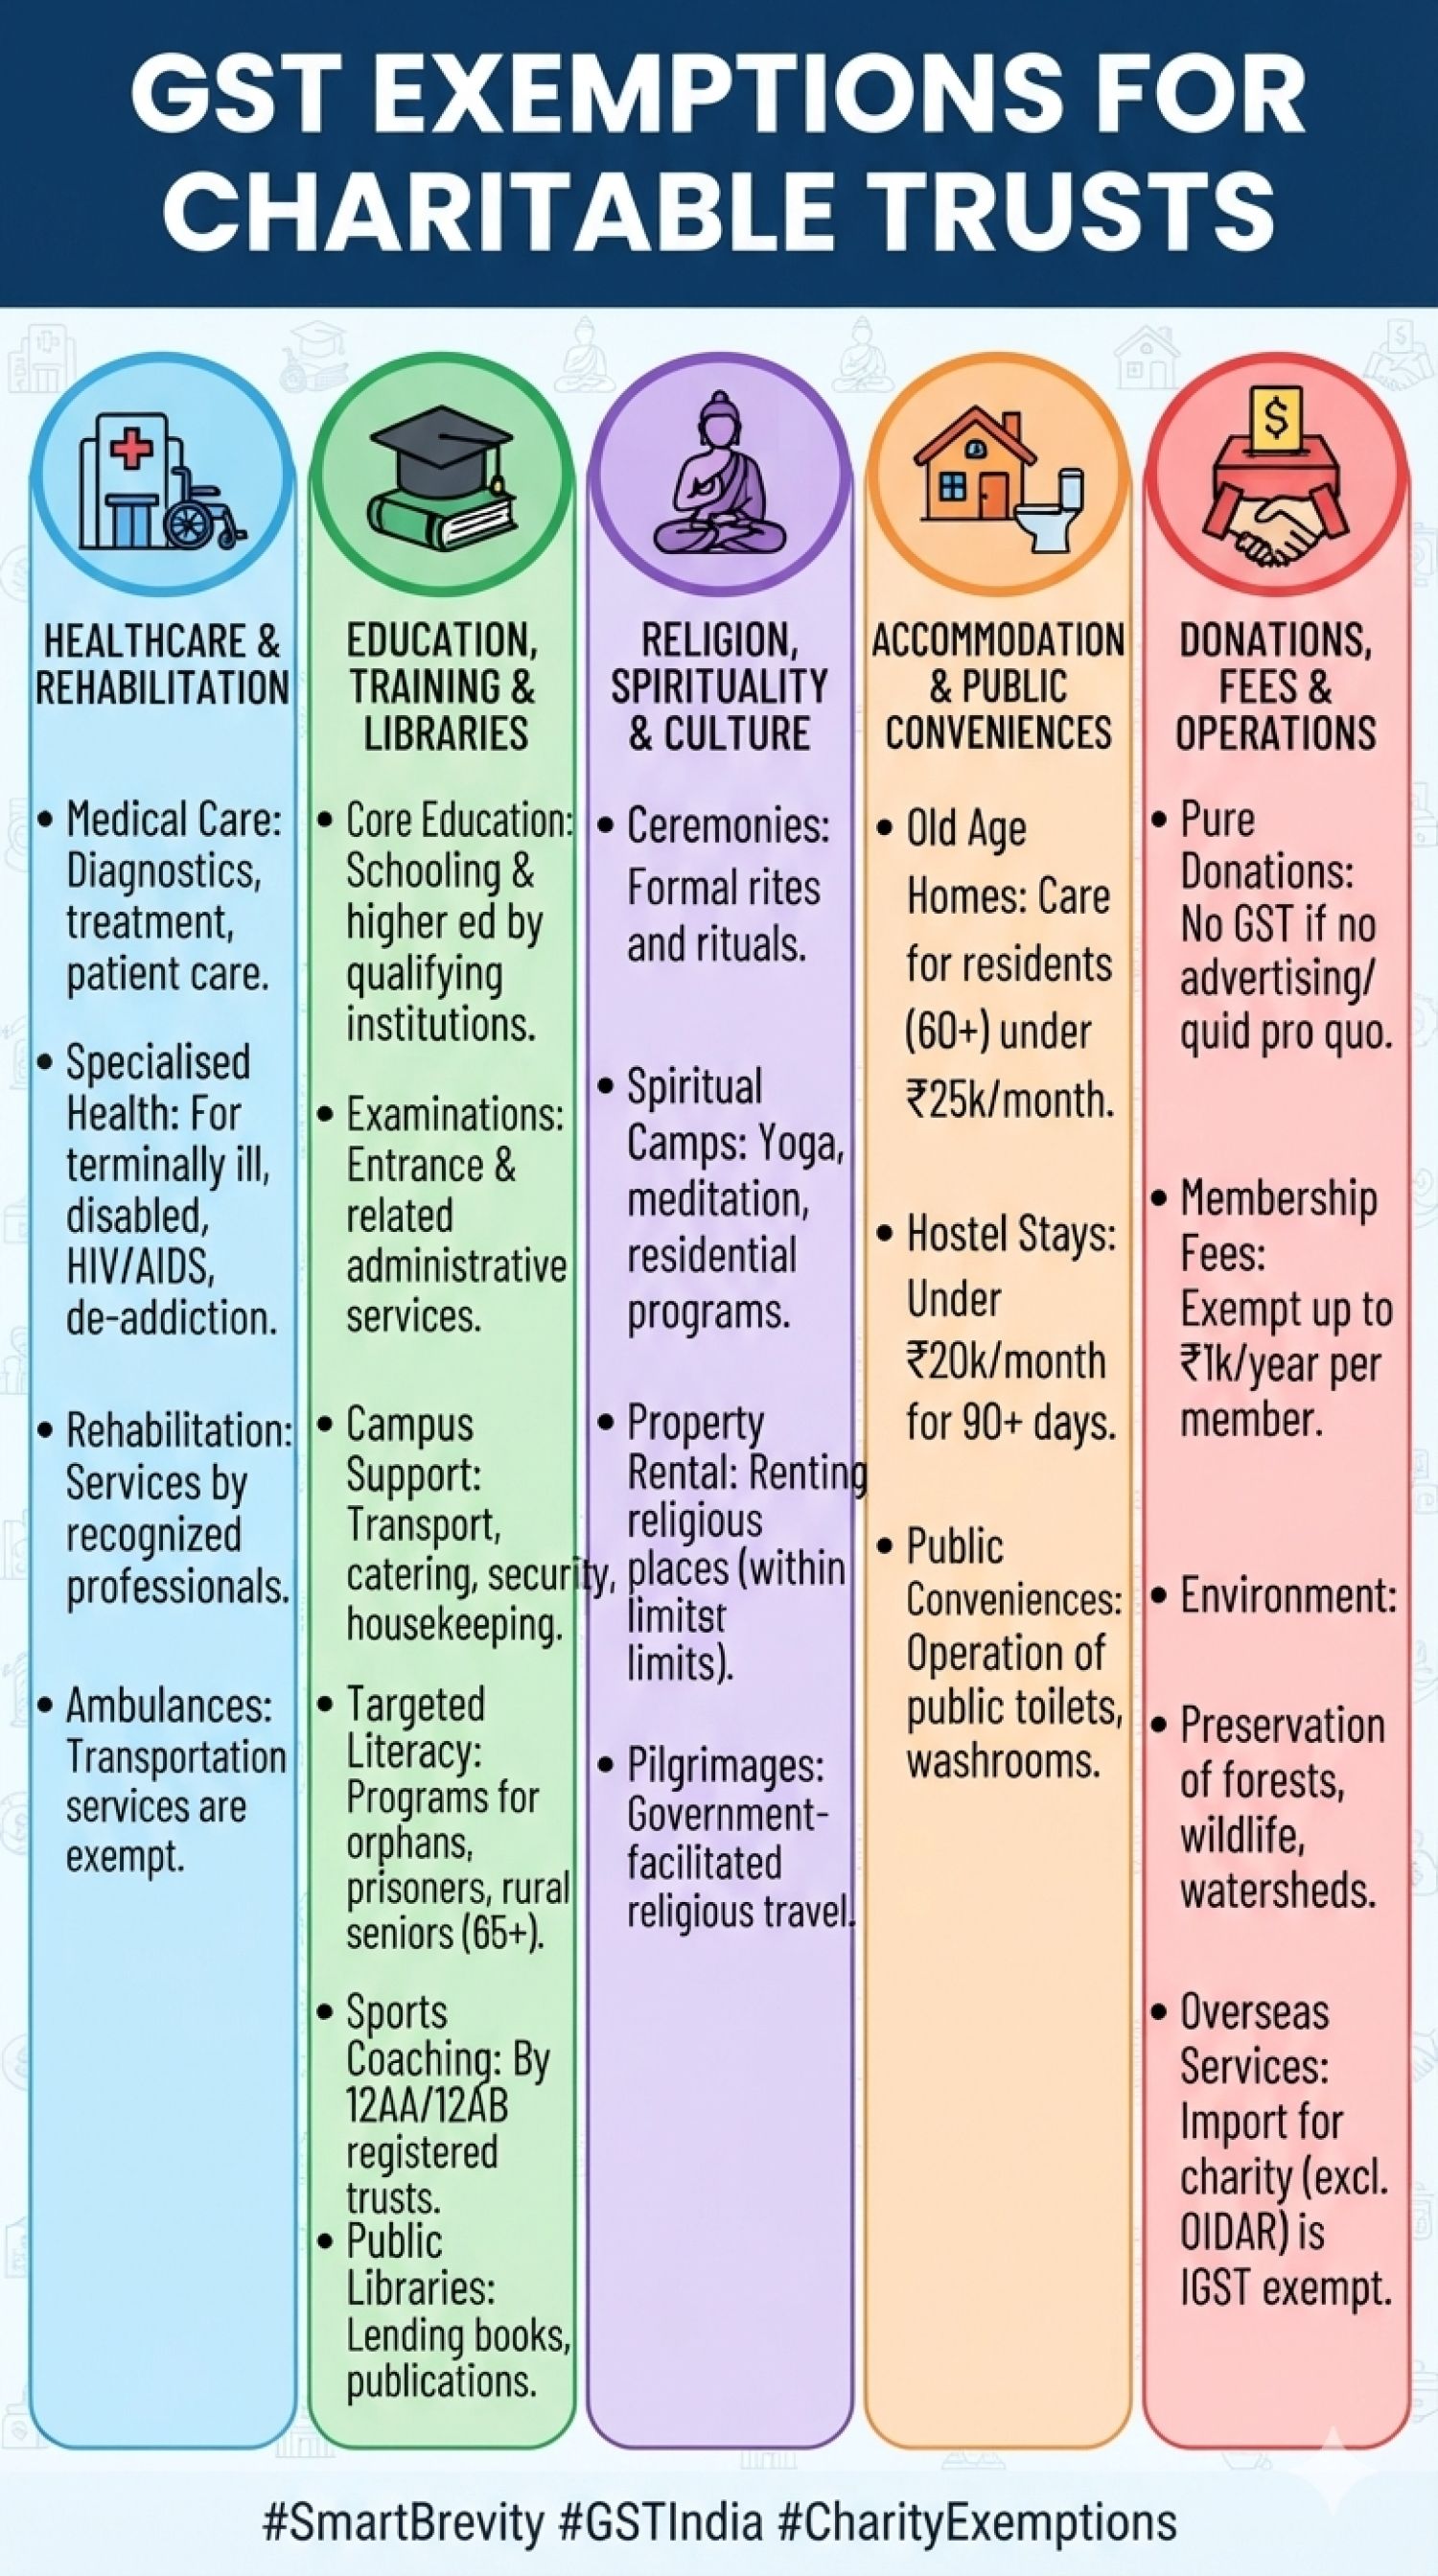
Being a charitable trust does not automatically make all income GST-exempt. Exemption depends on the specific nature of the activity. Sale of books, souvenirs, marathon participation fees, commercial renting, sponsorship arrangements, or other business-like activities may still attract GST. the following major GST exemptions are available:
1. Charitable Activities Exemption
Available to trusts/institutions registered under Section 12AA/12AB of the Income-tax Act. Exempt activities include Public health services (care of terminally ill, disabled persons, HIV/AIDS patients, de-addiction services).Public awareness of preventive health and family planning. Advancement of religion, spirituality, or yoga. Educational and skill development programs for Orphans and homeless children, Abused or traumatized persons, Prisoners, Senior citizens (65+) residing in rural areas. Preservation of environment, forests, wildlife, and watersheds.
2. Donations
Pure donations are not subject to GST since they are not consideration for any supply, provided there is no quid pro quo or advertising benefit to the donor.
3. Religious Activities
Exempt Religious ceremonies, Yoga, meditation, and spiritual camps. And Residential spiritual programs where the primary objective is religious/spiritual advancement.
4. Renting of Religious Places
Exempt when provided by eligible religious/charitable trusts for religious purposes, subject to prescribed limits.
5. Healthcare Services
Exempt Healthcare services by hospitals, clinics, nursing homes, clinical establishments, doctors, and paramedics. Ambulance services. and Treatment, diagnosis, and patient care services.
6. Rehabilitation Services
Services provided by recognized rehabilitation professionals at rehabilitation centres, medical establishments, and institutions established by registered charitable trusts are exempt.
7. Educational Institutions
Exempt Education provided by qualifying educational institutions, Entrance examinations and Certain support services such as transportation, catering, security, housekeeping, admission, and examination-related services.
8. Old Age Homes
Services provided by old age homes run by registered charitable entities to residents aged 60 years or above are exempt where charges do not exceed INR 25,000 per month per member, including boarding, lodging, and maintenance.
9. Public Libraries
Lending of books, publications, and knowledge-enhancing materials by public libraries is exempt.
10. Religious Pilgrimage
Services relating to Government-facilitated religious pilgrimages under bilateral arrangements are exempt.
11. Public Conveniences
Services by way of providing toilets, washrooms, urinals, and similar public conveniences are exempt.
12. Membership Fee Exemption
Membership fees up to INR 1,000 per member per year charged by eligible non-profit organizations to their members are exempt.
13. Sports Training
Training or coaching in sports provided by charitable entities registered under Section 12AA/12AB is exempt.
14. Import of Services for Charitable Activities
Specified services received from overseas by a registered charitable trust for carrying out charitable activities are exempt from IGST (except OIDAR services).
15. Hostel Accommodation (from 15 July 2024)
Exempt if Charges do not exceed INR 20,000 per person per month, and Continuous stay is 90 days or more.