Table of Contents
- Form 3cd - Clause 12: Presumptive Income And Deemed Profit Provisions
- Detailed Explanation Of Sections Covered Under Clause 12
- Auditor's Verification Under Clause 12
- Practical Tax Audit Reporting Example
- Relevance For Tax Audit
- Practical Point For Ca/ip Professionals
- Important Point For Tax Auditors
- Tax Audit Qualifications In Form 3ca / 3cb
- In Summary:
Form 3CD - Clause 12: Presumptive Income and Deemed Profit Provisions
Clause 12 of Form 3CD requires the Tax Auditor to report whether the assessee has opted for any special presumptive taxation provisions under the Income-tax Act, where income is computed on a prescribed basis rather than on actual books of account.
The auditor is required to disclose the relevant section, nature of business, and the amount of income computed under such provisions.
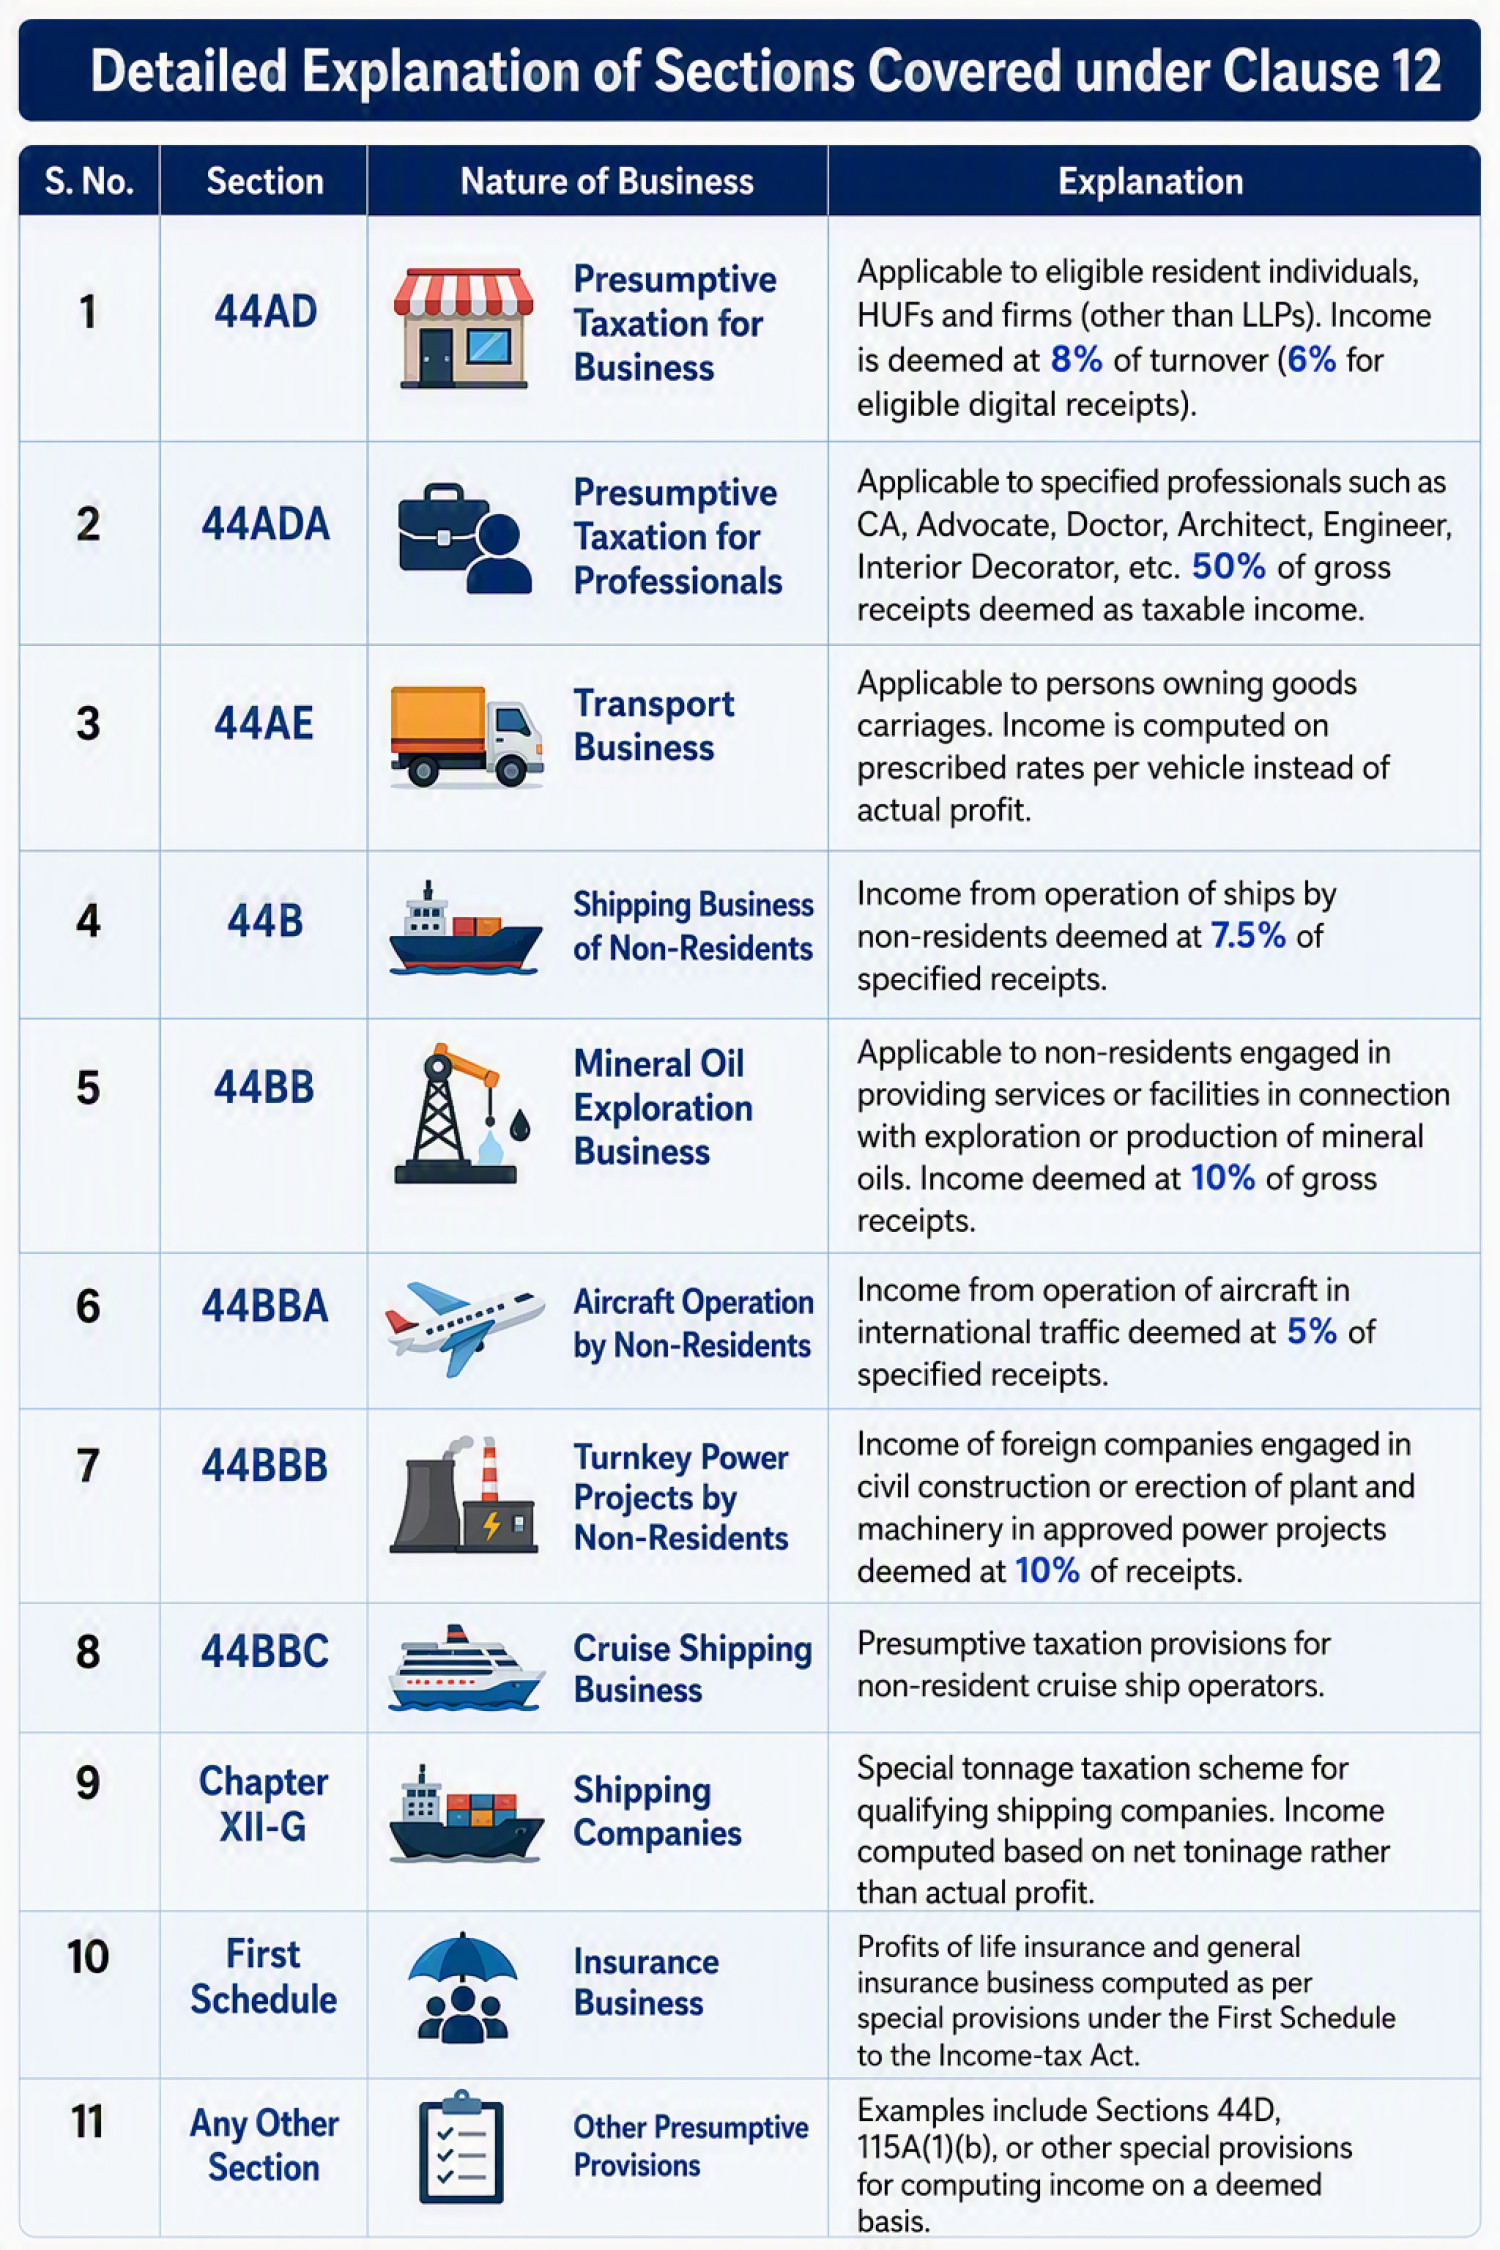
Detailed Explanation of Sections Covered under Clause 12
|
S. No. |
Section |
Nature of Business |
Explanation |
|
1 |
44AD |
Presumptive Taxation for Business |
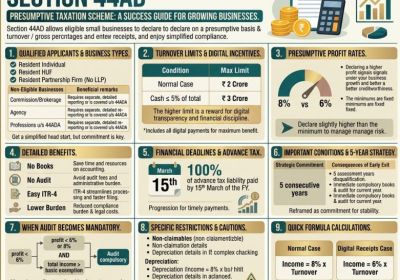
Applicable to eligible resident individuals, HUFs and firms (other than LLPs). Income is deemed at 8% of turnover (6% for eligible digital receipts). |
|
2 |
44ADA |
Presumptive Taxation for Professionals |
Applicable to specified professionals such as CA, Advocate, Doctor, Architect, Engineer, Interior Decorator, etc. 50% of gross receipts deemed as taxable income. |
|
3 |
44AE |
Transport Business |
Applicable to persons owning goods carriages. Income is computed on prescribed rates per vehicle instead of actual profit. |
|
4 |
44B |
Shipping Business of Non-Residents |
Income from operation of ships by non-residents deemed at 7.5% of specified receipts. |
|
5 |
44BB |
Mineral Oil Exploration Business |
Applicable to non-residents engaged in providing services or facilities in connection with exploration or production of mineral oils. Income deemed at 10% of gross receipts. |
|
6 |
44BBA |
Aircraft Operation by Non-Residents |
Income from operation of aircraft in international traffic deemed at 5% of specified receipts. |
|
7 |
44BBB |
Turnkey Power Projects by Non-Residents |
Income of foreign companies engaged in civil construction or erection of plant and machinery in approved power projects deemed at 10% of receipts. |
|
8 |
44BBC |
Cruise Shipping Business |
Presumptive taxation provisions for non-resident cruise ship operators. |
|
9 |
Chapter XII-G |
Shipping Companies |
Special tonnage taxation scheme for qualifying shipping companies. Income computed based on net tonnage rather than actual profit. |
|
10 |
First Schedule |
Insurance Business |
Profits of life insurance and general insurance business computed as per special provisions under the First Schedule to the Income-tax Act. |
|
11 |
Any Other Section |
Other Presumptive Provisions |
Examples include Sections 44D, 115A(1)(b), or other special provisions for computing income on a deemed basis. |
Auditor's Verification under Clause 12
|
Particulars to Verify |
Auditor's Responsibility |
|
Eligibility of Assessee |
Verify whether conditions of the relevant presumptive section are satisfied. |
|
Nature of Business |
Confirm that the business falls within the scope of the respective section. |
|
Turnover/Gross Receipts |
Check turnover and receipts used for deemed income calculation. |
|
Presumptive Income Calculation |
Verify correctness of income declared under the applicable section. |
|
Maintenance of Books |
Ensure compliance with provisions relating to maintenance of books when income lower than presumptive income is declared. |
|
Audit Requirement |
Check whether audit becomes applicable when income is declared below prescribed presumptive rates. |
Practical Tax Audit Reporting Example
|
Situation |
Reporting under Clause 12 |
|
Trader having turnover of ₹1.50 crore opting for Section 44AD |
Report Section 44AD and income computed on presumptive basis. |
|
Chartered Accountant having professional receipts of ₹60 lakh opting for Section 44ADA |
Mention Section 44ADA and deemed income offered. |
|
Transport operator owning goods vehicles and declaring income under Section 44AE |
Report Section 44AE and vehicle-wise computation details. |
|
Non-resident shipping company taxable under Section 44B |
Report income computed as per Section 44B. |
Relevance for Tax Audit
Clause 12 is important because it informs the Income Tax Department that:
- Income is not calculated under normal accounting provisions.
- Special presumptive taxation provisions have been used.
- The auditor has verified the applicability of those provisions.
Practical Point for CA/IP Professionals
When preparing Form 3CD:
- Check whether the assessee has opted for any presumptive scheme.
- Verify eligibility conditions.
- Report the relevant section and income amount under Clause 12.
- If no presumptive or special computation section applies, Clause 12 may be reported as "Not Applicable".
Important Point for Tax Auditors
Clause 12 is mainly a disclosure clause. The auditor should ensure that:
- The correct presumptive section has been applied.
- Eligibility conditions are fulfilled.
- Income has been computed as per the prescribed provisions.
- Appropriate disclosures have been made in the return and Form 3CD.
- Where the assessee departs from the presumptive scheme, consequent audit and book-keeping requirements have been complied with.
Tax Audit Qualifications in Form 3CA / 3CB
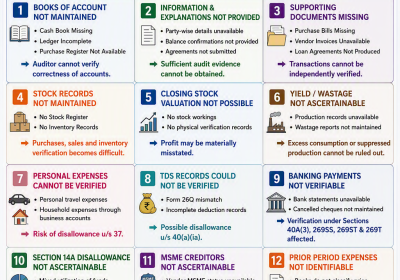
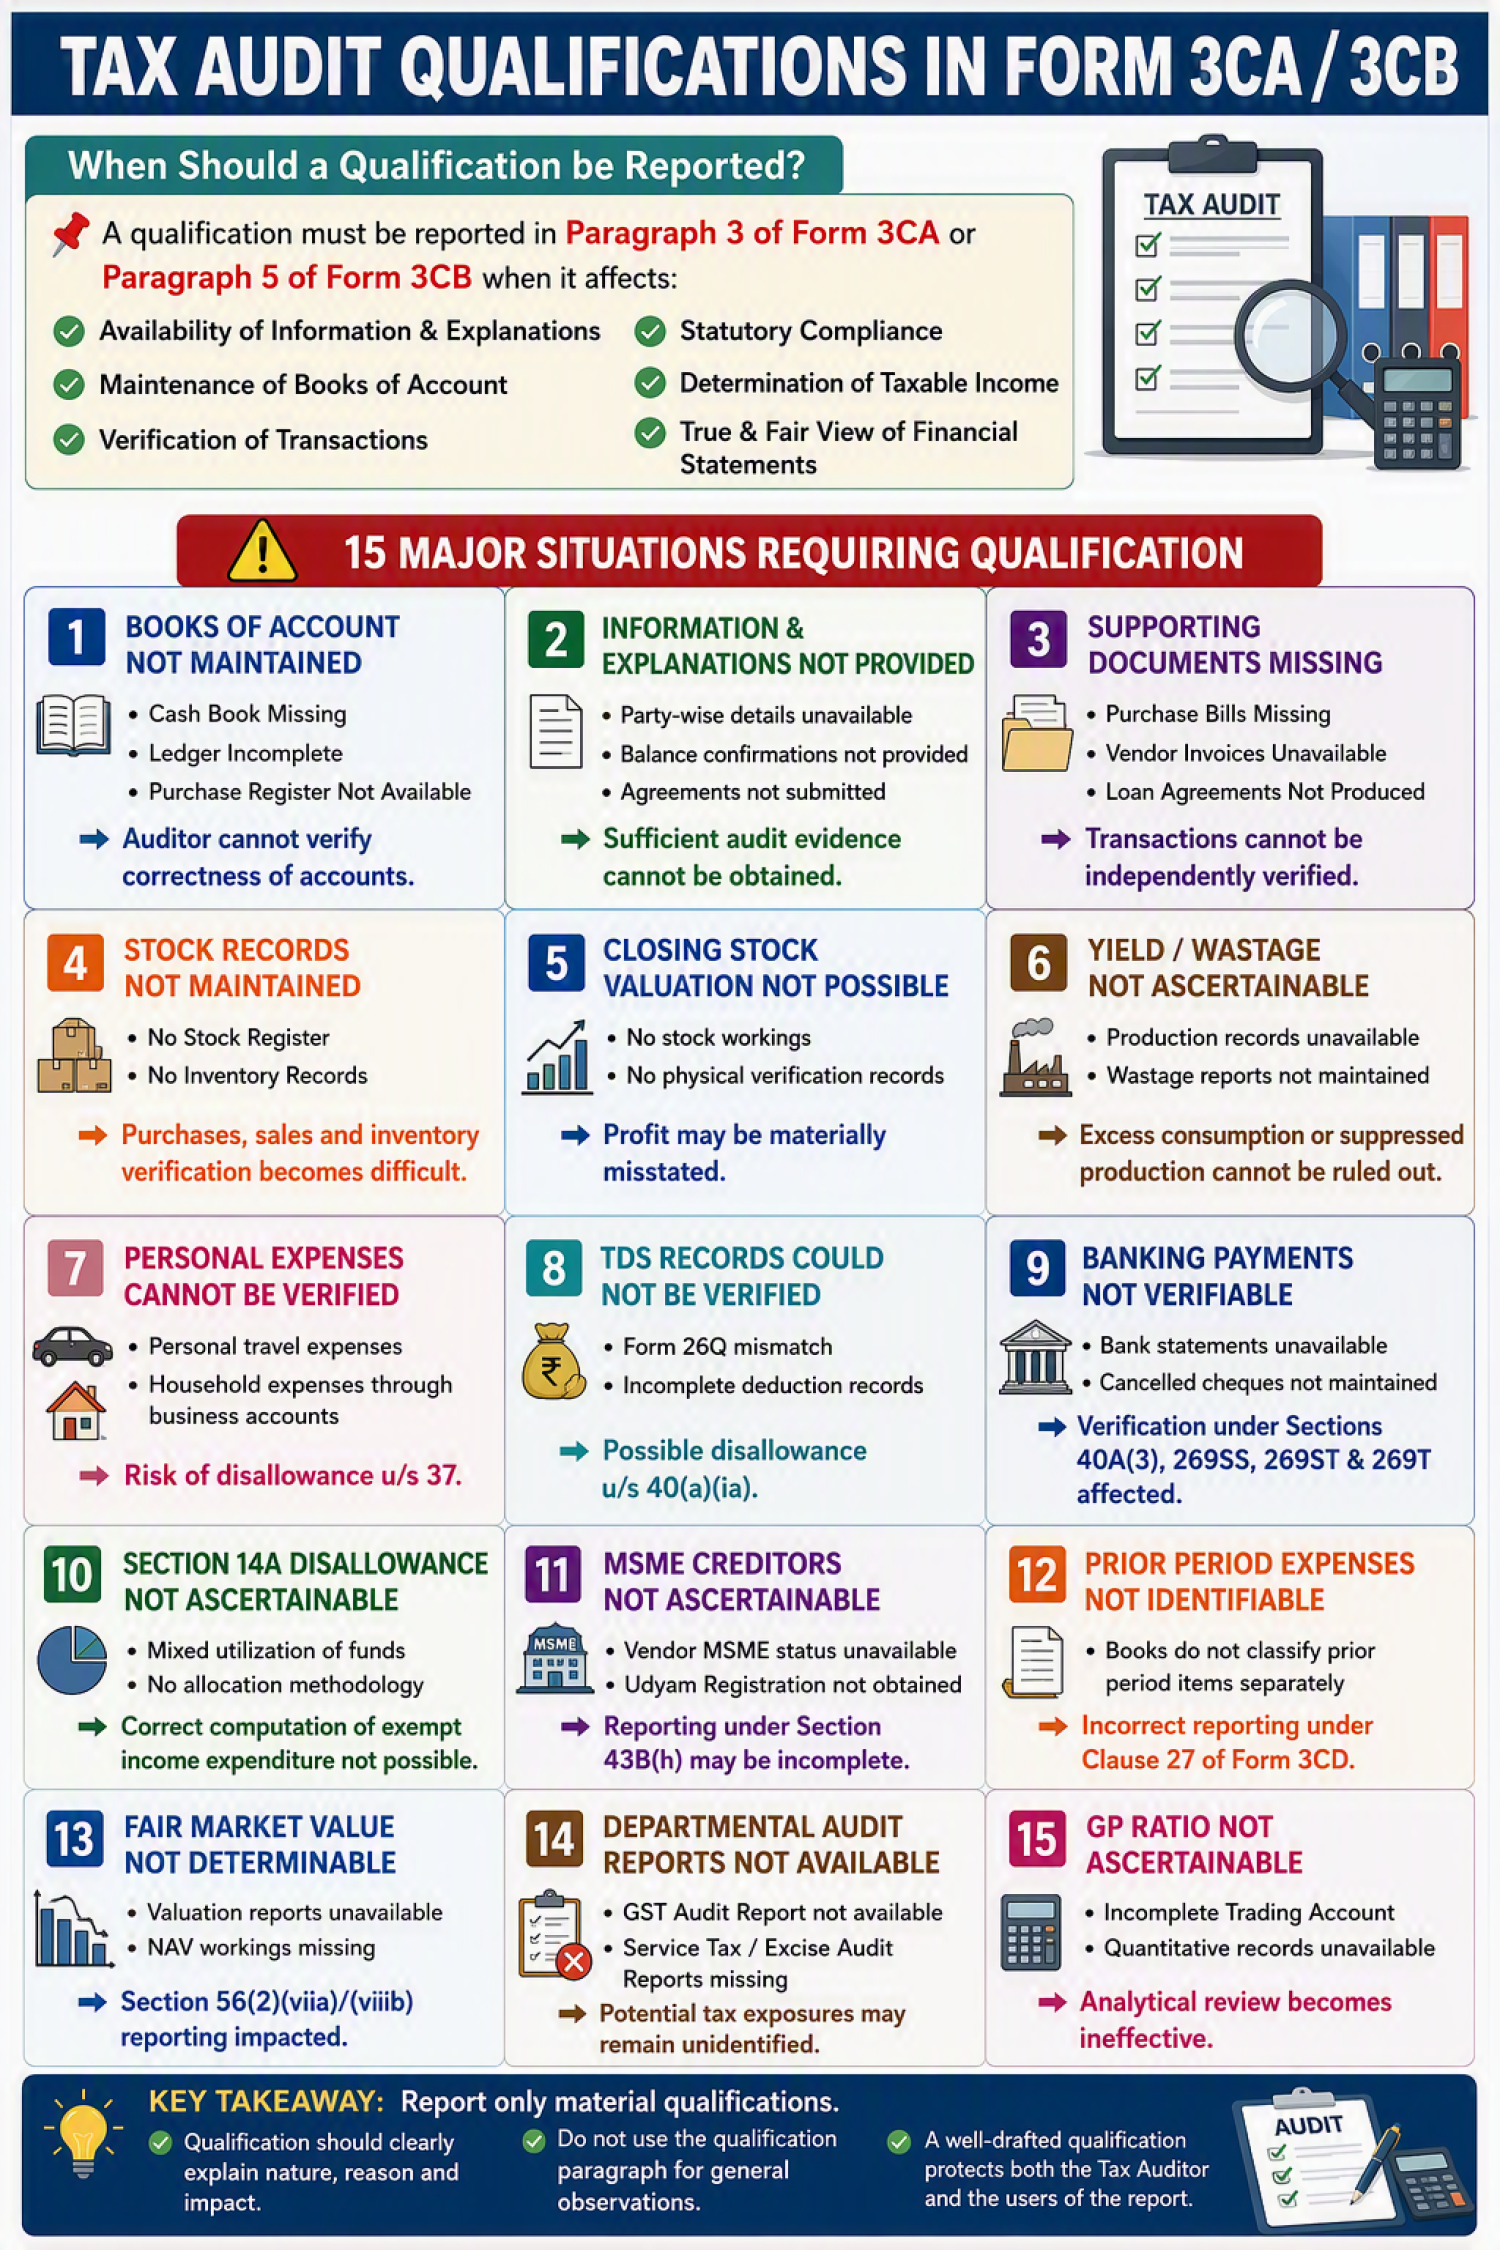
- A qualification in a Tax Audit Report (Form 3CA/3CB) is required when the tax auditor is unable to obtain sufficient evidence or verify important financial and tax-related information. Such qualifications are reported in Paragraph 3 of Form 3CA or Paragraph 5 of Form 3CB. They generally affect the maintenance of books of account, verification of transactions, statutory compliance, determination of taxable income, and the true and fair view of financial statements.
- 15 major situations where a qualification may become necessary. Common examples include non-maintenance of books of account, absence of stock records, inability to verify closing stock, missing supporting documents, non-availability of bank statements, non-verification of TDS records, and lack of information from the assessee. In these cases, the auditor cannot independently verify the accuracy and completeness of financial records, increasing the risk of incorrect tax reporting.
- Qualifications may also arise when specific tax provisions cannot be properly applied. Examples include inability to determine Section 14A disallowance, ascertain MSME creditor status, identify prior period expenses, determine fair market value, or verify gross profit ratios. Such deficiencies can impact disclosures required under Form 3CD and may lead to potential additions, disallowances, or incomplete reporting.
- The key principle is that an auditor should report only material qualifications, clearly stating the nature of the issue, the reason for the qualification, and its possible impact on taxable income or compliance. A well-drafted qualification protects both the tax auditor and the users of the audit report by ensuring transparency about limitations encountered during the audit process.
In summary:
- Clause 12 is a disclosure clause in Form 3CD for reporting income computed under presumptive taxation schemes (Sections 44AD, 44ADA, 44AE, etc.) or other special computation provisions such as shipping, insurance, aircraft operations, oil exploration, and similar businesses.
- In simple words, Clause 12 informs the Income-tax Department that the assessee's income is being computed under a special presumptive or deemed-profit scheme instead of the normal provisions of business income computation.