44AB(a), (b), (c), (d) or (e): Which Tax Audit Clause Applies? (FY 2025-26 / AY 2026-27)
Selecting the correct clause under Section 44AB is the first step in a tax audit. The clause reported in Clause 8 of Form 3CD reflects why the audit applies, while the choice between Form 3CA and Form 3CB is a separate decision based on whether the accounts are already audited under another law. For FY 2025-26, applicability continues to be governed by the Income-tax Act, 1961 and the existing reporting framework.
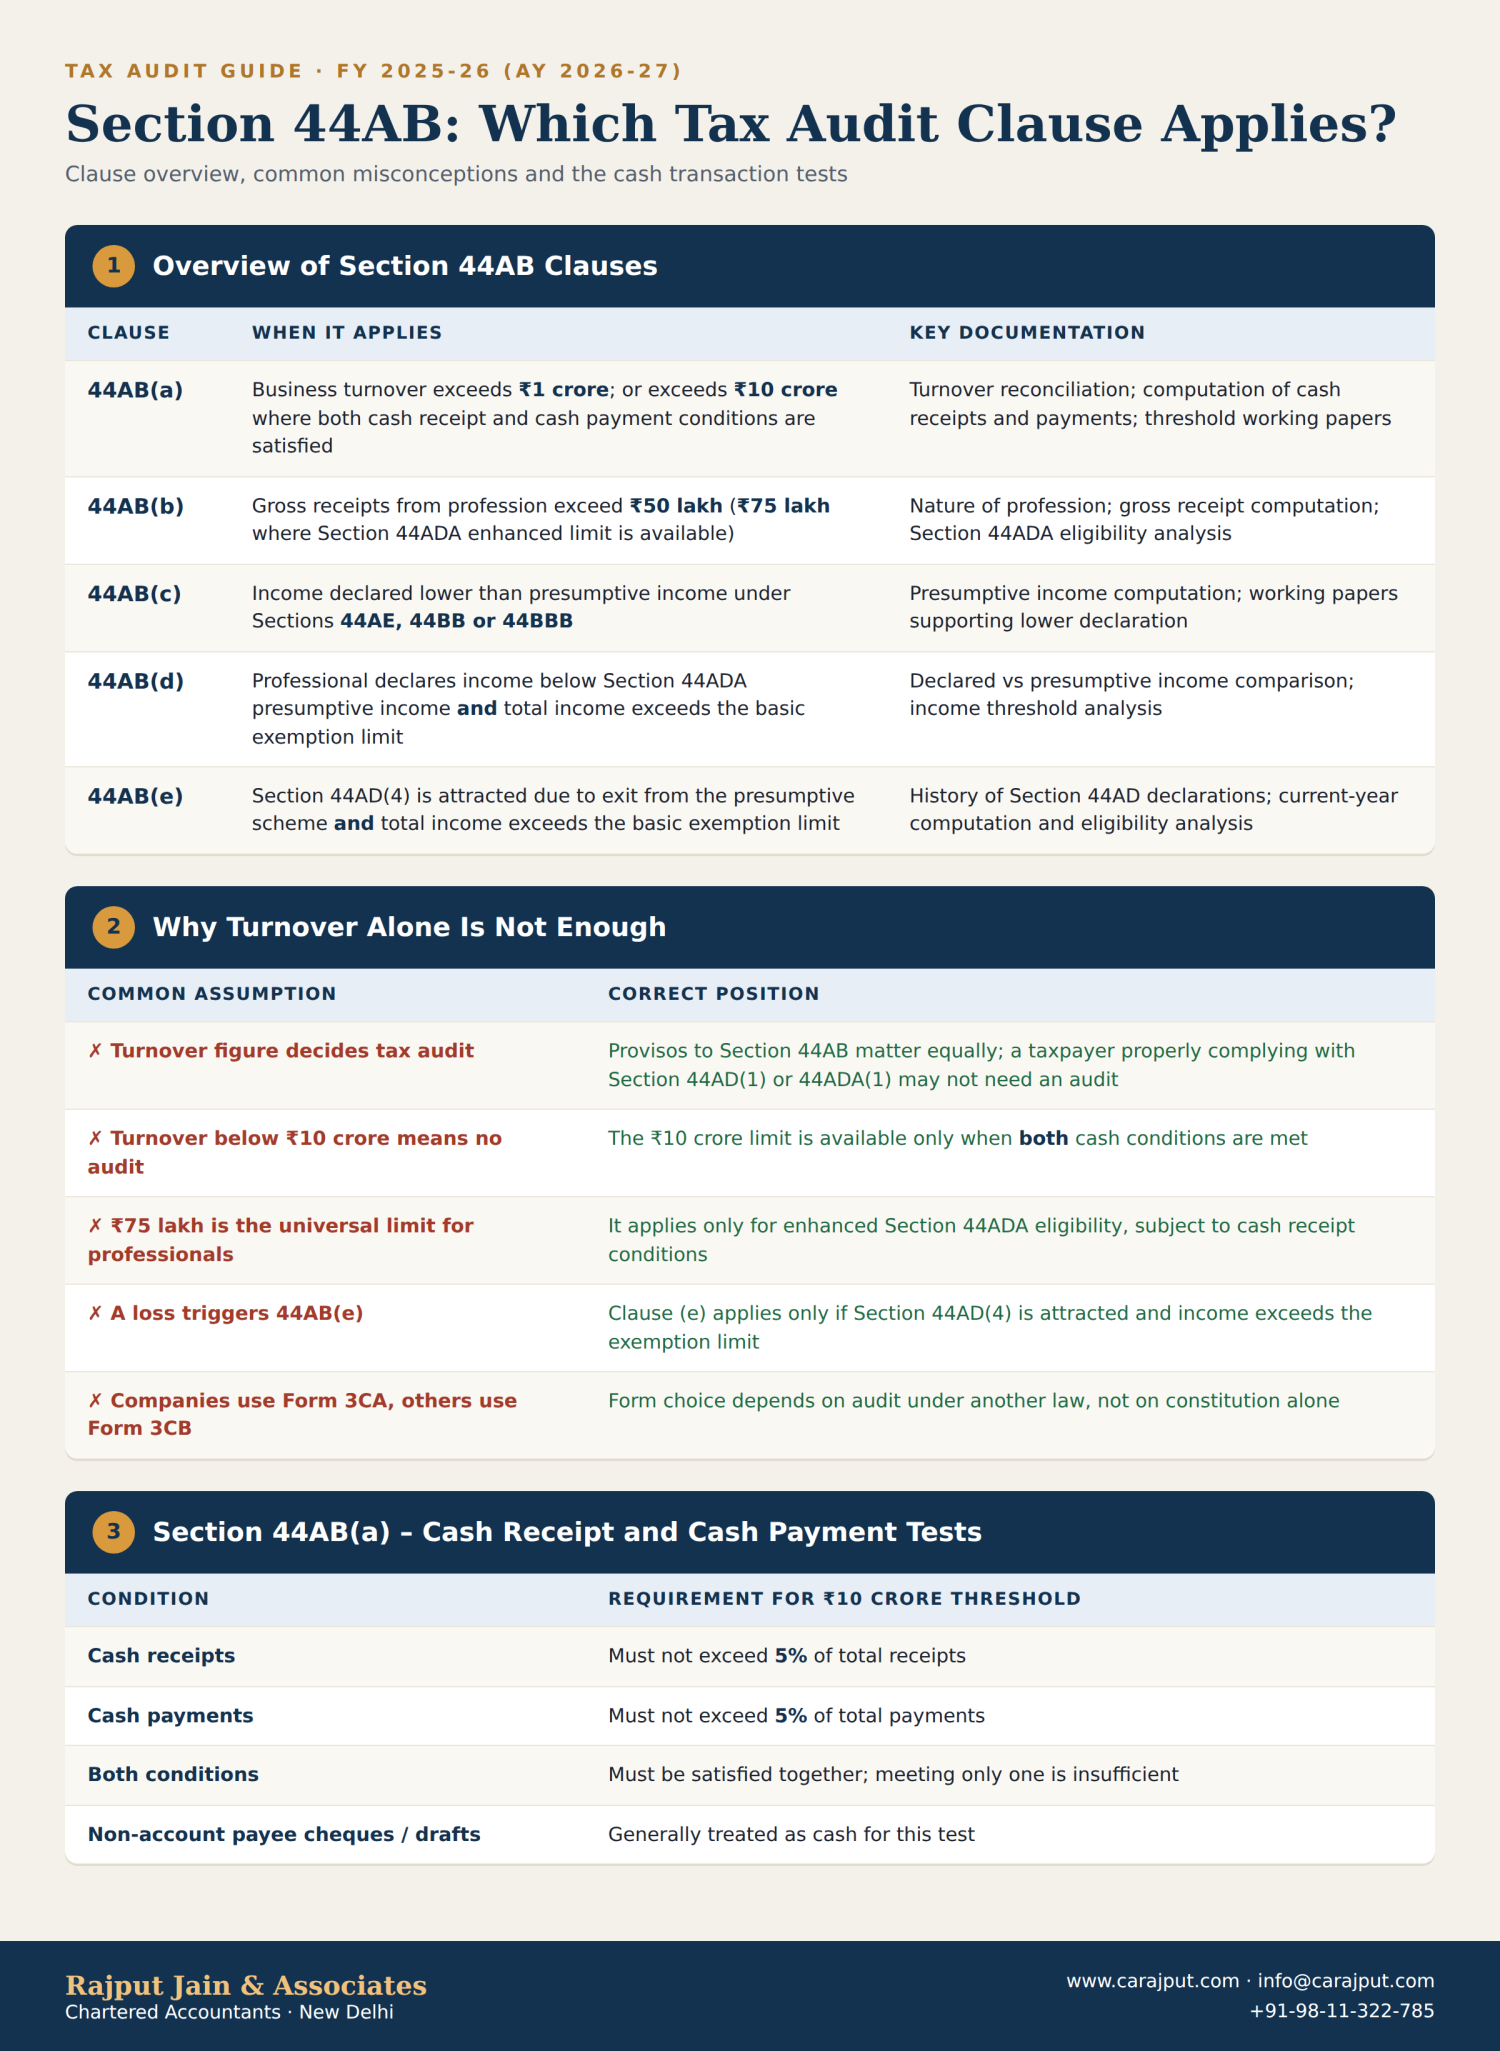
Table 1: Overview of Section 44AB Clauses
| Clause |
When It Applies |
Key Documentation |
| 44AB(a) |
Business turnover exceeds INR 1 crore; or exceeds ₹10 crore where both cash receipt and cash payment conditions are satisfied |
Turnover reconciliation; computation of cash receipts and payments; threshold working papers |
| 44AB(b) |
Gross receipts from profession exceed INR 50 lakh (INR 75 lakh where Section 44ADA enhanced limit is available) |
Nature of profession; gross receipt computation; Section 44ADA eligibility analysis |
| 44AB(c) |
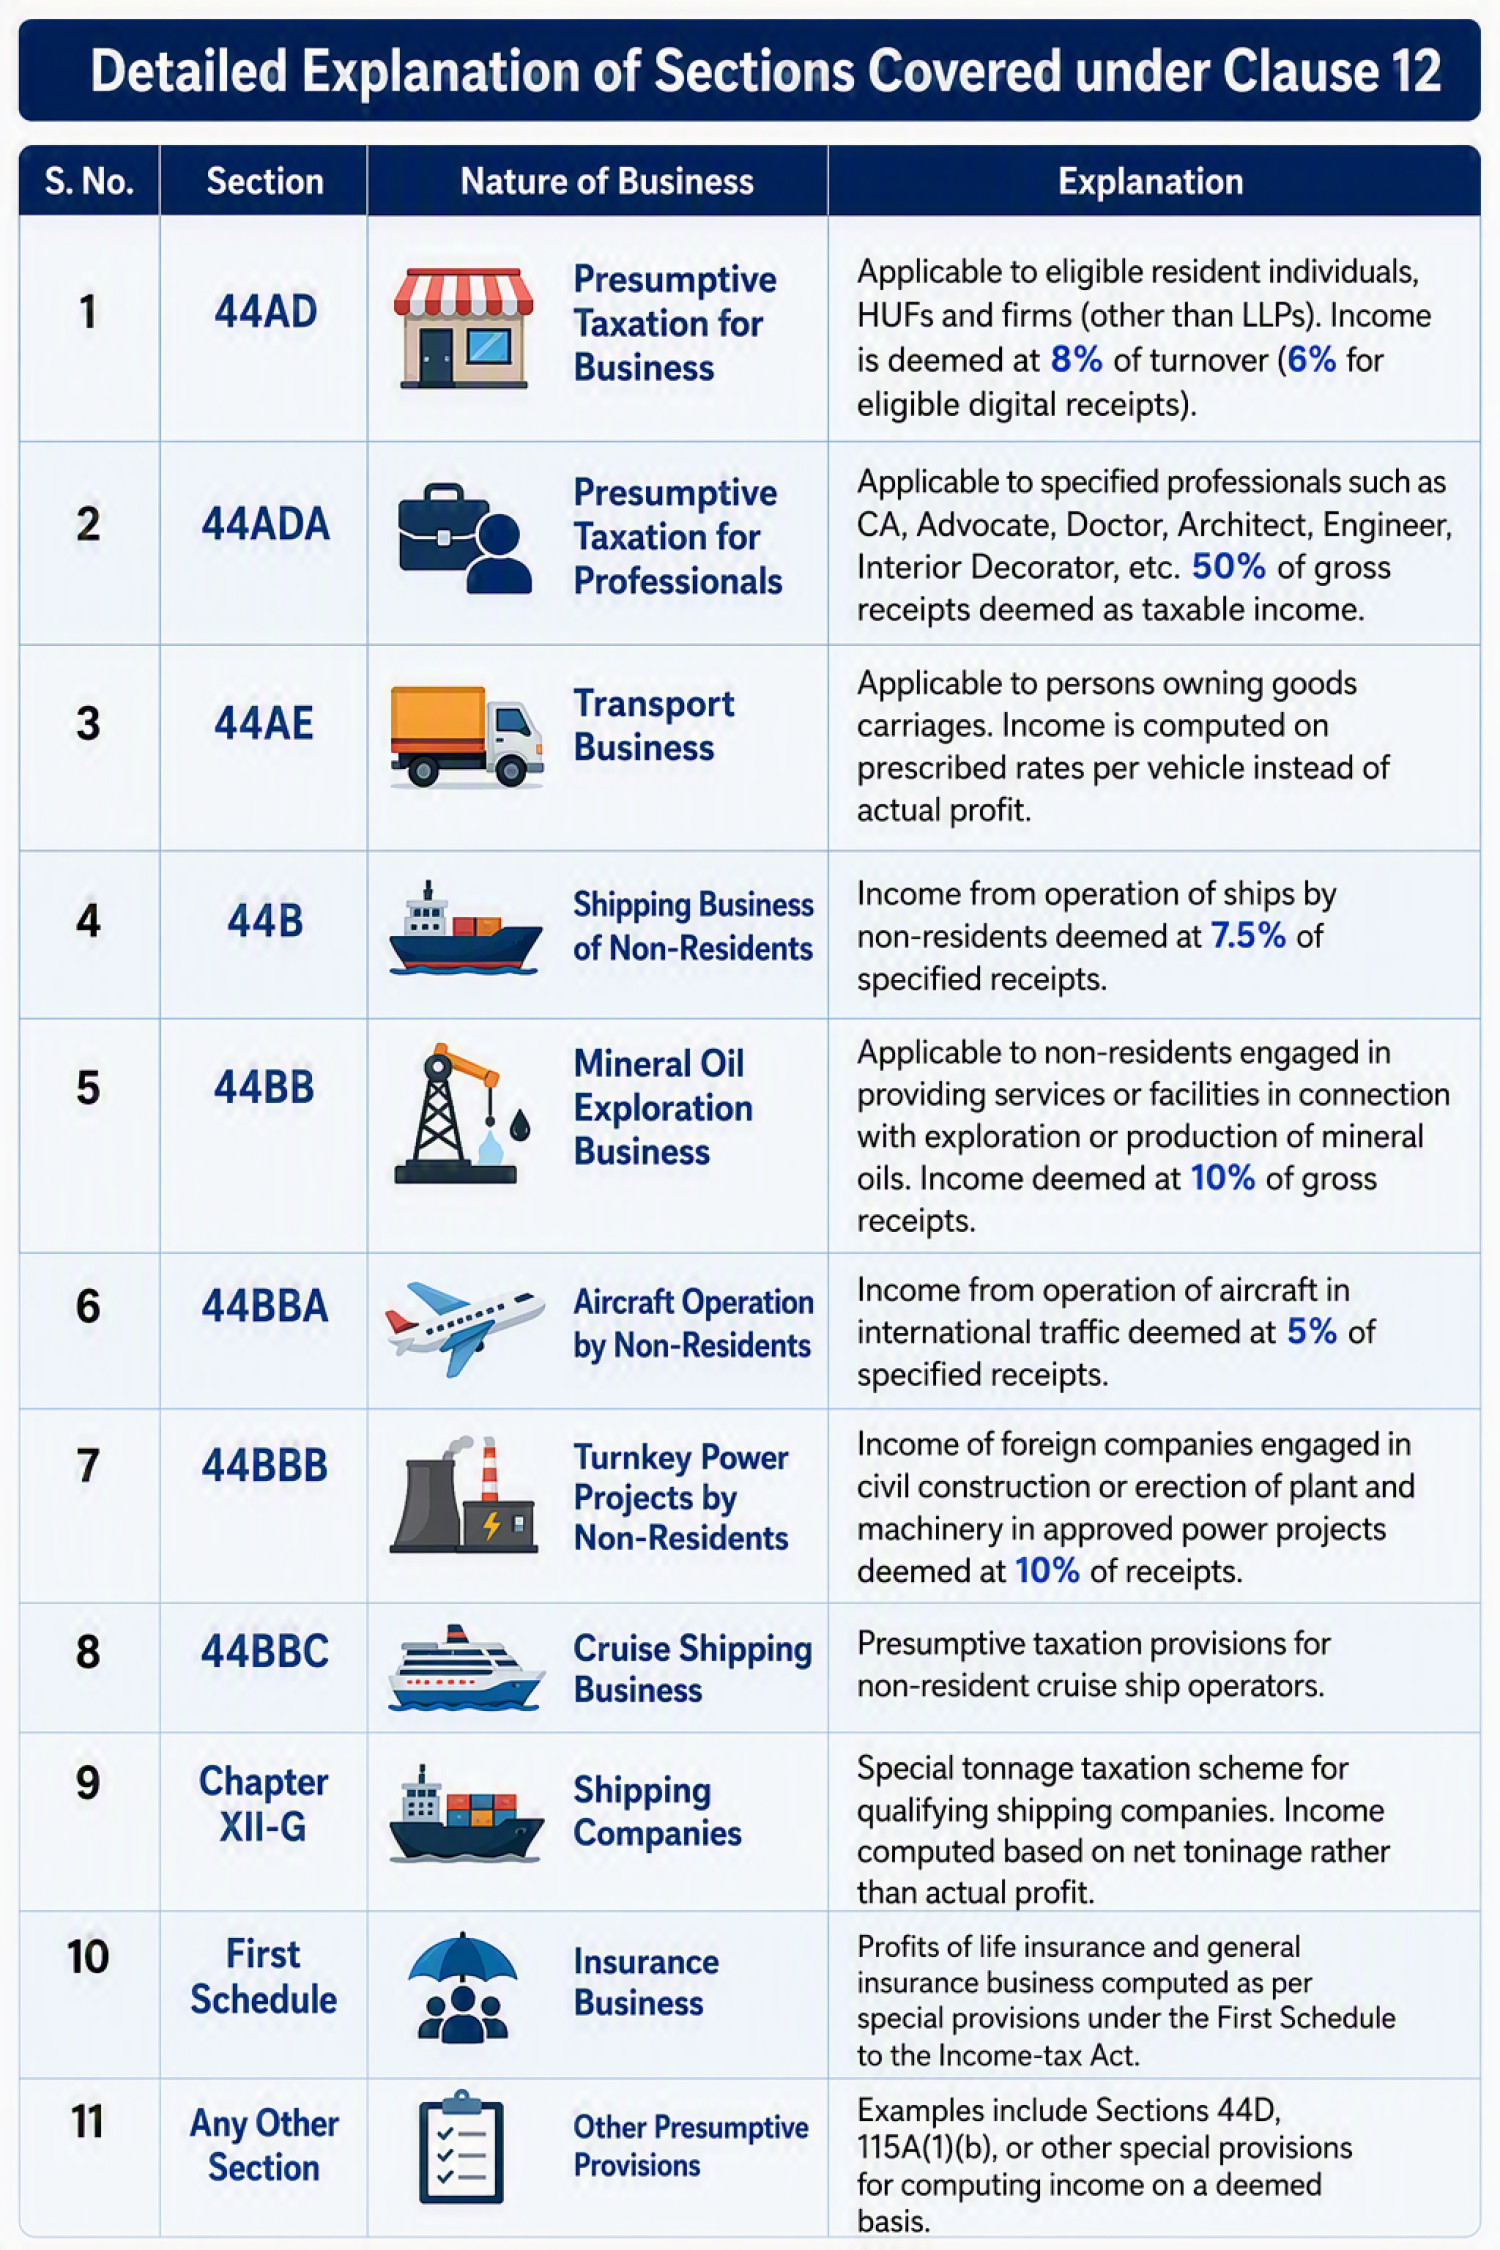
Income declared lower than presumptive income under Sections 44AE, 44BB or 44BBB |
Presumptive income computation; working papers supporting lower declaration |
| 44AB(d) |
Professional declares income below Section 44ADA presumptive income and total income exceeds the basic exemption limit |
Declared vs presumptive income comparison; income threshold analysis |
| 44AB(e) |
Section 44AD(4) is attracted due to exit from the presumptive scheme and total income exceeds the basic exemption limit |
History of Section 44AD declarations; current-year computation and eligibility analysis |
Table 2: Why Turnover Alone Is Not Enough
| Common Assumption |
Correct Position |
| Turnover figure decides tax audit |
Provisos to Section 44AB matter equally; a taxpayer properly complying with Section 44AD(1) or 44ADA(1) may not need an audit |
| Turnover below INR 10 crore means no audit |
The INR 10 crore limit is available only when both cash conditions are met |
| INR 75 lakh is the universal limit for professionals |
It applies only for enhanced Section 44ADA eligibility, subject to cash receipt conditions |
| A loss triggers 44AB(e) |
Clause (e) applies only if Section 44AD(4) is attracted and income exceeds the exemption limit |
| Companies use Form 3CA, others use Form 3CB |
Form choice depends on audit under another law, not on constitution alone |
Table 3: Section 44AB(a) – Cash Receipt and Cash Payment Tests
| Condition |
Requirement for INR 10 Crore Threshold |
| Cash receipts |
Must not exceed 5% of total receipts |
| Cash payments |
Must not exceed 5% of total payments |
| Both conditions |
Must be satisfied together; meeting only one is insufficient |
| Non-account payee cheques / drafts |
Generally treated as cash for this test |
Table 4: Illustrative Example
| Particulars |
Cash Amount |
Total Amount |
Cash Ratio |
Result |
| Receipts |
INR 20 lakh |
INR 8.40 crore |
2.38% |
Condition met |
| Payments |
INR 50 lakh |
INR 7.50 crore |
6.67% |
Condition fails |
| Conclusion |
|
|
|
INR 10 crore threshold unavailable; normal INR 1 crore threshold applies |
Table 5: Audit File Workings for Cash Test
| Working Paper Element |
Purpose |
| Included ledger accounts |
Shows what was counted as receipts/payments |
| Excluded items |
Explains what was left out and why |
| Basis of classification |
Justifies cash vs non-cash treatment |
| Reconciliation of percentages |
Lets the reviewer verify calculations independently from the books |
Table 6: Sections 44AB(b) and 44AB(d) – Understanding the ₹75 Lakh Limit
| Factor |
Relevance to Section 44ADA Eligibility |
| Residential status |
Only residents can opt for Section 44ADA |
| Nature of profession |
Must be a specified profession under Section 44AA(1) |
| Category of taxpayer |
Available to individuals, HUFs and partnership firms (not LLPs) |
| Cash receipts |
Enhanced INR 75 lakh limit applies only if cash receipts do not exceed 5% |
| Compliance with presumptive provisions |
Declared income must meet the presumptive rate, otherwise 44AB(d) must be evaluated |
| Scenario |
Outcome |
| Resident professional, receipts INR 62 lakh, meets Section 44ADA conditions |
Tax audit may not be required |
| Taxpayer not eligible for Section 44ADA, receipts below ₹75 lakh but above INR 50 lakh |
Cannot avoid tax audit under 44AB(b) |
| Income declared below presumptive rate and total income above exemption limit |
Evaluate under 44AB(d) |
Table 7: Section 44AB(e) – Section 44AD History Sheet
| Assessment Year |
Turnover |
Applicable Section |
Income Declared |
Return Filing Details |
| AY 20XX-XX |
|
|
|
|
| AY 20XX-XX |
|
|
|
|
| AY 2026-27 |
|
|
|
|
| Situation |
Is 44AB(e) Attracted? |
| Trader earlier under Section 44AD, now exits the scheme within the lock-in period, income above exemption limit |
Yes, even if current turnover is below INR 1 crore |
| Business merely reports profit below 6%/8% |
Not by itself; check Section 44AD(4) first |
| Business reports an accounting loss |
Not automatically; statutory conditions must be satisfied |
Table 8: Tax Audit Clause vs Form 3CA / 3CB
| Form |
When Applicable |
Examples |
| Form 3CA |
Accounts already audited under any other law |
Companies Act, 2013; cooperative society laws; other statutory audits |
| Form 3CB |
No audit required under any other law |
Proprietorships, partnership firms and others not otherwise audited |
| Form 3CD |
Statement of particulars filed along with either form |
Does not replace 3CA or 3CB |
The auditor should document three separate determinations: why Section 44AB applies, which clause applies, and whether Form 3CA or 3CB is appropriate.
Table 9: Best Practice – Clause 8 Working Note Checklist
| Sr. No. |
Item to Document |
Cross-Reference |
| 1 |
Nature of business or profession |
Engagement file |
| 2 |
Entity constitution |
Registration documents |
| 3 |
Turnover or gross receipts |
Turnover reconciliation |
| 4 |
Cash receipt and payment analysis |
Cash test working |
| 5 |
Presumptive taxation eligibility |
Section 44AD/44ADA analysis |
| 6 |
Section 44AD history |
History sheet |
| 7 |
Income threshold verification |
Computation of income |
| 8 |
Status of audit under any other law |
Statutory audit report |
| 9 |
Final selection of Section 44AB clause |
Clause 8 working note |
| 10 |
Basis for choosing Form 3CA or 3CB |
Form selection note |
Table 10: Frequently Asked Questions
| Question |
Answer |
| Does turnover below INR 10 crore automatically eliminate tax audit liability? |
No. The INR 10 crore limit applies only when both cash conditions are met; presumptive and professional triggers must also be checked. |
| Is Section 44AB(e) applicable whenever a business incurs a loss? |
No. It applies only when Section 44AD(4) conditions and the income threshold are satisfied. |
| Does Form 3CA replace Form 3CD? |
No. Form 3CD contains the prescribed particulars; Form 3CA or 3CB is the audit report. |
Conclusion
Selecting the correct Section 44AB clause is not a mechanical exercise based on turnover alone. Cash thresholds, presumptive taxation eligibility, Section 44AD history, income declarations and audit under other laws must all be evaluated before finalising Clause 8 of Form 3CD. Proper documentation at this stage reduces reporting errors and supports peer review, quality review and reassessment proceedings.
Need help determining tax audit applicability for FY 2025-26? Rajput Jain & Associates, Chartered Accountants, assists businesses and professionals with tax audits, Form 3CA/3CB/3CD reporting and presumptive taxation reviews. Call +91-98-11-322-785, email info@carajput.com, or visit www.carajput.com.
Disclaimer: The content of this post isn't considered to be professional or legal advice, We aren't responsible for any damages arising from your access to the location content & must not be relied on or used as a substitute for legal advice from a lawyer professional in your jurisdiction. CARajput is among India's big digital compliance services platform which committed to helping people have started & developed their businesses. We had started with the goal of creating it easier for start-ups to start out their business. Our main aim is to assist the businessman with applicable laws & regulations compliance and providing support at each & every level to make sure the business stays compliant and growing continuously. For any query, help or feedback you may in touch on singh@carajput.com or Call or what’s-up on 9-555-555-480