Table of Contents
CBDT Proposes New Rule 281A & Form 173A for Exemption on Government Securities Income: Detailed Analysis
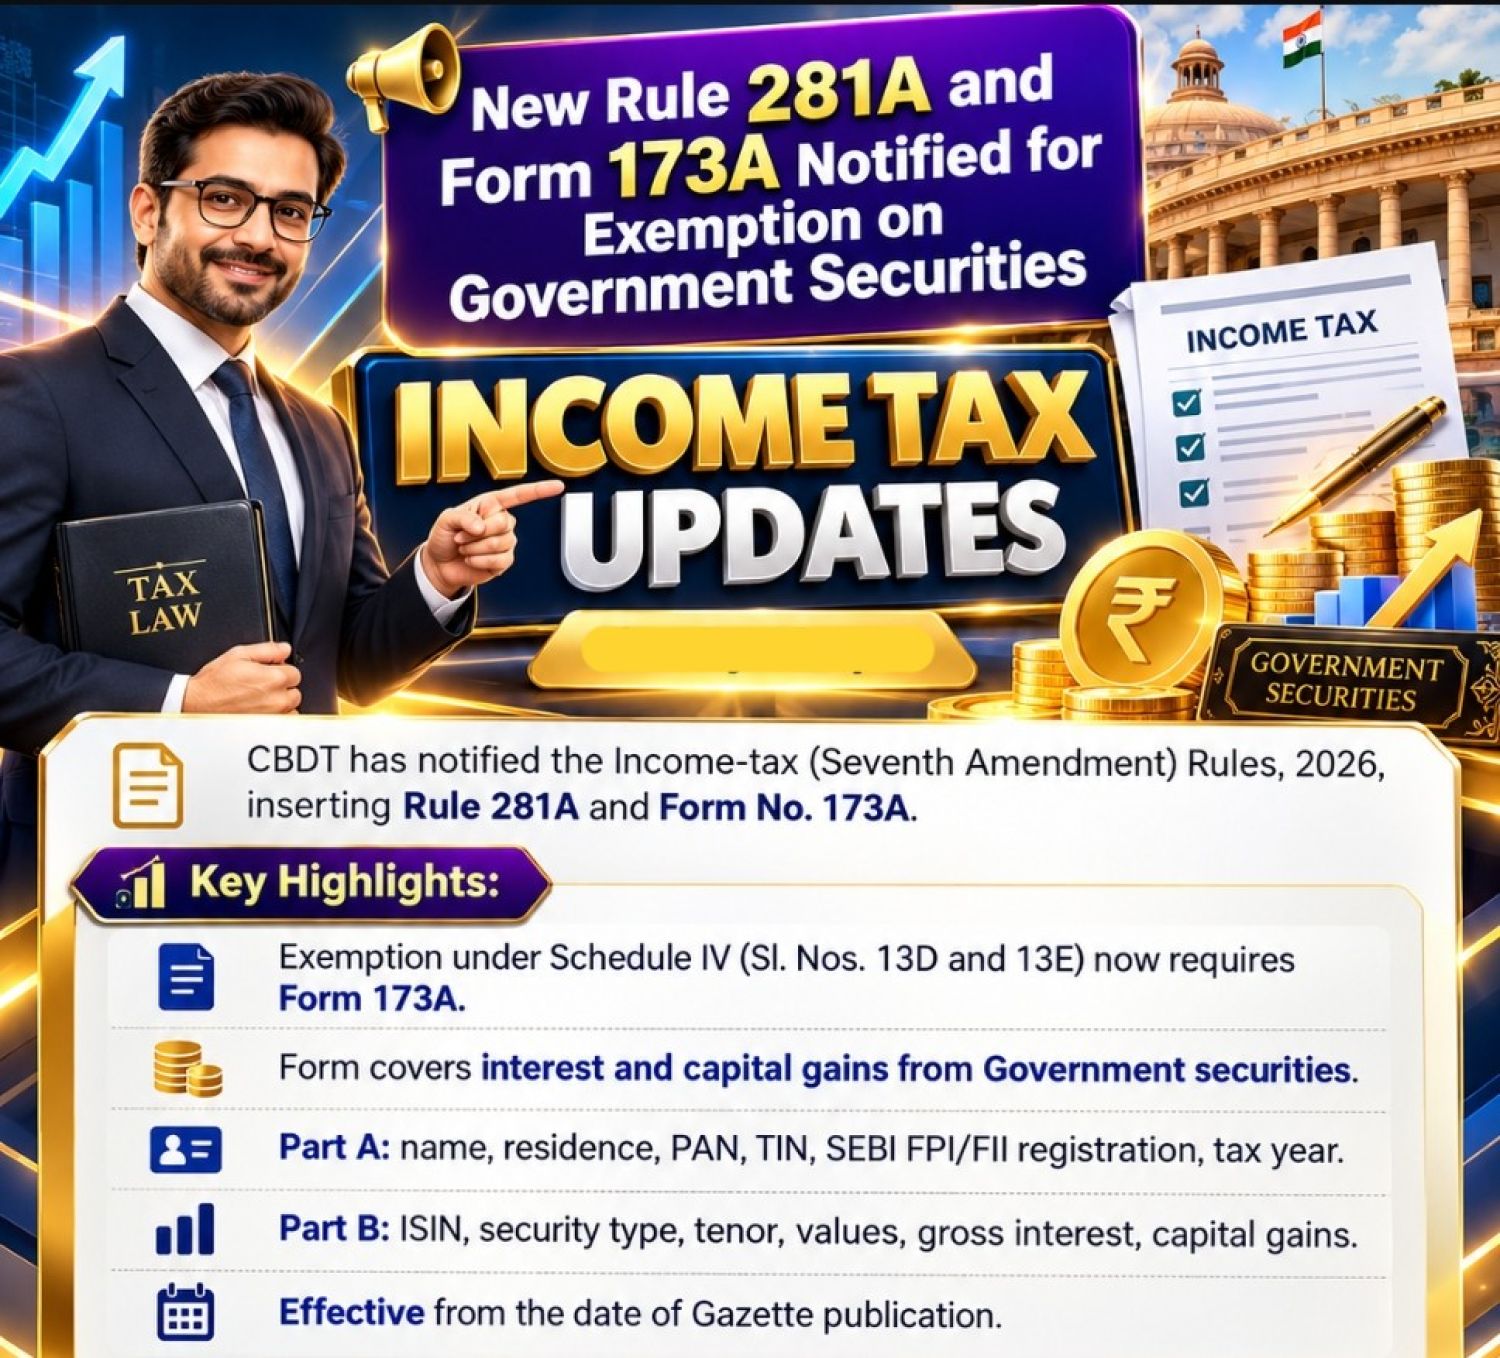
The Central Board of Direct Taxes has issued draft Notification-no-137-2026 proposing the Income-tax (Seventh Amendment) Rules, 2026. The proposal seeks to introduce a new Rule 281A and Form No. 173A under the Income-tax Act, 2025 to facilitate exemption claims on specified interest income and capital gains arising from Government Securities. The amendment became effective from 19 October 2026 and creates a reporting requirement for taxpayers claiming specified exemptions on interest income and capital gains from Government securities.
Objective of the Amendment
The proposed amendment aims to create a standardized reporting mechanism for claiming exemption under Schedule IV (Table Serial No. 13D) and Schedule IV (Table Serial No. 13E) of the Income-tax Act, 2025. The CBDT intends to ensure that eligible investors furnish prescribed information before claiming exemption on Interest income earned from Government Securities. And Capital gains arising from Government Securities.
What is Rule 281A?
A new Rule 281A is proposed to be inserted in the Income-tax Rules, 2026. The proposed rule provides that Any assessee claiming exemption under Schedule IV (Sl. No. 13D and 13E) shall be required to furnish prescribed information in Form No. 173A. In simple terms, exemption will not merely depend upon eligibility. The taxpayer will also be required to file the specified reporting form containing detailed investment information. Key Point
- It is a compliance and reporting requirement.
- It does not create a new exemption.
- It does not automatically grant tax benefits to all Government security investors.
What is Form No. 173A?
Form 173A is a new reporting form proposed for taxpayers claiming exemption on Interest earned from Government Securities and Capital gains from Government Securities. Form 173A is titled "Information to be furnished for claiming exemption on interest and capital gains from Government securities." The form collects:
What Information Is Required in Form 173A?
CBDT Form 173A requires detailed information about investors, security holdings and exempt income. The Form No. 173A is divided into
Part A – Basic Information- Taxpayer Information
- Name: Full name of the assessee.
- Country of Residence: Country where the taxpayer is resident for tax purposes.
- Address in Country of Residence: Complete overseas address including Country, Building/Flat Number, Street/Road, ZIP/PIN Code, Locality, District and State
- Permanent Account Number (PAN) : PAN allotted in India.
- Tax Identification Number (TIN): Tax residency identification number of the foreign jurisdiction.
- SEBI Registration Number: SEBI registration number as FPI (Foreign Portfolio Investor), FII (Foreign Institutional Investor), where applicable.
- Tax Year: Tax year for which exemption is claimed.
- Email ID:
- Contact Number: Complete contact details including country code.
Part B – Details of Exempt Income Claimed- Government Security Details
- The form seeks comprehensive details of Government Securities investments.
- Security-wise Reporting: For each Government Security, the following information is required:
- International Securities Identification Number (ISIN): Unique security identification number.
- Type of Government Security: Applicants must classify investments into Treasury Bills, Fixed Rate Bonds, Floating Rate Bonds, State Development Loans (SDLs), Other Government Securities
- Tenor : Duration or maturity period of security.
- Financial Information Required: The form requires disclosure of Value as on 1 April Opening value of Government Securities held at the beginning of the tax year.
- Purchases During the Year : Value of Government Securities acquired during the tax year.
- Sale Consideration : Total consideration received on sale of Government Securities during the year.
- Closing Value as on 31 March : Value of securities held at the end of the tax year.
- Gross Interest Income : Interest accrued or received from Government Securities during the tax year.
- Capital Gains Earned : Capital gains arising from sale or transfer of Government Securities during the year.
Who is Required to File Form 173A?
The structure of Form 173A suggests that the provision primarily targets Foreign Portfolio Investors (FPIs), Foreign Institutional Investors (FIIs), Sovereign Funds, International Financial Institutions, and Overseas Investors investing in Indian Government Securities. who are claiming specific tax exemptions under Schedule IV of the Income-tax Act, 2025.
Important Clarification : Ordinary investors holding Government bonds should not assume that Form 173A is applicable merely because they earn interest from Government securities
Who is Covered by the Proposed Rule 281A and Form 173A?
It is important to understand that the proposed Rule 281A and Form 173A are not applicable to all investors holding Government Securities. The compliance requirement is specifically intended for certain eligible foreign investors claiming exemption under the specified provisions of Schedule IV of the Income-tax Act, 2025.
|
Category of Investor |
Automatic Applicability of Rule 281A & Form 173A |
|
Resident Indian individual investing in Government Bonds |
No |
|
Non-Resident Indian (NRI) investing in Government Securities |
No |
|
Indian Company holding government securities |
No |
|
Foreign Individual Investor |
No |
|
Eligible Foreign Portfolio Investor (FPI) / Foreign Institutional Investor (FII) claiming the specified exemption |
Yes |
|
Bank for International Settlements (BIS) claiming the specified exemption |
Yes |
The proposed reporting requirement is not a general compliance obligation for all investors in government securities. Instead, it is designed for specific foreign investors who seek to avail themselves of the tax exemptions provided under the relevant entries of Schedule IV of the Income-tax Act, 2025.
Merely investing in Indian government securities does not automatically entitle an investor to tax exemption, nor does being a foreign investor automatically make the income exempt from tax. The investor must first satisfy the conditions prescribed for the relevant exemption and, thereafter, furnish the prescribed information in Form 173A to support the exemption claim.
Special Relaxation for BIS : The notification specifically provides that TIN Details and SEBI Registration Number are optional for the Bank for International Settlements (BIS).
Types of Government Securities Covered
The form requires reporting of investments in Treasury Bills (T-Bills), Fixed Rate Bonds, Floating Rate Bonds, State Development Loans (SDLs) and Other Eligible Government Securities
Declaration Requirement
The assessee will be required to certify that:
- Information furnished is true and correct.
- Exemption is claimed in accordance with Schedule IV provisions.
- Information is complete to the best of his knowledge and belief.
Why Has CBDT Introduced This Form?
The objective is to Track exemption claims accurately, Link interest income and capital gains with specific Government securities, verify investment holdings and transactions, Improve transparency and tax compliance and Facilitate verification of exemption claims.
Indian resident investors generally continue to be taxed as per the normal provisions applicable to them. NRIs and foreign investors are not automatically covered merely because they hold Government Securities. The new compliance framework becomes relevant only when an eligible foreign investor claims exemption on Interest income from specified Government Securities; or Capital gains arising from such securities. In such cases, detailed disclosures relating to residency, tax identification number, SEBI registration, ISIN-wise holdings, interest income, and capital gains are required through Form 173A.
Practical Compliance Checklist
Before filing Form 173A:
- Verify eligibility under Schedule IV (13D/13E).
- Identify all relevant Government securities.
- Obtain ISIN-wise investment details.
- Reconcile opening and closing holdings.
- Match purchases and sales with records.
- Verify interest income and capital gains.
- Check PAN, TIN and registration details.
- Complete Form 173A accurately.
- Retain supporting investment records.
- Follow CBDT filing instructions and deadlines.
Does Form 173A Introduce a New Tax?
No. The amendment Does not impose any new tax, Does not provide a blanket exemption and Only mandates furnishing information when claiming specified exemptions. Eligibility for exemption will continue to depend upon the provisions of the Income-tax Act, 2025.
Compliance Impact
The amendment will increase transparency regarding tax-exempt investments in Government Securities. Key implications include:
- Additional compliance reporting requirement.
- Security-wise disclosure of exempt investments.
- Detailed tracking of interest income and capital gains claimed as exempt.
- Better audit trail for tax authorities.
- Reduced disputes relating to exemption eligibility.
- Enhanced reporting for foreign investors in Indian Government Securities.
Key Takeaways
Rule 281A and Form 173A introduce a structured reporting framework for taxpayers claiming certain tax exemptions on interest income and capital gains from Government securities.
- CBDT has proposed insertion of Rule 281A under the Income-tax Rules 2026.
- New Form 173A has been introduced to claim exemption on interest income and capital gains from Government Securities.
- The form requires taxpayer details, residency information, PAN, TIN, SEBI registration details and security-wise reporting of investments.
- Detailed disclosure of ISIN, purchases, sales, interest income and capital gains will be mandatory.
- The amendment mainly impacts FPIs, FIIs and other foreign investors investing in Indian Government Securities.
- The objective is to strengthen transparency and ensure proper verification of exemption claims under Schedule IV of the Income-tax Act, 2025.
Conclusion
- Rule 281A and Form 173A are targeted disclosure provisions for eligible foreign institutional investors and specified international entities claiming tax exemption on income from Indian Government Securities. They are not intended to apply universally to all bondholders or all foreign investors.
- Eligible taxpayers must provide detailed security-wise information, including holdings, transactions, interest income, and capital gains. The requirement improves transparency and supports verification of exemption claims while not altering the underlying eligibility conditions for tax exemptions.
- Before claiming any exemption, taxpayers must verify their eligibility under Schedule IV and comply with the prescribed reporting requirements.
- In essence, CBDT is moving toward a disclosure-based exemption regime, where eligible taxpayers can continue claiming exemption on Government Securities income, but only after furnishing comprehensive investment and income details through the newly prescribed Form 173A