Table of Contents
Joint Assets: Think Beyond Tax Savings, Plan for Protection and Succession
Joint ownership of property, bank accounts, and investments is often promoted as an effective tax-planning strategy. While joint assets can certainly provide income-tax benefits and optimize deductions, viewing them solely through a tax lens can create significant legal, financial, and succession-related risks.
True financial planning goes beyond reducing taxes. It focuses on ensuring uninterrupted access to assets, protecting family wealth, avoiding disputes among heirs, and securing the financial future of loved ones.
Why Joint Ownership Matters
- For married couples and family members, joint ownership serves multiple purposes beyond tax savings. It can help ensure that assets remain accessible and manageable during unforeseen circumstances such as death, illness, incapacity, or prolonged absence of one owner.
- A well-structured joint ownership arrangement can provide Easier access to assets for the surviving spouse, Better continuity in financial management, Clear ownership rights and responsibilities, Smoother transfer of wealth to the next generation and Reduced risk of inheritance disputes.
- A comprehensive joint ownership strategy should answer four key questions:
- Who actually funded the purchase?
- What percentage belongs to each co-owner?
- Who can access the asset during emergencies?
- Who ultimately inherits the asset after the owner's death?
- Without clarity on these aspects, tax benefits today may lead to disputes tomorrow
Key Areas That Require Careful Attention
-
Plan for Continuity, Not Just Tax Efficiency :
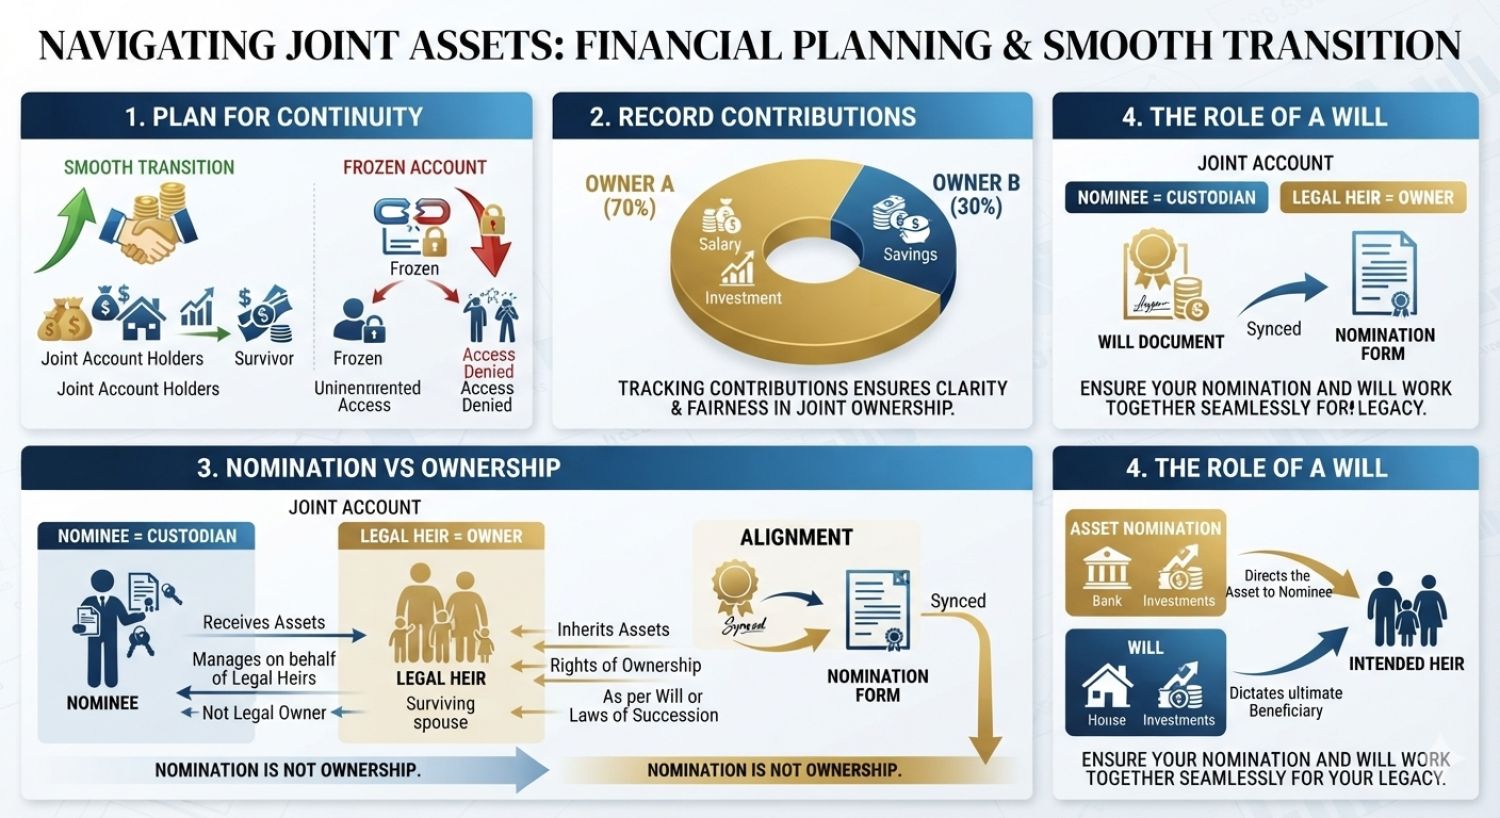
- One of the biggest advantages of joint ownership is continuity. If one co-owner becomes incapacitated or passes away, the surviving owner may find it easier to operate bank accounts, manage investments, or deal with jointly held property. However, this benefit is maximized only when ownership structures, nominations, and succession plans are properly documented.
- Without proper planning, family members may face Frozen bank accounts, Delayed access to investments, Probate and succession complications and Legal disputes among heirs. Joint ownership should therefore be viewed as a continuity-planning tool rather than merely a tax-saving mechanism.
-
Clearly Record Contributions and Ownership Shares
- Whenever property, securities, or investments are purchased jointly, each person's financial contribution should be clearly documented. Maintain records of Initial capital contribution, Down-payment made by each co-owner, EMI payments towards housing loans, Renovation or improvement expenses and Investment contributions into mutual funds or financial assets.
- For example, if a husband contributes 70% of the purchase price of a property and the spouse contributes 30%, ownership records and supporting documents should ideally reflect that position.
- Proper documentation Supports tax claims, avoids income attribution disputes, Simplifies future capital gains calculations, Helps resolve ownership disagreements.
-
Keep Nominations Updated
- Many individuals add a nominee once and forget about it for years. Nominations should be periodically reviewed for Bank accounts, Fixed deposits, Mutual funds, Demat accounts, Insurance policies, EPF and NPS accounts and Bonds and securities. Life events such as marriage, childbirth, divorce, death of a nominee, or family restructuring should trigger an immediate review of nomination records.
- Outdated nominations can create complications during claim settlements and inheritance proceedings.
-
Understand the Difference Between a Nominee and an Owner:
- This is one of the most misunderstood areas of financial planning. A nominee is generally not the ultimate owner of the asset. In most situations, the nominee merely acts as a custodian or trustee who receives the asset on behalf of the legal heirs.
Nominee ≠ Legal Owner
- For most financial assets The nominee obtains possession. The legal heirs obtain beneficial ownership. And Succession laws and the Will determine the final distribution. Therefore, appointing a nominee alone does not eliminate succession-related issues.
-
Have a Proper Will :
A nomination cannot replace a well-drafted Will. Every family should maintain a clear Will specifying Who will inherit specific assets., Distribution percentages among beneficiaries, Guardianship provisions where applicable. And Successor arrangements for jointly owned assets.
The Will and nomination records should always be aligned to avoid conflicts. For example If a mutual fund nomination names one person, But the Will leaves the investment to another person, the family may face avoidable litigation and delays.
Hidden Risks of Joint Ownership
- Documentation Risk : Failure to maintain contribution records can lead to Tax scrutiny, Ownership disputes and Difficulties during succession
- Succession Risk : Absence of a Will may result in Legal heir disputes, Court proceedings, Delayed transfer of assets
- Access Risk : Improper structuring may lead to Frozen bank accounts, Restricted access to funds and Delays in emergency financial requirements
- Liability Risk : Joint owners generally share responsibility for Housing loans, Tax liabilities, Property-related obligations and Charges or encumbrances on the asset
- A default by one co-owner can impact the entire holding arrangement.
Essential Steps for Effective Joint Asset Planning
- Align Ownership with Actual Contributions : Ensure ownership percentages correspond to actual financial contributions.
- Maintain Complete Documentation : Preserve Bank statements, Loan repayment records, Sale deeds, Investment statements and Payment trails
- Review Nominations Regularly : Update nominee details after every major life event.
- Prepare a Comprehensive Will : Clearly define inheritance rights and succession arrangements.
- Create an Emergency Access Plan : Ensure family members know Where important documents are stored, How to access critical financial information and Whom to contact in emergencies
Practical Takeaway
Joint ownership should be planned from three perspectives:
- Tax Efficiency : Maximize deductions and optimize taxation.
- Asset Protection : Ensure ownership records, contributions, and liabilities are clearly defined.
- Succession Planning : Keep nominations updated and maintain a legally valid Will to facilitate smooth inheritance.
Conclusion
- Joint ownership of property can deliver valuable tax benefits, but tax planning alone is not enough. A successful joint ownership structure should combine tax efficiency, ownership clarity, continuity of access, and inheritance planning. Essential Steps for Effective Joint Asset Planning
- Align ownership shares with actual financial contributions.
- Maintain complete funding and payment records.
- Update nominations periodically.
- Draft and regularly review a legally valid Will.
- Ensure nominations and inheritance instructions are consistent.
- Create an emergency access and succession plan for family members.
- Financial planning is not merely about saving income tax. It is equally about protecting family wealth, ensuring uninterrupted access to assets, minimizing inheritance disputes, and securing the future of loved ones.
- Remember:
- Joint ownership can provide tax benefits today, but proper documentation, updated nominations, and a well-drafted Will are what truly protect your family's financial future tomorrow.
- Saving tax is only one part of financial planning. Protecting assets, avoiding family disputes, ensuring smooth succession, and securing your spouse's financial future are equally important objectives when holding property jointly.