GST Filling
GSTN Makes emSigner v3.3 Mandatory for New DSC Tokens from 21 09.2026
RJA 02 Oct, 2026
GSTN Makes emSigner v3.3 Mandatory for New DSC Tokens from 21 September 2026 GSTN has released an advisory requiring users with newly issued DSC USB tokens (dongles) issued on or after 21 September 2026 to upgrade to emSigner version 3.3. The change is intended to ensure compatibility with new-generation DSC tokens. Key Points—GSTN ...

IBC
IBBI Further Extends Deadline for Filing PGIRP Forms
RJA 02 Oct, 2026
IBBI Further Extends Deadline for Filing PGIRP Forms The Insolvency and Bankruptcy Board of India (IBBI) has issued Circular No. IBBI/II/108/2026 dated 24 September 2026, granting a further extension for filing electronic Forms PGIRP-1 to PGIRP-6 relating to insolvency resolution processes of Personal Guarantors to Corporate Debtors. Key Highlights of IBBI ...

IBC
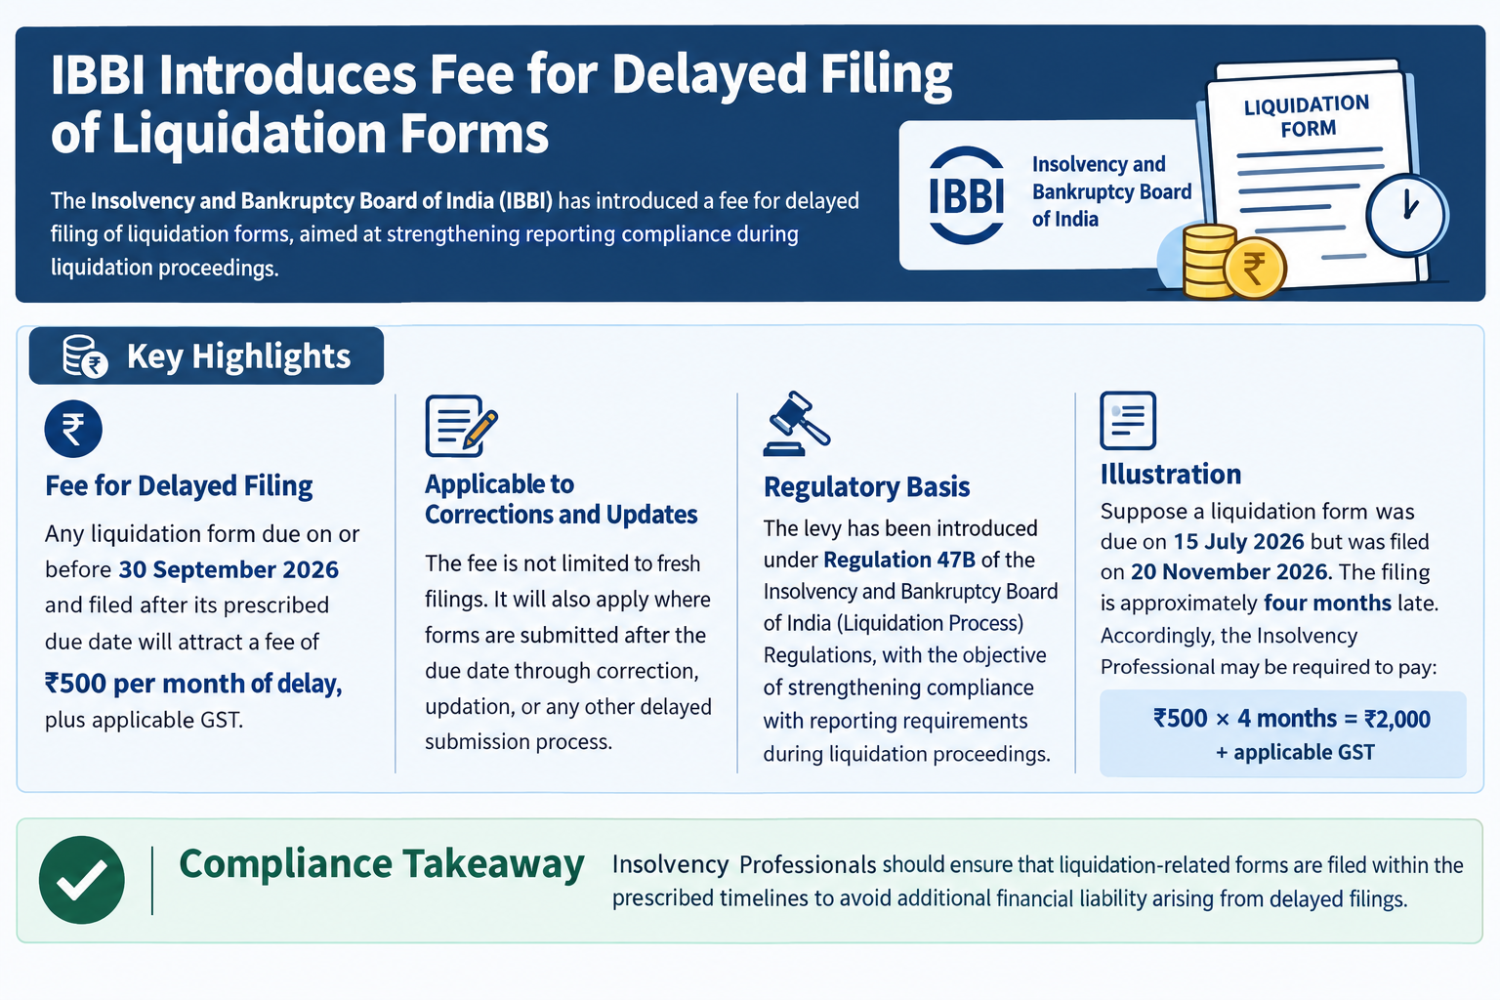
IBBI Introduces Fee for Delayed Filing of Liquidation Forms
RJA 02 Oct, 2026
IBBI Introduces Fee for Delayed Filing of Liquidation Forms The Insolvency and Bankruptcy Board of India (IBBI) has issued Circular No. IBBI/LIQ/107/2026 dated 24 September 2026, notifying the commencement of fees for delayed filing of forms under Regulation 47B of the IBBI (Liquidation Process) Regulations, 2016. The circular applies to all Registered ...

IBC
IBBI Fifth Amendment 2026: Liquidator Can Now Modify the List of Stakeholders
RJA 02 Oct, 2026
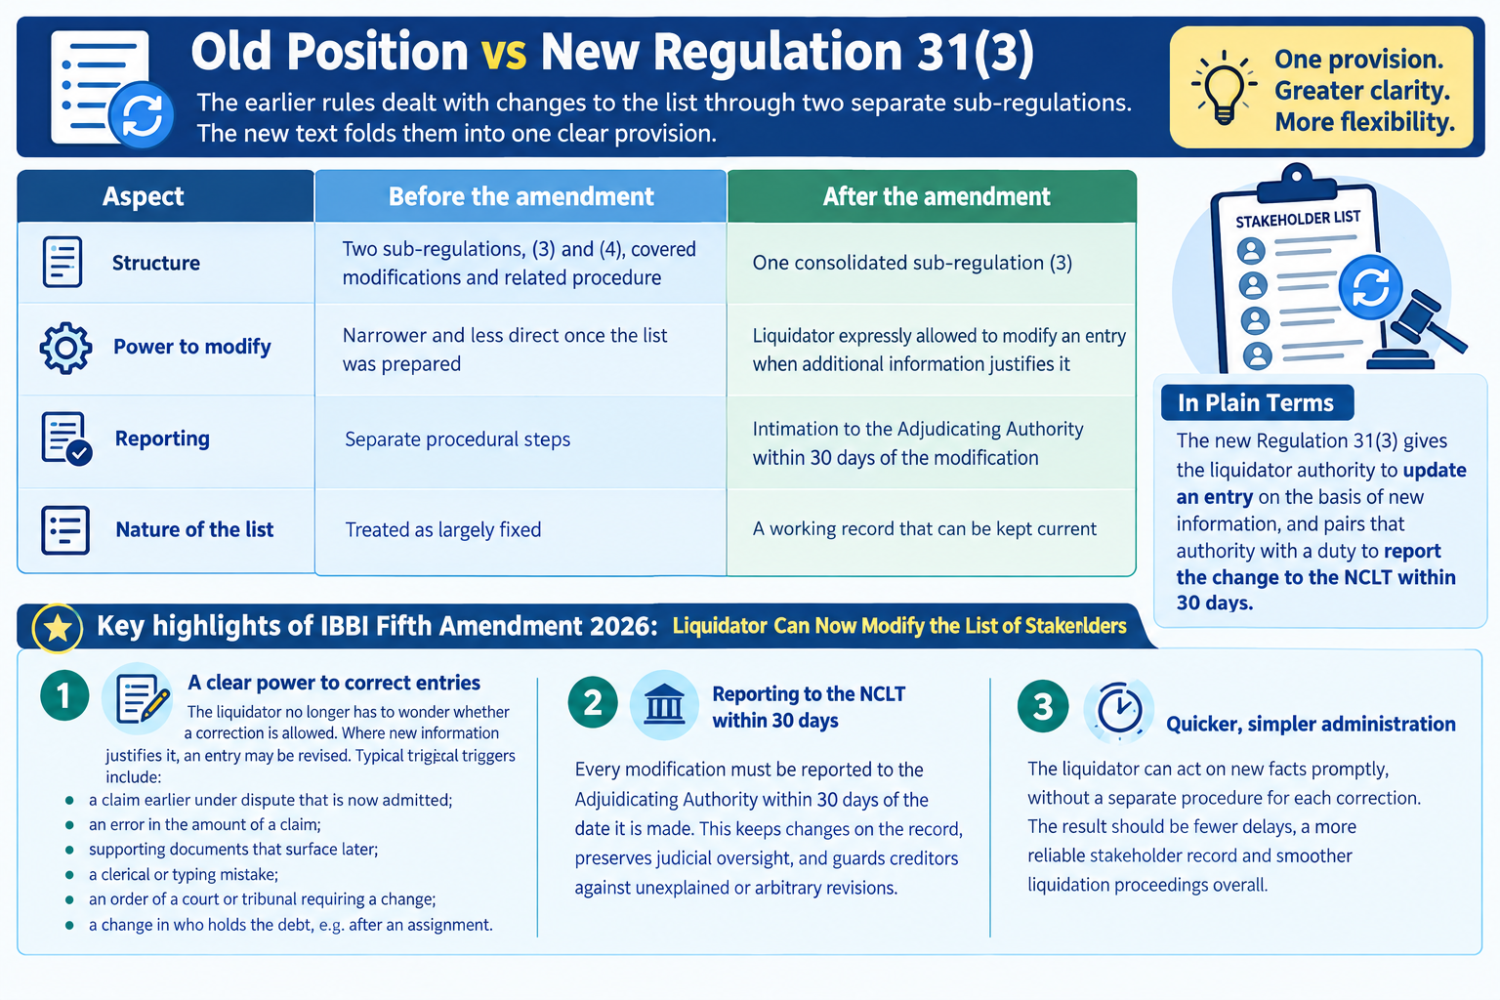
Overview of IBBI Fifth Amendment 2026: Liquidator Can Now Modify the List of Stakeholders A liquidator can now correct any entry in the List of Stakeholders when fresh information supports it, provided the Adjudicating Authority is told within 30 days. This is the core of the IBBI (Liquidation Process) (Fifth Amendment) ...

IBC
Cessation of Interim Moratorium for PG's to Corporate Debtors
RJA 02 Oct, 2026
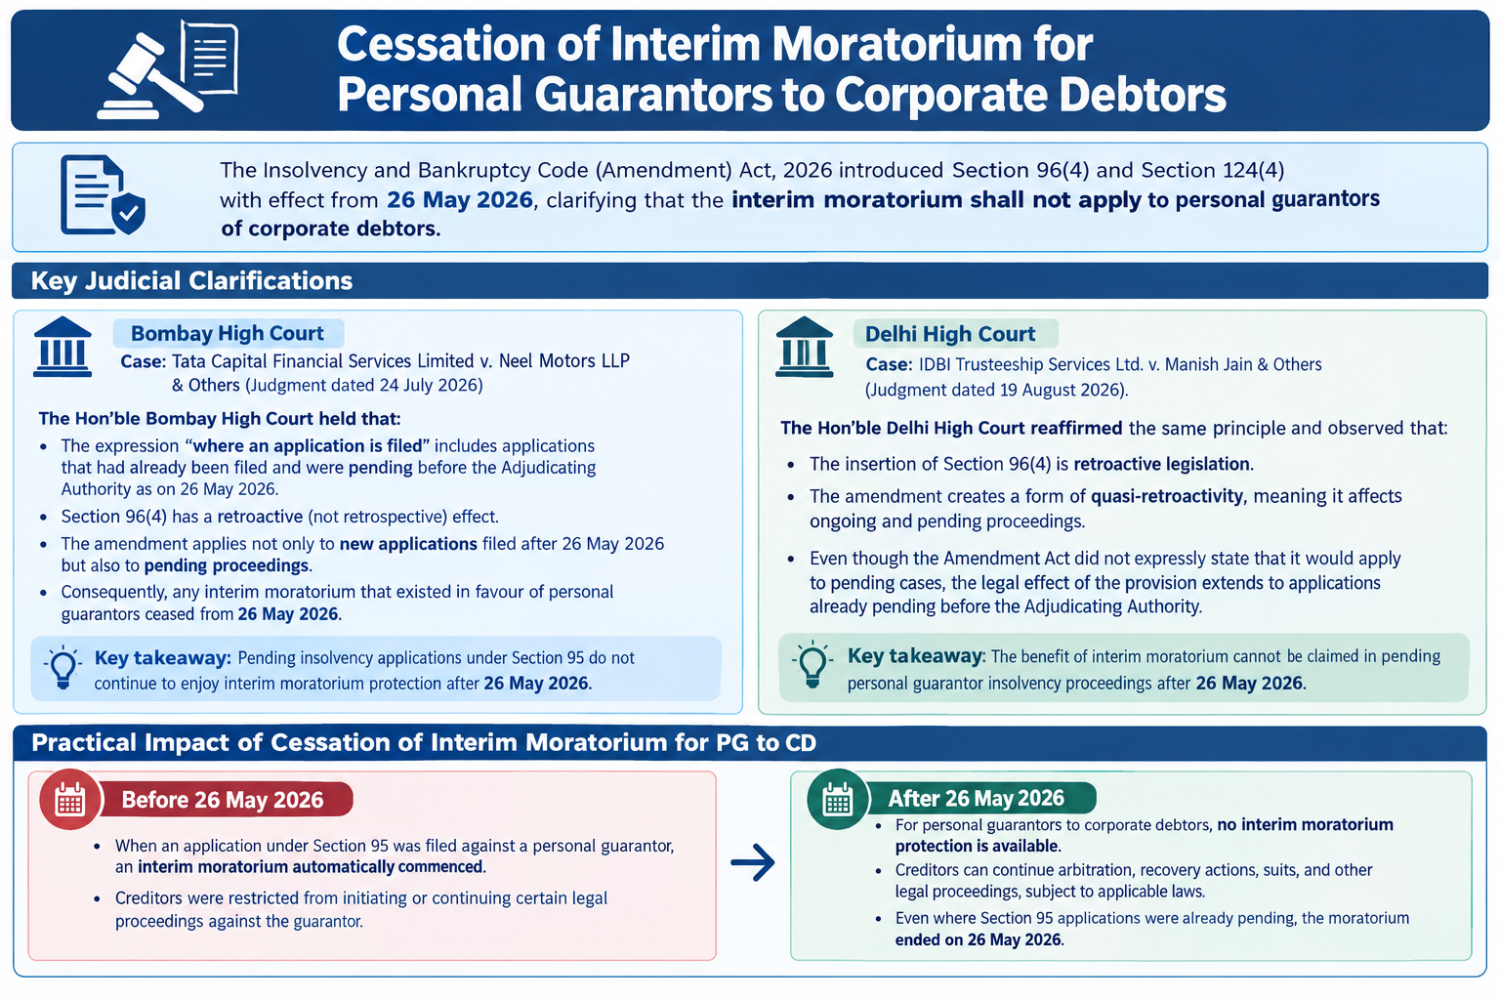
Cessation of Interim Moratorium for Personal Guarantors to Corporate Debtors The Insolvency and Bankruptcy Code (Amendment) Act, 2026 introduced Section 96(4) and Section 124(4) with effect from 26 May 2026, clarifying that the interim moratorium shall not apply to personal guarantors of corporate debtors. Following are Key Judicial Clarifications Bombay High Court : Case: Tata ...

IBC
Due Diligence by Insolvency Professionals to Identify and Prevent Misuse of the IBC Framework
RJA 02 Oct, 2026
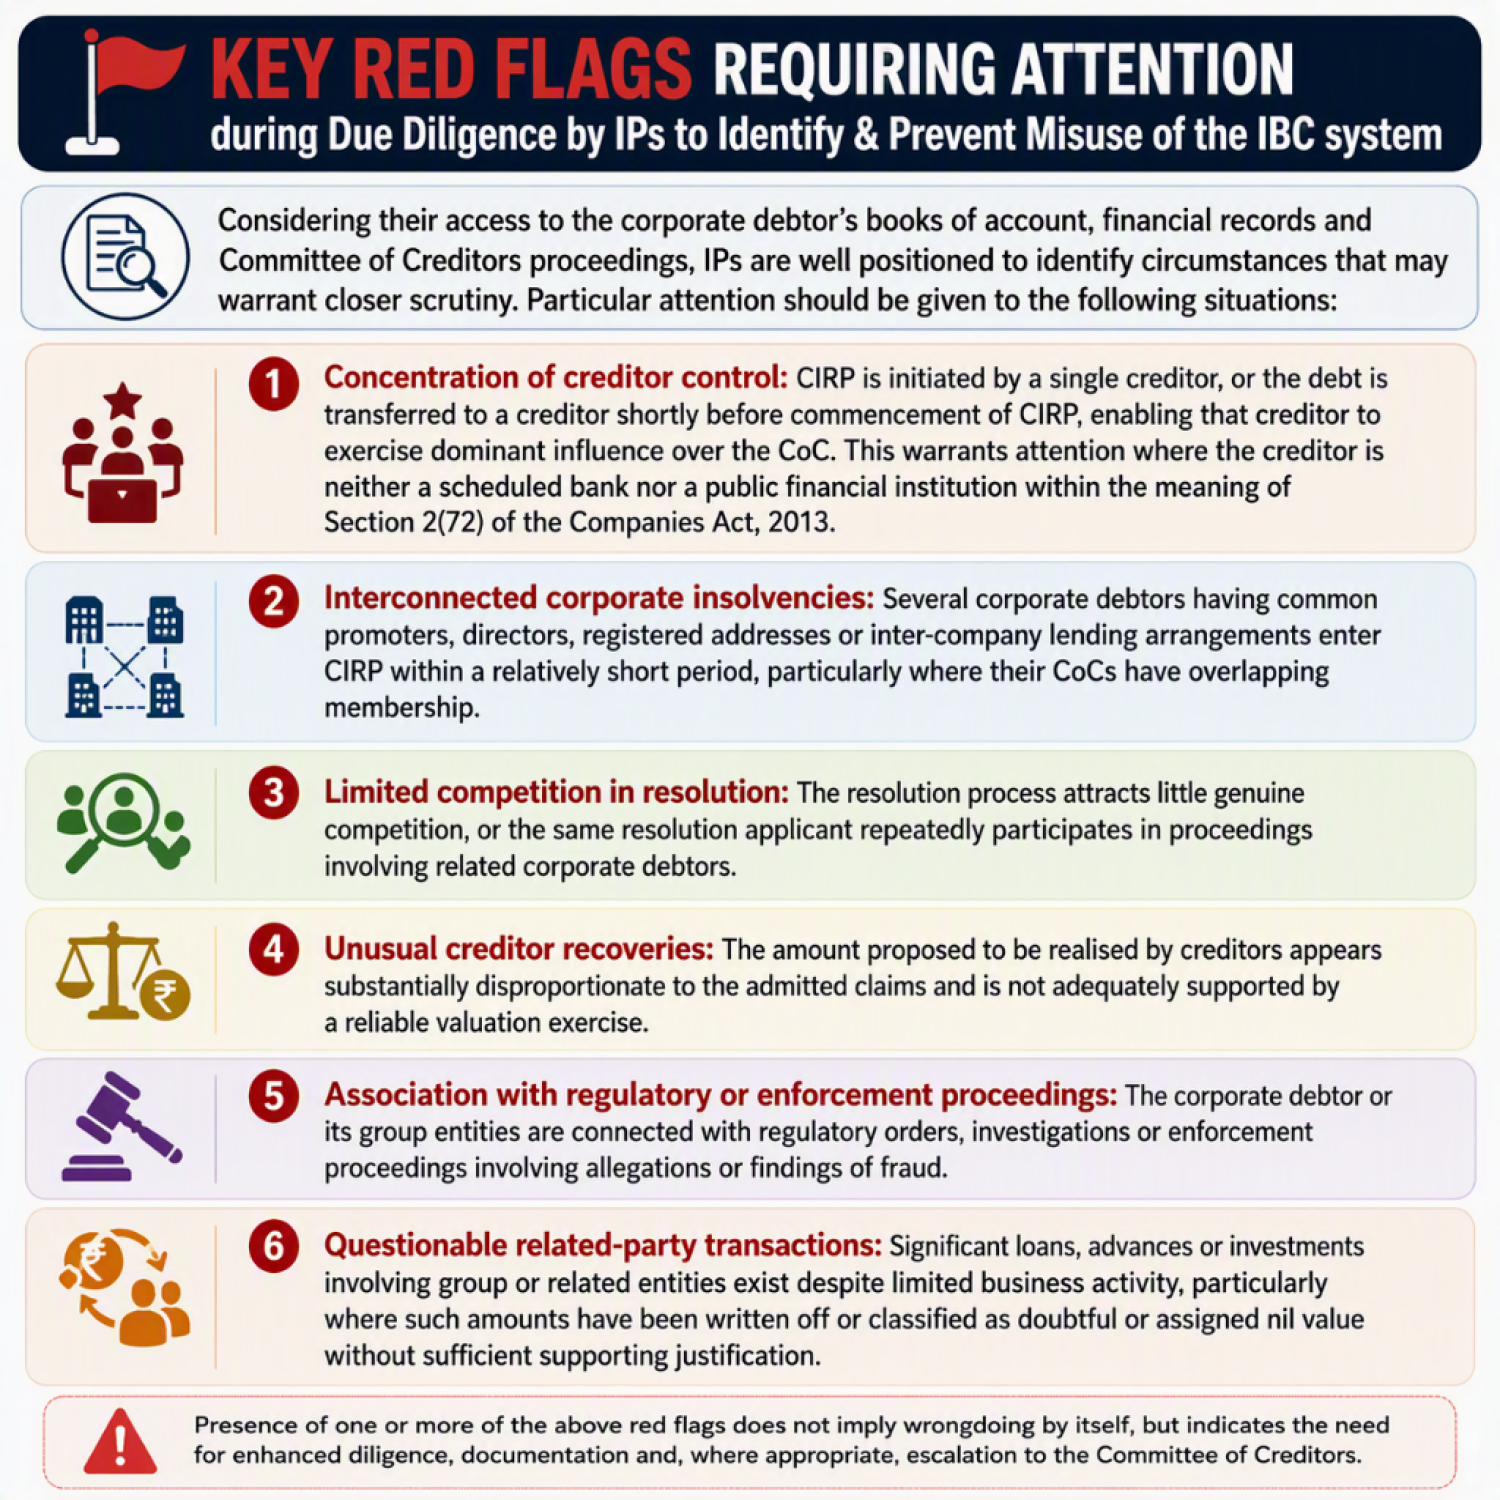
Due Diligence by Insolvency Professionals to Identify and Prevent Misuse of the IBC Framework The Insolvency and Bankruptcy Board of India (IBBI), based on information received from law enforcement and regulatory authorities, has highlighted concerns regarding the potential misuse of the Insolvency and Bankruptcy Code, 2016 (IBC). In certain cases, insolvency ...

IBC
IBBI Valuation Guidelines under IBC 2026: Complete Guide
RJA 02 Oct, 2026
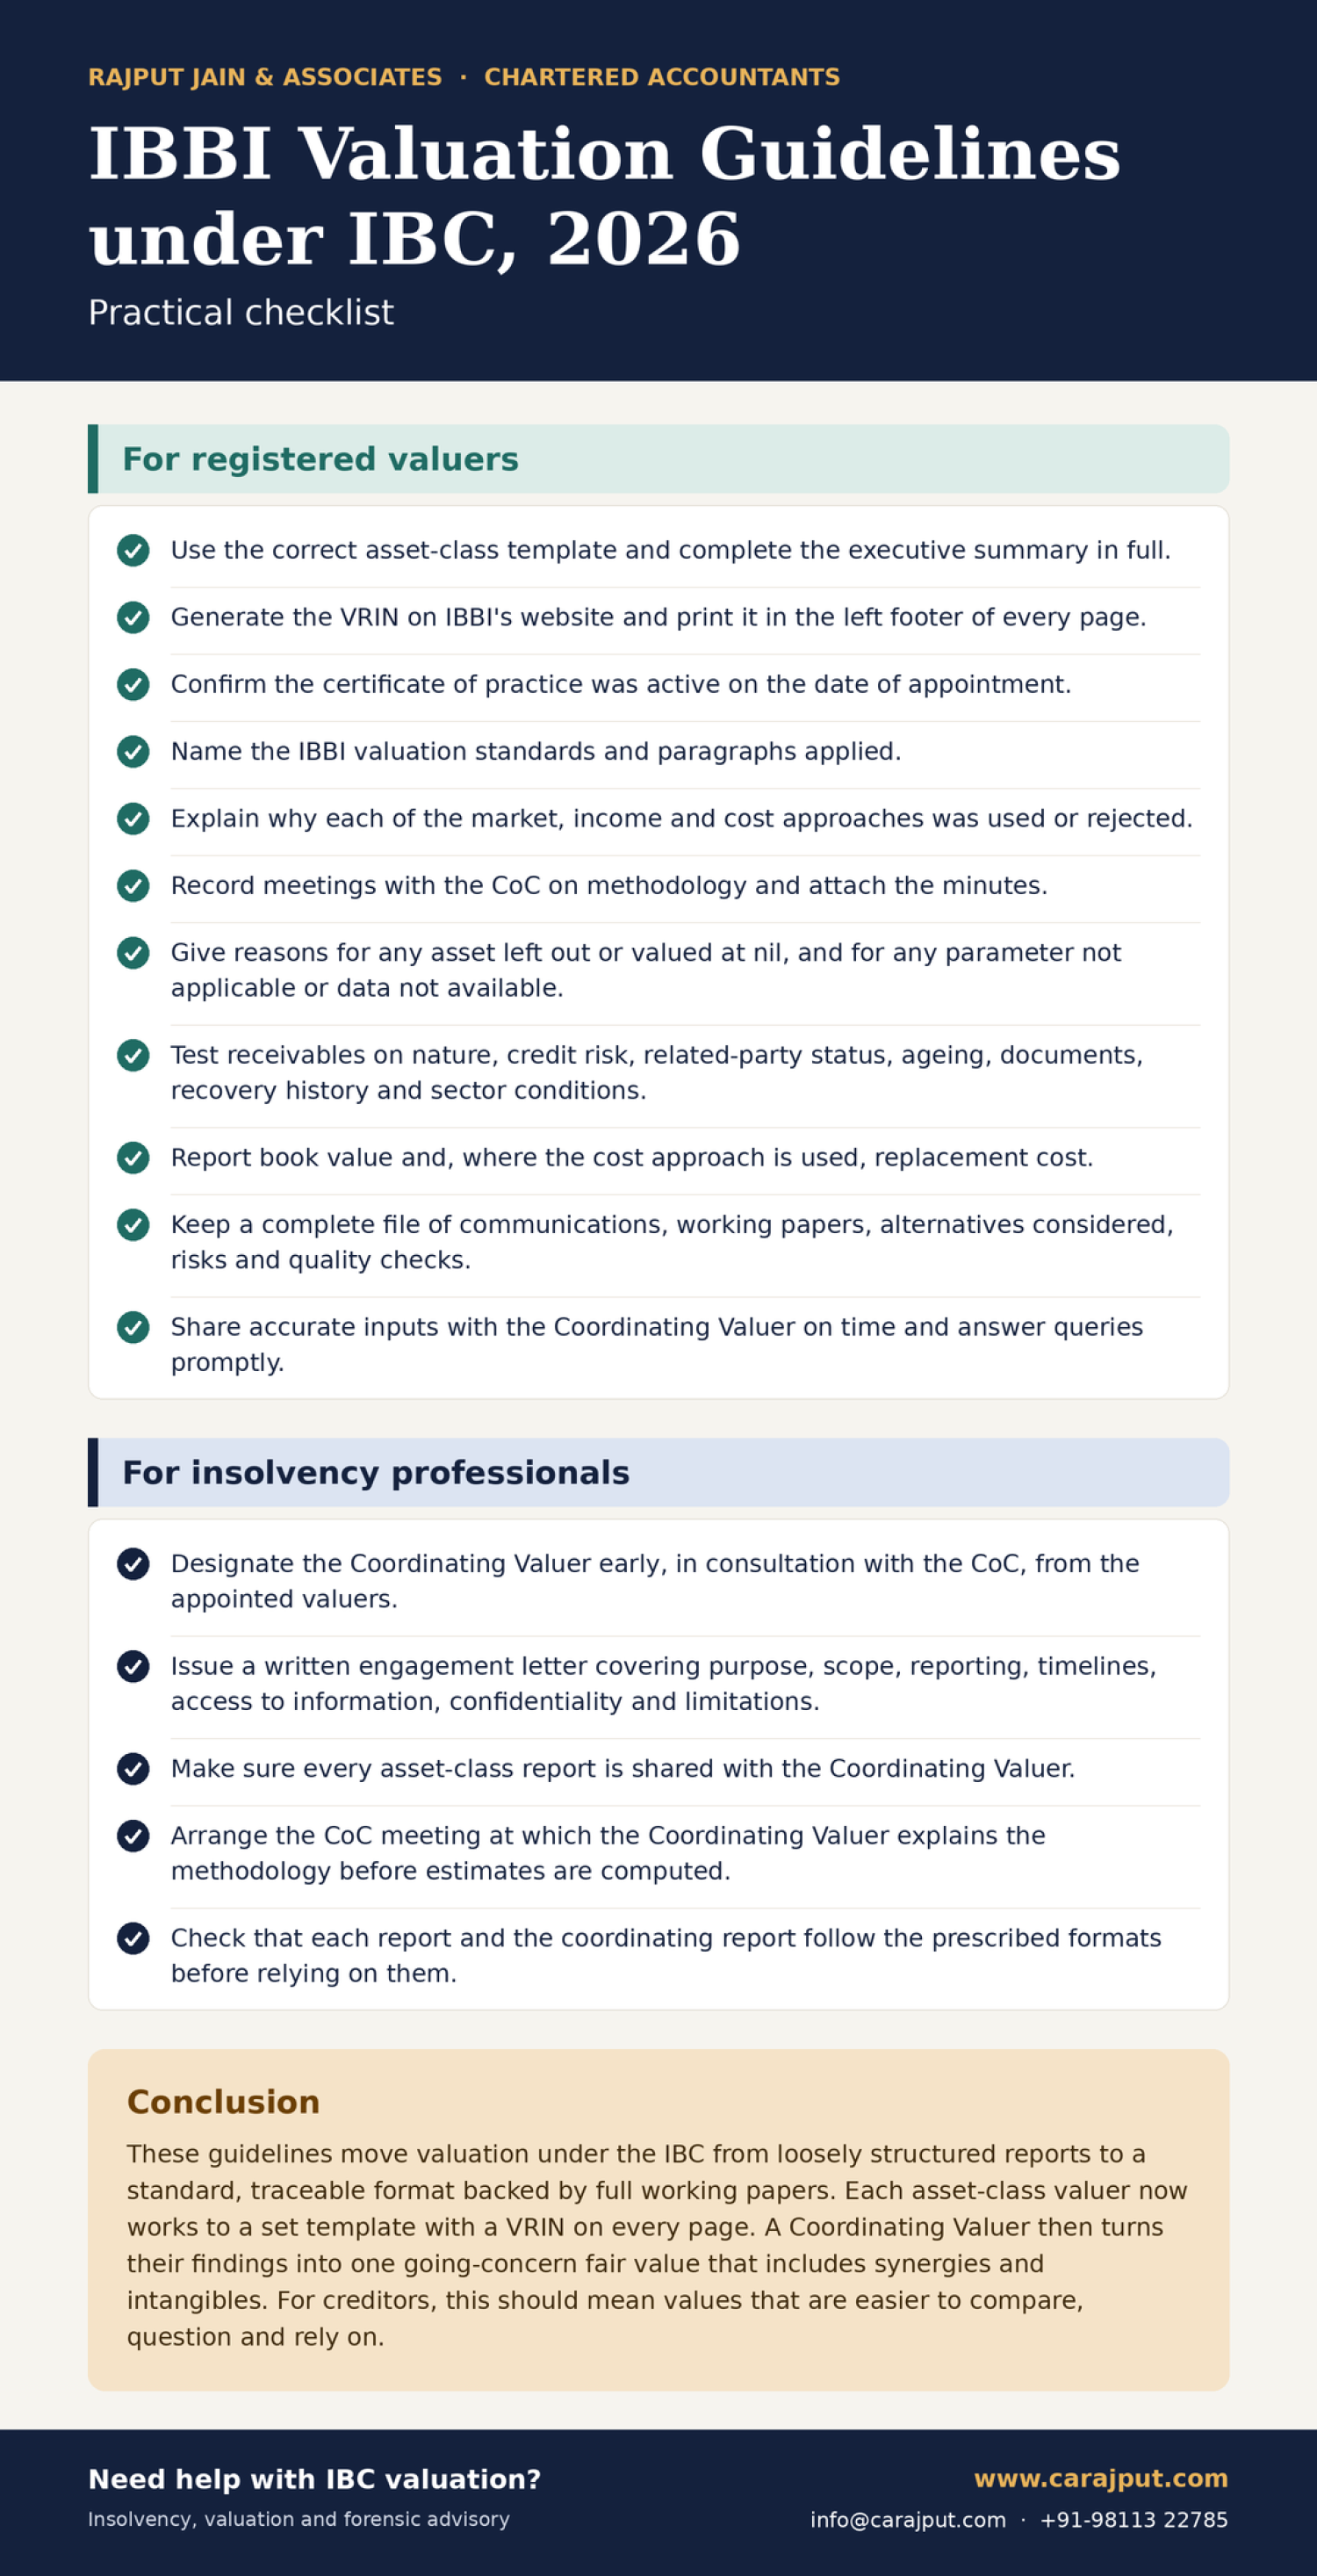
IBBI Valuation Guidelines under IBC, 2026: Complete Explained Guide From 15 June 2026, every registered valuer working under the Insolvency and Bankruptcy Code, 2016 must prepare reports and keep working papers in the format IBBI has now prescribed. The rules come from IBBI Circular No. IBBI/RV/103/2026, which also creates a Coordinating Valuer to ...

AUDIT
44AB(a), (b), (c), (d)/(e): Which Tax Audit (FY 2025-26) Clause Applies?
RJA 01 Oct, 2026
44AB(a), (b), (c), (d) or (e): Which Tax Audit Clause Applies? (FY 2025-26 / AY 2026-27) Selecting the correct clause under Section 44AB is the first step in a tax audit. The clause reported in Clause 8 of Form 3CD reflects why the audit applies, while the choice between Form 3CA ...

COMPANY LAW
Compliance Planning Checklist for October 2026
RJA 01 Oct, 2026
October 2026 Compliance Calendar: Key Tax, GST, TDS, ROC & Payroll Due Dates October 2026 is one of the most critical compliance months for businesses, professionals, companies, LLPs, and tax practitioners. With revised tax audit timelines, quarterly TDS/TCS filings, GST returns, ROC compliances, and payroll obligations falling in the same month, ...

INCOME TAX
Salary Tax Planning for Tax Year 2026-27: New Regime vs Old Regime
RJA 30 Sep, 2026
Salary Tax Planning for Tax Year 2026-27: New Regime vs Old Regime under the Income-tax Act, 2025 From "FY/AY" to "Tax Year": what has changed The Income-tax Act, 2025 came into force on 1 April 2026, replacing the Income-tax Act, 1961. One of its most visible changes is terminology. The ...

NRI
TDS on Buying Property from an NRI: TAN Requirement Removed From 1 Oct 2026
RJA 27 Sep, 2026
TDS on Buying Property from an NRI: TAN Requirement Removed From 1 October 2026 Starting 1 October 2026, a resident individual or HUF who purchases immovable property from a non-resident will not have to obtain a TAN to deduct and deposit TDS. The CBDT has notified the Income-tax (Fifth Amendment) Rules, 2026 (Notification No. 121/2026, G....

Chartered Accountants
ICAI's 60 Tax Audit Limit Now Enforced via UDIN: What Every CA Must Know
RJA 24 Sep, 2026
ICAI's 60 Tax Audit Limit Now Enforced Through UDIN: What Every Chartered Accountant Must Know Introduction For many years, the ceiling on the number of tax audits that a chartered accountant could undertake functioned largely as a matter of professional self-regulation. That position is now set to change. The Institute ...

Chartered Accountants
Why Every CA Firm Needs a Robust Audit Manual
RJA 22 Sep, 2026
Why Every CA Firm Needs a Robust Audit Manual In today's evolving regulatory environment, maintaining audit quality is not merely a best practice but a professional necessity. An Audit Manual serves as the foundation of a Chartered Accountant firm's quality control framework and is essential for firms undertaking ...

Chartered Accountants
DPDP Act Explained for Chartered Accountants:
RJA 14 Sep, 2026
DPDP Act Explained for Chartered Accountants: Here we explain how the Digital Personal Data Protection (DPDP) Act, 2023, applies specifically to Chartered Accountants (CAs), CA Firms, Tax Consultants, Auditors, and Professional Service Firms. The main message is that a CA firm can act either as a data fiduciary or a Data ...

AUDIT
Form 3CD -Clause 12: Presumptive Income & Deemed Profit Provisions
RJA 14 Sep, 2026
Form 3CD - Clause 12: Presumptive Income and Deemed Profit Provisions Clause 12 of Form 3CD requires the Tax Auditor to report whether the assessee has opted for any special presumptive taxation provisions under the Income-tax Act, where income is computed on a prescribed basis rather than on actual books of account. ...

AUDIT
Revision of Tax Audit Report under Rule 6G & Penalty : Explanation
RJA 13 Sep, 2026
Revision of Tax Audit Report under Rule 6G – Detailed Explanation The Income Tax Act permits revision of a tax audit report in certain specified situations. Earlier, there was no specific mechanism to revise a tax audit report after filing. However, pursuant to Notification No. 28/2021 dated 01.04.2021, a taxpayer can furnish ...

AUDIT
Form 3CA / 3CB Qualifications – Explanation for Tax Auditors
RJA 13 Sep, 2026
Form 3CA / 3CB Qualifications – Detailed Explanation for Tax Auditors A qualification in Form 3CA or Form 3CB is not a mere disclosure. It is a formal statement by the tax auditor highlighting material deficiencies, limitations, discrepancies, or lack of evidence that affect the auditor's ability to express an ...

FCRA
FCRA 2010 (Incorporating Amendments up to June 2026)
RJA 12 Sep, 2026
FCRA 2010 (Incorporating Amendments up to June 2026) Comprehensive analysis of the Foreign Contribution (Regulation) Act, 2010 (FCRA), including the major amendments introduced through the 2024, 2025, and 2026 Rules. It also distinguishes between provisions that are currently in force and those merely proposed under the pending FCRA Amendment Bill, 2026. 1. Purpose of FCRA: The objective of ...

NGO
Taxation of Unregistered NPOs: Can NGO Be Taxed on Net Income/Gross Receipts?
RJA 12 Sep, 2026
Taxation of Unregistered NPOs: Can Charitable Trusts Be Taxed on Net Income Instead of Gross Receipts? Introduction The taxation of charitable and religious organizations has undergone significant changes with the transition from the Income-tax Act, 1961 to the Income-tax Act, 2025. While registered charitable institutions continue to enjoy the benefits of exemption ...

Chartered Accountants
ICAI UDIN:Understanding of 60 Tax Audit Limit & Field-Level Validation
RJA 12 Sep, 2026
ICAI UDIN : Understanding of 60 Tax Audit Limit & Field-Level Validation The UDIN Directorate of ICAI has introduced field-level validation on the UDIN portal for tax audit assignments under Section 44AB of the Income Tax Act. This means that while generating a UDIN for a tax audit report, members will not ...

INCOME TAX
Comparative penalty provisions under the ITA 1961 vs ITA 2025.
RJA 05 Sep, 2026
Major penalty provisions Income Tax Act, 2025 vs. Income Tax Act, 1961 The Income Tax Act, 2025, is largely a restructuring and renumbering exercise, with most penalty provisions continuing without major changes. Most penalty provisions are renumbered rather than substantially amended. Section 271AAC (unexplained income penalty) has been omitted. Crypto-asset reporting penalties were ...

INCOME TAX
Residential Status & DTAA Framework: A Comprehensive Guide
RJA 04 Sep, 2026
Residential Status & DTAA Framework: A Comprehensive Guide Under this blogs, we are going to discuss the residential status of individuals and the residential status of entities. We will explain in Place of Effective Management (POEM) Residential Status & DTAA Framework With increasing globalization, individuals are working across ...

Income tax return
Taxation of Exchange Traded Funds (ETFs) in India
RJA 30 Aug, 2026
Taxation of Exchange Traded Funds (ETFs) in India The tax treatment of Exchange Traded Funds (ETFs) depends on the underlying asset (equity, gold, silver, debt, etc.) and the holding period. The classification determines whether the gain is taxed as a Short-Term Capital Gain (STCG) or a **Long-Term Capital Gain (LTCG).** ...

Chartered Accountants
ICAI Expands Bulk UDIN Facility for CA's: Key Features & Process
RJA 30 Aug, 2026
ICAI Expands Bulk UDIN Facility to Tax Audit and Audit & Assurance Functions In a major step towards simplifying compliance and improving efficiency for chartered accountants, the Institute of Chartered Accountants of India (ICAI) has extended the Bulk UDIN Generation Facility to tax audit and audit & assurance functions. Previously, ...