Is Tax audit due date Extended ?
Page Contents

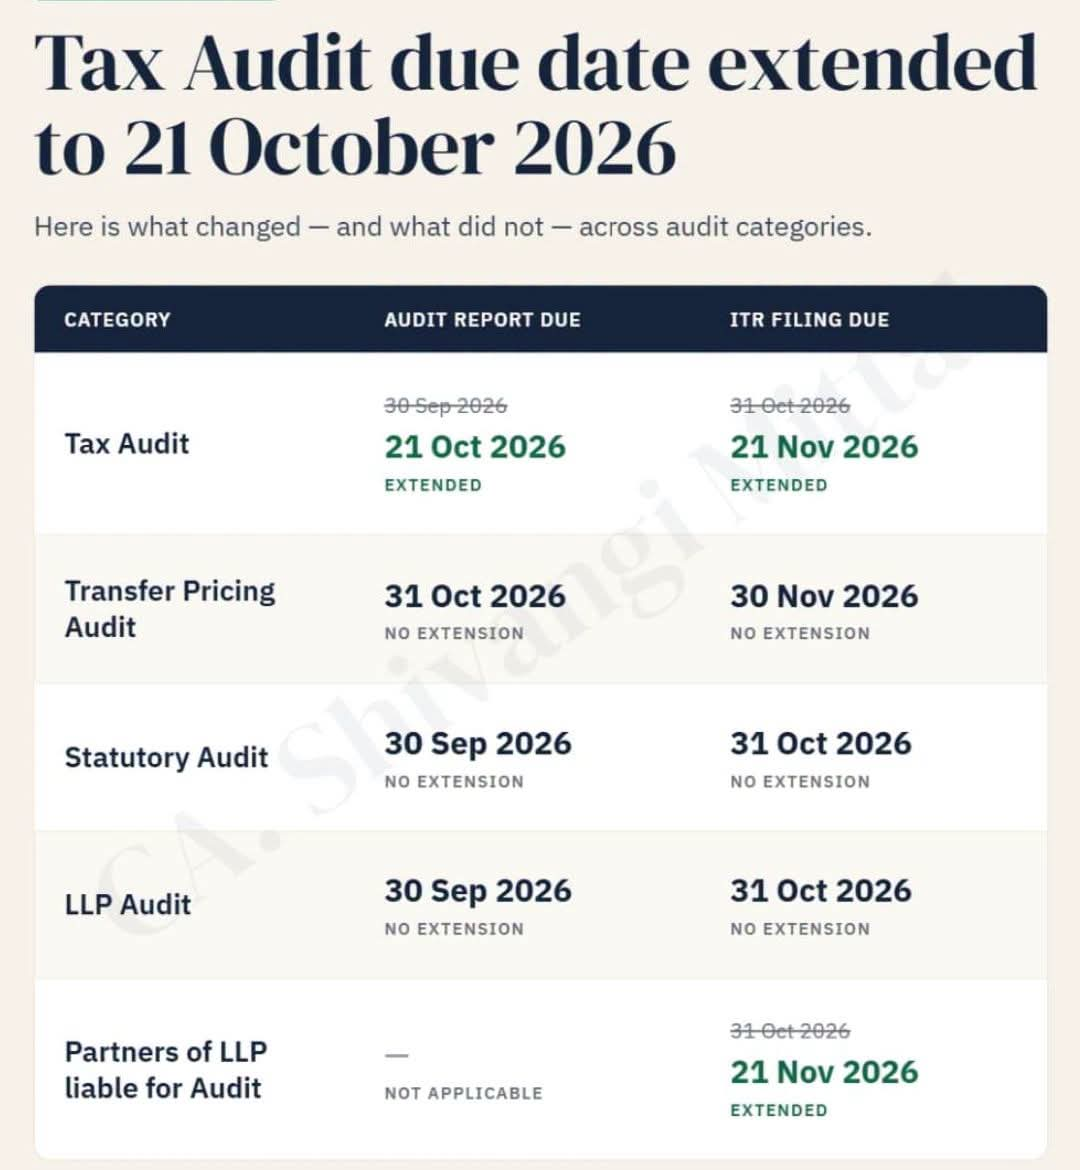
Tax audit due date has been extended till 21 oct 2026
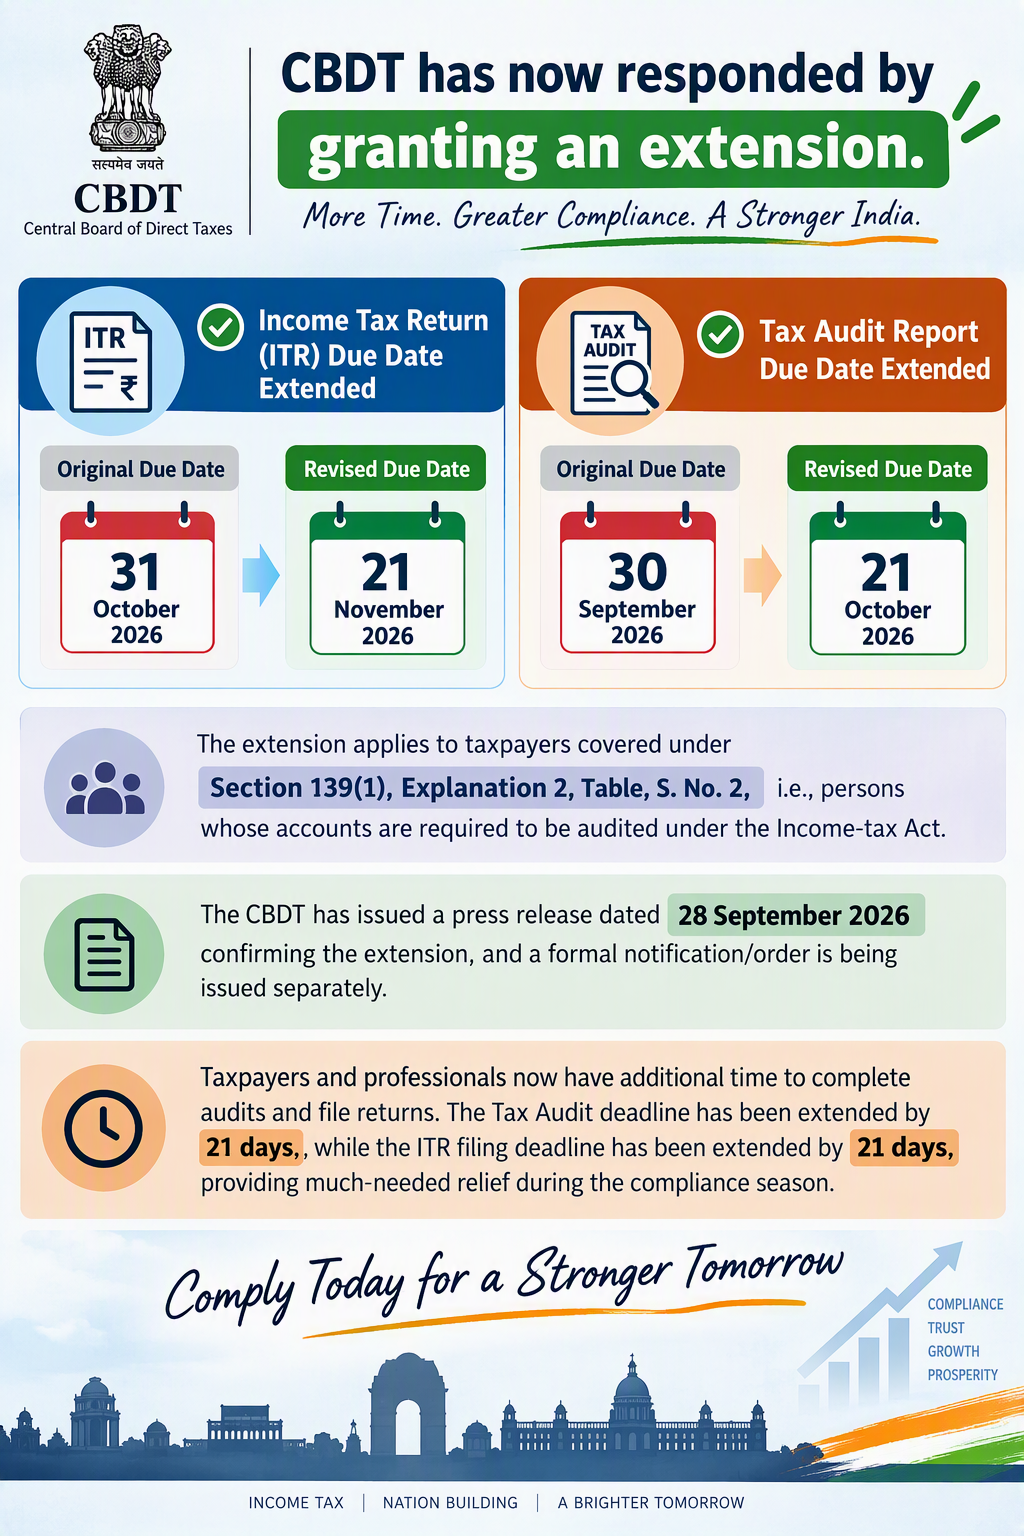
- The Income Tax Department extended the deadline for the Tax Audit Report for AY 2025–26 from 30 September to 21 October 2026 at the last minute.
- Main cause of the prolongation was today’s total downtime of the Income Tax Portal. To upload a single audit report would take hours.
“Due Date” for filing various audit reports is extended by the CBDT for the AY 2025–26 under the Income-tax Act of 1961’s
- The CBDT has decided to extend the due date for filing various reports of audit for the AY 2025-26, which was the 30th Sept, 2026 to the 21th Oct, 2026 in the case of certain category of assessees for whom the due date was 30.09.2026,
- In consideration of difficulties faced by the taxpayers and other stakeholders in filing the various reports of audit for the AY 2025-26
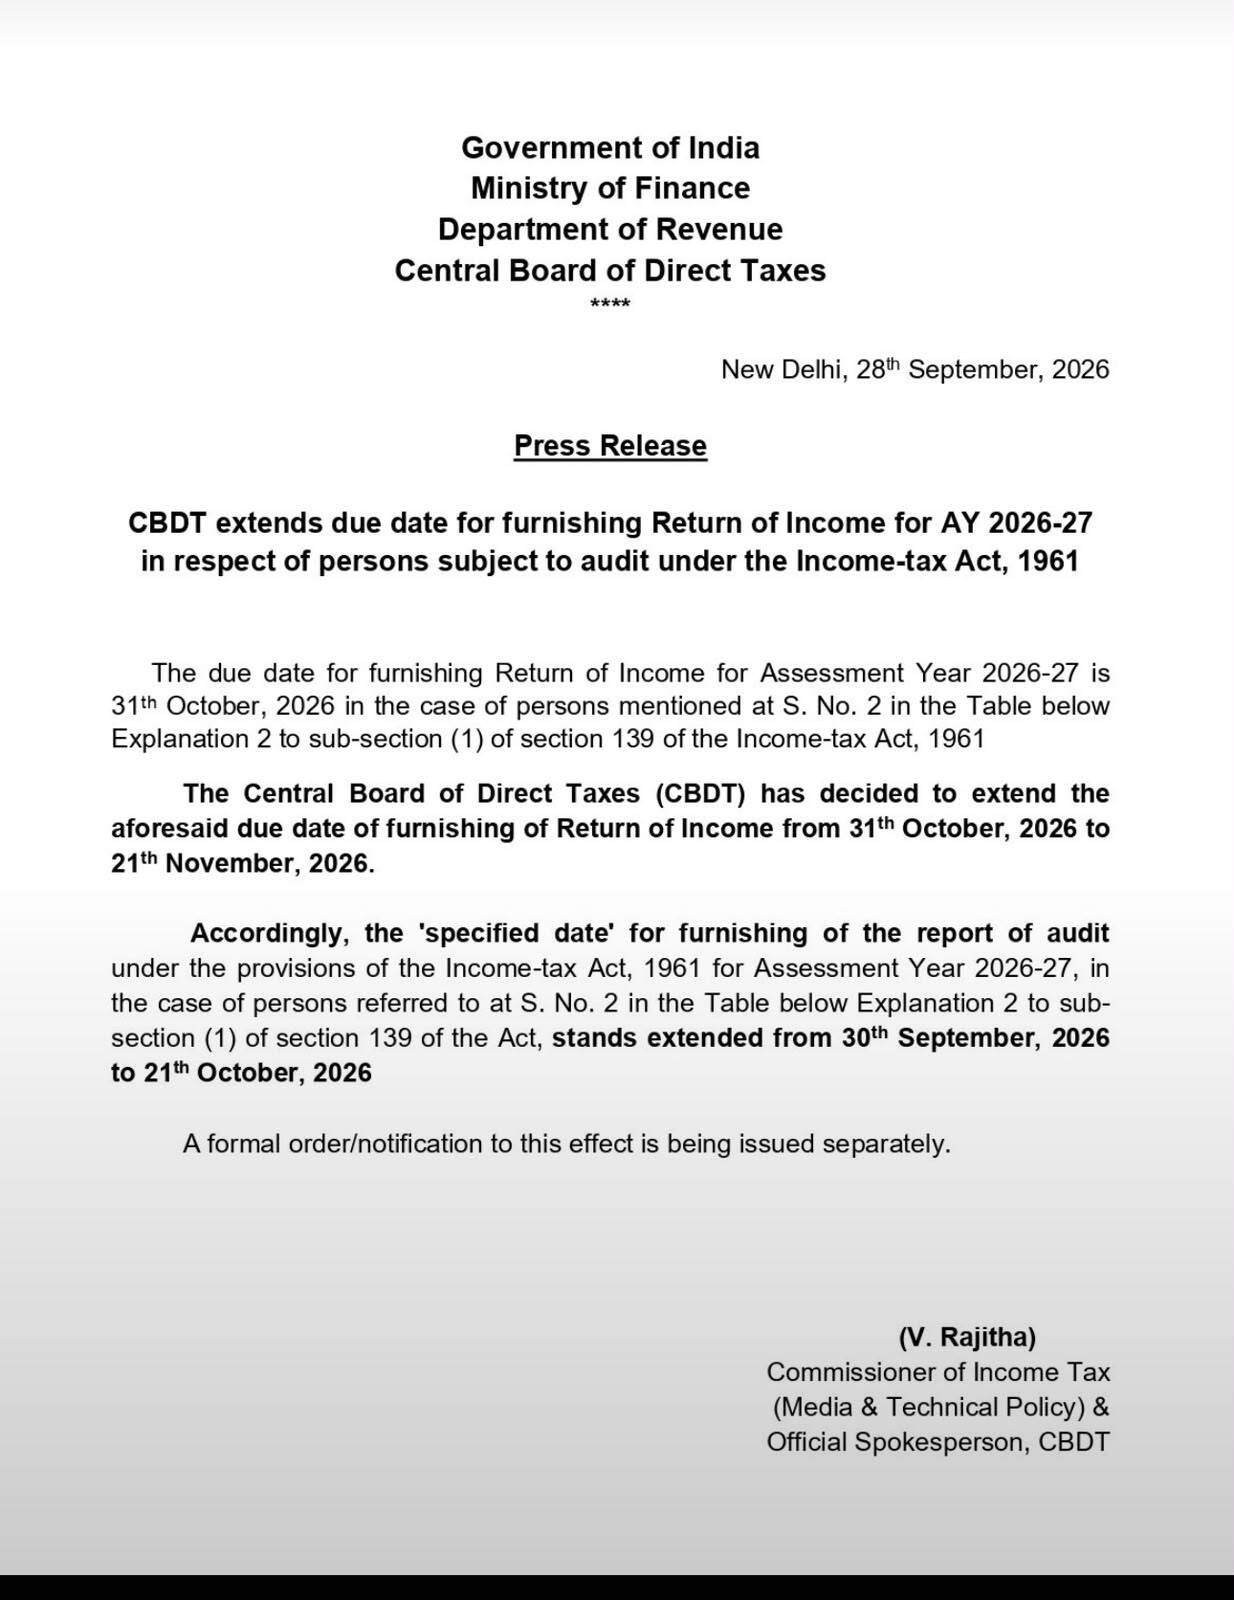
The deadline for tax audits has been moved up to 21 October 2026.
CBDT Circular was published on September 28, 2026.
Is chartered accountant’s be held responsible if the Tax Audit is not Completed on due date?
- It may be big questioned whether a tax auditor appointed as per section 44AB can be held accountable if the audit is not completed & Tax audit report is not submitted by the due-date. The facts & circumstances of such kind of case will decide answer to this question.
- Normally chartered accountant’s professional liability is to see that the audit he accepts is finished ahead of schedule. If a client complains and there is any arbitrary delay on his end,
- He is accountable to the ICAI Institute in case if a complaint is made by client. But The Tax Auditor as chartered Accountants cannot be held liable, In case Tax audit’s conclusion was delayed due to his client.
What are the Consequences of Penalty for Non submission of Tax Audit Report?
- As per Income tax provision Under Section 271B, if a person who must comply with section 44AB fails to have his accounts audited in respect of any year or years as required by section 44AB or to provide the report as required by section 44AB.
- The Assessing Officer may impose a fine/ penalty. The lower of the below amounts shall serve as the penalty:
- 5% of the total gross receipts or sales, turnover, as the case may be, in business, or of the gross receipts in the profession, in such year or years.
- INR 1,50,000/-
- But, According to Section 271B of Income tax act, states that no punishment shall be applied if a valid explanation for the failure is provided.
- For query or help, contact: singh@carajput.com or call at 9555-555-480
Popular Article :
How to file Revised Return of Income Tax E-Filing: Income Tax Department