CBDT Extends Tax Audit & ITR Due Dates for AY 2026-27
Page Contents
CBDT Extends Tax Audit & ITR Due Dates for AY 2026-27
Background: The Rajasthan High Court’s Intervention
The announcement came on the same day as a hearing before the Rajasthan High Court. The hearing was on a petition by the Rajasthan Tax Consultants Association (RTCA) seeking an extension. The Court asked the CBDT to clarify that day whether the tax audit due date would be extended. It said this uncertainty should not be allowed to continue until the last date. The Court also said that because tax audits are primarily conducted by Chartered Accountants, the ICAI should itself approach the Court when CAs face genuine difficulties. The CBDT then announced the extension later that day.
The wait is finally over.
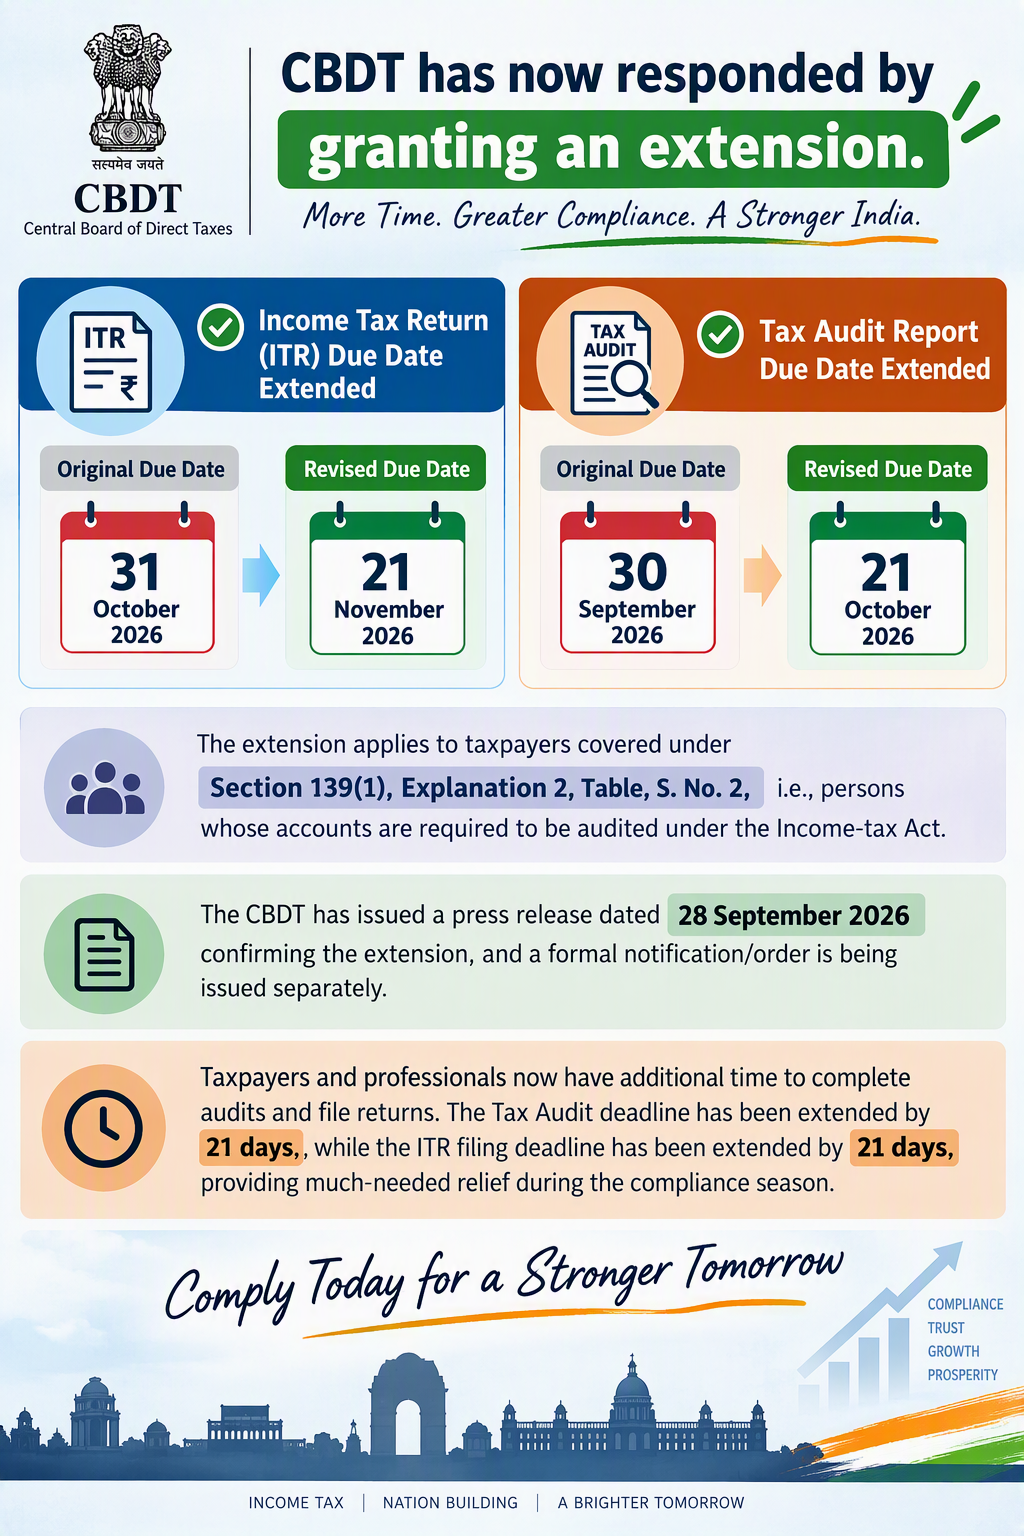
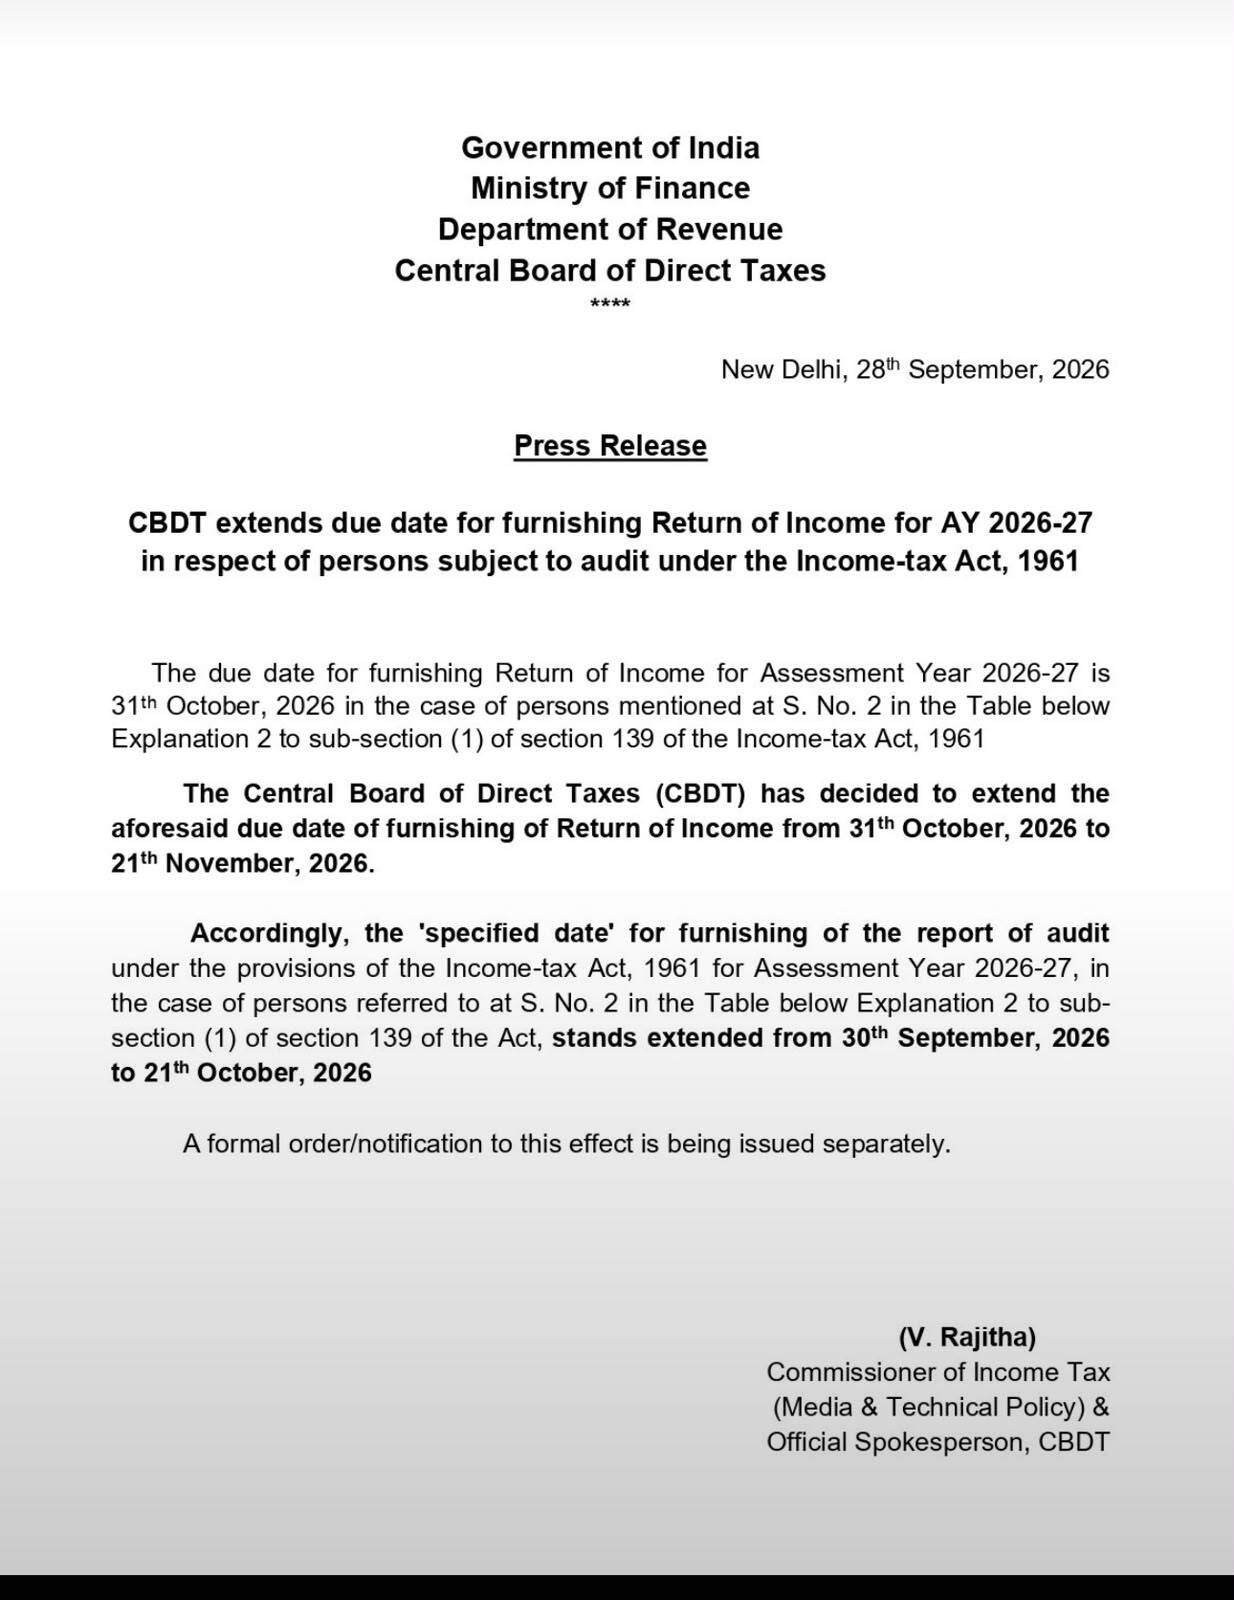
CBDT has now responded by granting an extension. – Revised Due Dates at a Glance
| Compliance | Original Due Date | Revised Due Date |
|---|---|---|
| Tax Audit Report (“specified date”) | 30 September 2026 | 21 October 2026 |
| Return of Income (audit cases) | 31 October 2026 | 21 November 2026 |
Both deadlines move by 21 days. A formal order or notification is being issued separately.
Who Is Covered?
The extension applies to persons at S. No. 2 in the Table below Explanation 2 to Section 139(1) of the Income-tax Act, 1961. Broadly, these are taxpayers whose accounts must be audited under the Act or any other law in force, such as:
- Companies
- Businesses and professionals whose accounts are audited under Section 44AB
- Working partners of firms whose accounts are required to be audited
Taxpayers with international or specified domestic transactions who must file a transfer pricing report in Form 3CEB fall under a separate entry. This press release does not change their dates.
Which Audit Reports Are Affected?
The CBDT press release extends the “specified date” for submission of audit reports under the Income-tax Act. Since the specified date is directly linked to the due date for filing the Income Tax Return, the extension covers the Tax Audit Report under Section 44AB, including Forms 3CA/3CB and Form 3CD.
The extension also applies to other audit reports that are required to be furnished by the same specified date, including audit reports of charitable trusts and institutions in Form 10B and Form 10BB, wherever applicable. Accordingly, taxpayers covered by the extension will receive additional time for filing these audit reports as well.
Note for AY 2026-27
The Income-tax Act, 2025 came into force from 1 April 2026. However, returns and audits for FY 2025-26 (AY 2026-27) are still governed by the Income-tax Act, 1961, which is why the press release refers to the 1961 Act.
Tax Audit Applicability under Section 44AB
Section 44AB(a) – Regular Business
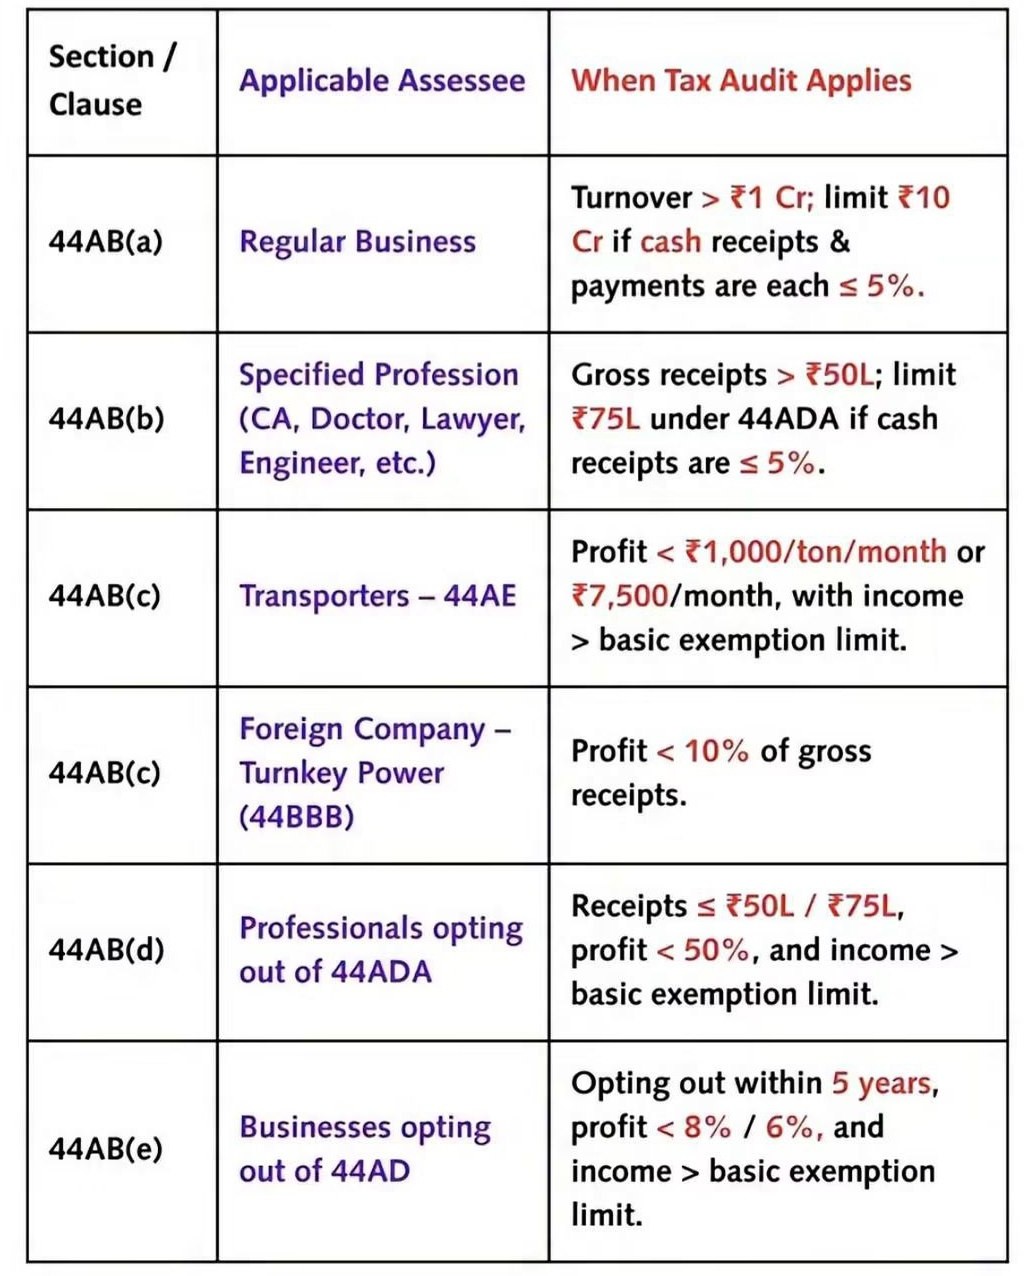
- Applicable Assessee: Regular Businesses . When Tax Audit Applies: Tax Audit is mandatory if total turnover or gross receipts exceed INR 1 Crore. The threshold is increased to INR 10 Crore if Cash receipts do not exceed 5% of total receipts; and Cash payments do not exceed 5% of total payments.
Section 44AB(b) – Specified Profession
- Applicable Assessee: Professionals such as Chartered Accountants, Doctors, Lawyers, Engineers, Architects, Technical Consultants, Interior Decorators and Other specified professionals
- When Tax Audit Applies Gross professional receipts exceed INR 50 Lakh. The limit increases to INR 75 Lakh under Section 44ADA where cash receipts do not exceed 5% of total receipts.
Section 44AB(c) – Transporters Covered under Section 44AE
Applicable Assessee: Persons engaged in the business of plying, hiring, or leasing goods carriages. When Tax Audit Applies: Income declared is lower than the presumptive income prescribed under Section 44AE: Less than INR 1,000 per ton per month for heavy goods vehicles; or Less than INR 7,500 per vehicle per month for other goods vehicles. Total income exceeds the basic exemption limit.
Section 44AB(c) – Foreign Company (Section 44BBB)
- Applicable Assessee: Foreign companies engaged in turnkey power projects approved by the Central Government. When Tax Audit Applies: Income declared is less than 10% of gross receipts, contrary to the presumptive income prescribed under Section 44BBB.
Section 44AB(d) – Professionals Opting Out of Section 44ADA
Applicable Assessee: Professionals eligible for presumptive taxation under Section 44ADA. When Tax Audit Applies:
-
- Gross receipts do not exceed INR 50 Lakh (or INR 75 Lakh where cash receipts are within 5% limit);
- Profit declared is less than 50% of gross receipts; and
- Total income exceeds the basic exemption limit.
Section 44AB(e) – Businesses Opting Out of Section 44AD
Applicable Assessee: Small businesses eligible for presumptive taxation under Section 44AD. When Tax Audit Applies: Profit declared is less than
- 8% of turnover (for cash receipts), or
6% of turnover (for digital receipts); - Total income exceeds the basic exemption limit; and The assessee opts out of the presumptive scheme within the prescribed five-year period.
Penalties for Missing the Revised Deadlines
- Section 271B: Failure to furnish the tax audit report by the due date can attract a penalty of 0.5% of turnover or gross receipts, subject to a maximum of ₹1.5 lakh.
- Under Section 234F: Late filing of the return attracts a late fee.
- Section 234A: Interest for delay in filing may apply. Check the formal CBDT order for any conditions on interest relief.
What Taxpayers Should Do Now
- Don’t wait for the last week. Portal congestion near deadlines is common. Finalise books and share data with your auditor now.
- Pay self-assessment tax early. This limits interest exposure, whatever the fine print of the formal order says.
- Reconcile with AIS/TIS and Form 26AS before finalising the audit report, so the return doesn’t draw mismatch notices.
- Verify the formal notification when it is issued, since that is the operative legal document.
Taxpayers and professionals now have additional time to complete audits and file returns. The Tax Audit deadline has been extended by 21 days, while the ITR filing deadline has been extended by 21 days, providing much-needed relief during the compliance season.
In summary
- 44AB(a) – Business turnover exceeds ₹1 Crore (₹10 Crore in specified low-cash cases)
- Section 44AB(b) – Professional receipts exceed ₹50 Lakh (₹75 Lakh in specified low-cash cases)
- 44AB(c) – Transporters declaring income below Section 44AE presumptive income
- Section 44AB(c) – Foreign power project companies declaring profit below 10% under Section 44BBB
- 44AB(d) – Professionals opting out of Section 44ADA and declaring profit below 50%
- Section 44AB(e) – Businesses opting out of Section 44AD and declaring profit below 6%/8%
- Tax Audit Due Date for AY 2026-27: 21 October 2026
- ITR Due Date (Audit Cases): 21 November 2026.
How Rajput Jain & Associates Can Help
+91-98-11-322-785 | info@carajput.com | www.carajput.com. Address P-6/90 (2F), Connaught Circus, Connaught Place, New Delhi – 110001
Disclaimer: This article is for general information only and is based on the CBDT press release dated 28 September 2026. Readers should refer to the formal notification/order and seek professional advice for their specific facts.