Depreciation Rate Chart (Income-tax Act, 1961)
Page Contents
Depreciation Rate Chart (Income-tax Act, 1961)
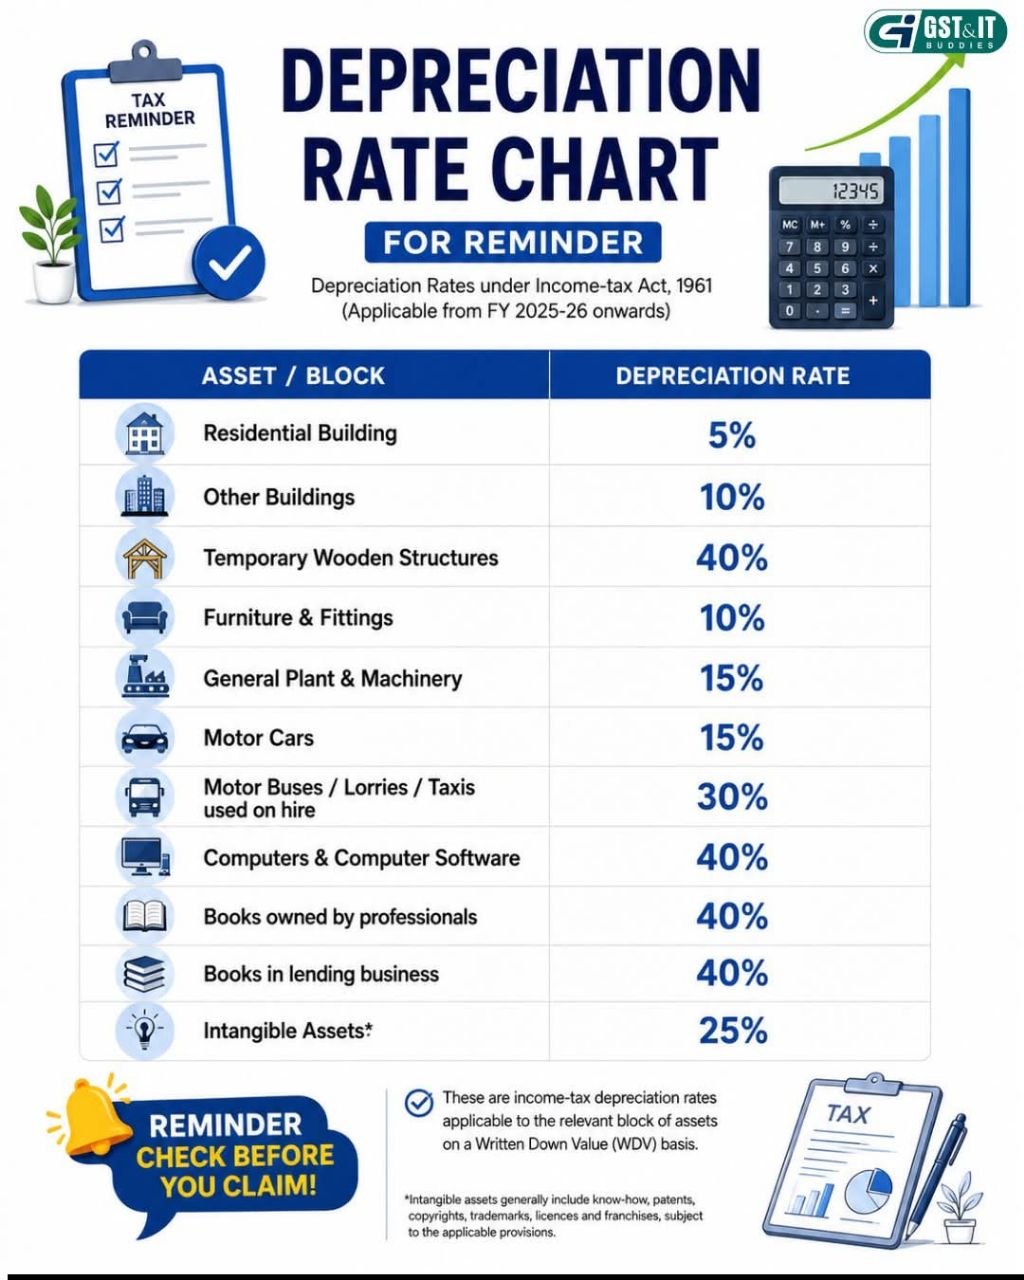
(As shown in the above applicable from FY 2025-26 onwards on WDV basis)
| Asset / Block | Depreciation Rate |
|---|---|
| Residential Building | 5% |
| Other Buildings | 10% |
| Temporary Wooden Structures | 40% |
| Furniture & Fittings | 10% |
| General Plant & Machinery | 15% |
| Motor Cars | 15% |
| Motor Buses, Lorries & Taxis Used on Hire | 30% |
| Computers & Computer Software | 40% |
| Books Owned by Professionals | 40% |
| Books Used in Lending Business | 40% |
| Intangible Assets* | 25% |
Notes : Depreciation is allowed on the Written Down Value (WDV) method under the Income-tax Act. Intangible Assets generally include Know-how, Patents, Copyrights, Trademarks, Licences and Franchises
Half-Year Rule
If an asset is put to use for less than 180 days during the financial year, only 50% of the applicable depreciation rate can be claimed in that year.
| Normal Rate | Rate if Used for Less than 180 Days |
|---|---|
| 5% | 2.5% |
| 10% | 5% |
| 15% | 7.5% |
| 25% | 12.5% |
| 30% | 15% |
| 40% | 20% |
Quick Examples
| Asset | Cost (INR ) | Rate | Full-Year Depreciation (₹) |
|---|---|---|---|
| Office Building | 10,00,000 | 10% | 1,00,000 |
| Furniture | 5,00,000 | 10% | 50,000 |
| Computer | 1,00,000 | 40% | 40,000 |
| Motor Car | 8,00,000 | 15% | 1,20,000 |
| Intangible Asset | 4,00,000 | 25% | 1,00,000 |
Important: Here we are a simplified reminder chart. For tax audit and return filing purposes, always refer to Appendix I of the Income-tax Rules and check for any special depreciation rates applicable to specific industries or assets. here under you can find the Complete Depreciation Rate Chart (Income-tax Act, 1961)