Page Contents
Rule 37BB of the IT Rules amended w.e.f.1st April 2016 to bring Major Changes in the Requirements of Form 15CA & 15CB and Foreign remittances covered under Sec 195: The Income Tax Depart amended the rules for the preparation and submission of Form 15CA & Form 15CB. The revised rules became effective as of 1.04.2016. The big changes are as follows
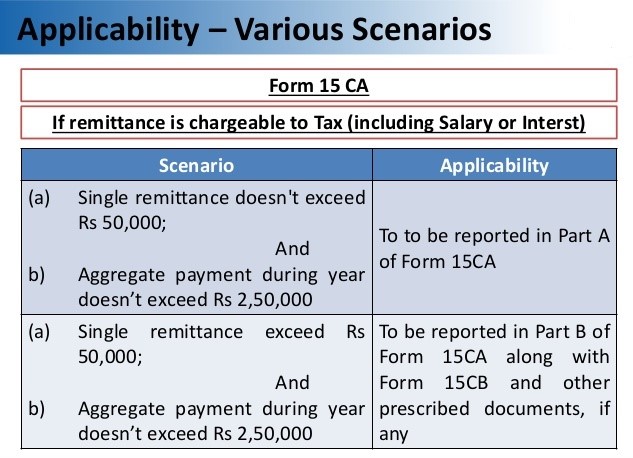
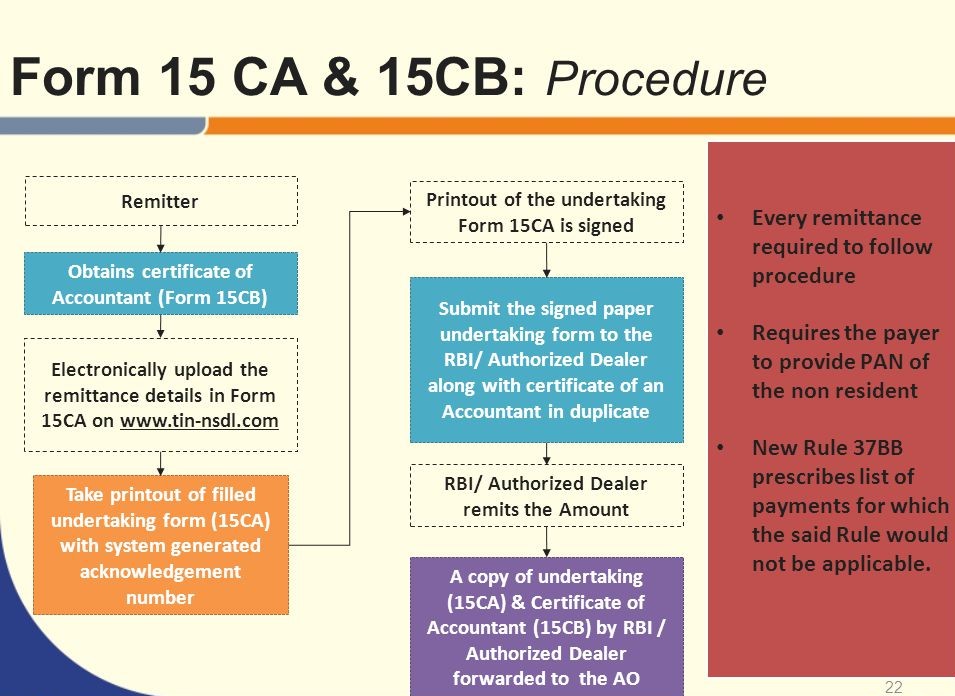
Certain payments made by a resident to a Non-resident must be made under the IT ACT 1961. The concept behind the deduction and subsequent reporting of taxes at the source is to make sure that taxes are collected on time. Form 15CA is a declaration made by the person remitting the money, stating that he has TDS from any payments to the non-resident. Details format of Form 15CA
Form 15CB, fortunately, is not a declaration, but a certificate issued by the Chartered Accountant to ensure that the provisions of the Double Taxation Avoidance Agreement and the Income Tax Act were complied with in respect of tax deductions while making payments. Contains the following details
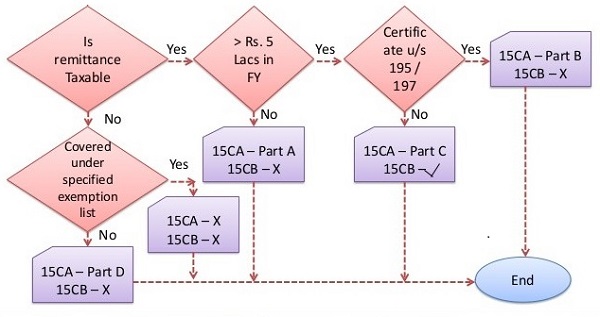
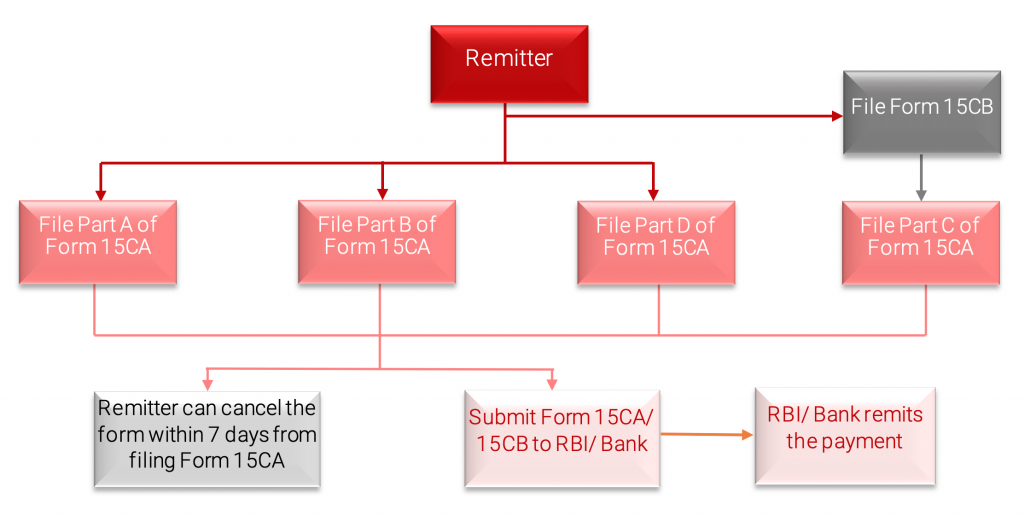
The form is divided into 4 parts to be filled out on the basis of a circumstance that is relevant at the time. There are 4 parts –
Part B of 15CA
Part C of 15CA
Part D of 15CA
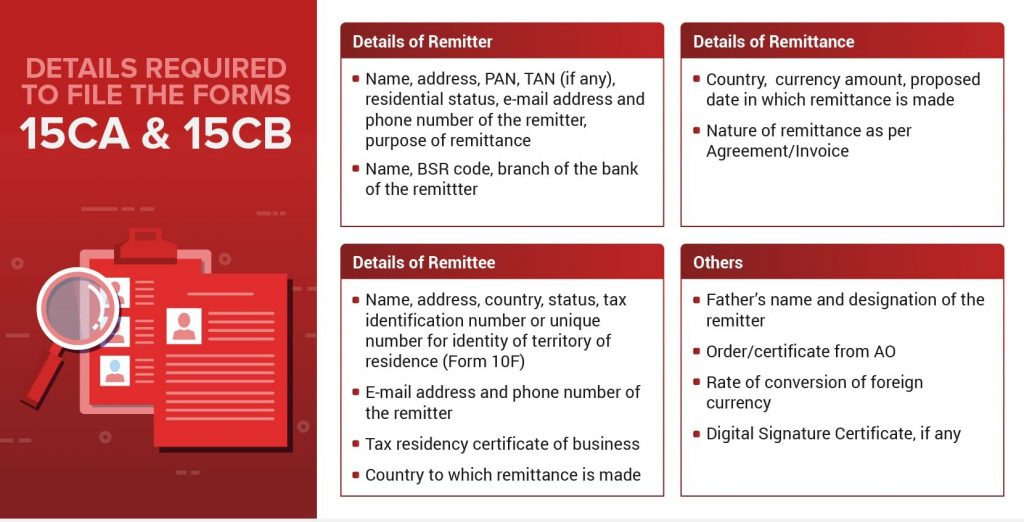
The person responsible for making the payment to a non-resident or a foreign company must provide the following details
www.carajput.com: Details-required-to-file-the-forms-15CA-15CB
As per Rule 37BB: The remittance shall be of the nature specified in the following list:
| Advance payment against imports | |
| Payment towards imports-settlement of invoice | |
| Imports by diplomatic missions | |
| Intermediary trade | |
| Imports below INR 5,00,000-(For use by ECD offices) | |
| Travel for pilgrimage | |
| Travel for medical treatment | |
| Freight insurance – relating to import and export of goods | |
| Payments for maintenance of offices abroad | |
| Maintenance of Indian embassies abroad | |
| Remittances by foreign embassies in India | |
| Remittance by non-residents towards family maintenance and savings | |
| Booking of passages abroad -Airlines companies | |
| Remittance towards business travel. | |
| Travel under basic travel quota (BTQ) | |
| Contributions or donations by the Government to international institutions | |
| Indian investment abroad -in subsidiaries and associates | |
| Indian investment abroad -in real estate | |
| Loans extended to Non-Residents | |
| Operating expenses of Indian Airlines companies operating abroad | |
| Remittance towards donations to religious and charitable institutions abroad | |
| Remittance towards grants and donations to other Governments and charitable institutions established by the Governments. | |
| Payment- for operating expenses of Indian shipping companies operating abroad. | |
| Remittance towards personal gifts and donations | |
| Remittance towards payment or refund of taxes. | |
| Refunds or rebates or reduction in invoice value on account of exports | |
| Payments by residents for international bidding. | |
| Travel for education (including fees, hostel expenses etc.) | |
| Indian investment abroad-in branches and WOS (Wholly owned subsidiaries) | |
| Construction of projects abroad by Indian companies including import of goods at project site | |
| Indian investment abroad -in equity capital (shares) | |
| Indian investment abroad -in debt securities | |
| Postal Services |
If the Assessor who is supposed to file Form 15CA 15CB fails to provide the same information prior to the transfer to a non-resident, the Assessor shall be liable for penalties regulations in accordance with Section 271I of the I T Act 1961.
Such an unlawful provision shall be attracted even if the person has provided incorrect information. The amount of penalty that the Assessing Officer may ask the Assessor to pay for non-compliance is Rs.1lakhs.
Yes, Form 15CA may be withdrawn within 7 days from the date of submitting. The respective link to withdraw the file form will be available on the Income-tax portal of the Assessee relevant concerned.
For query or help, contact: singh@carajput.com or call at 9555555480
Popular blog:-
TDS on Purchase of Property from an NRI: PAN-Based Compliance Replaces TAN from 1 October 2026 The Government has significantly… Read More
RBI Relaxes FEMA Export-Import Reporting for Service Exporters and Importers Reserve Bank of India (RBI) has simplified FEMA compliance requirements… Read More
Complete Guide to Limited Liability Partnership A Limited Liability Partnership is a hybrid business structure that combines the operational flexibility… Read More
ROC Provisions Relating to Directors under the Companies Act, 2013 The provisions relating to directors under the Companies Act, 2013… Read More
New GST Registration Guidelines from 1 November 2026 As per New GST Registration Guidelines from 1st Nov 2026 - As per Circular-No-257-03-2026… Read More
CSR Policy: Activities under Schedule VII and CSR Implementation through Eligible Agencies The framework of Corporate Social Responsibility (CSR) under… Read More