Page Contents
| BASIS | SECTION 194Q | SECTION 206C(1H) |
| OBLIGATION | BUYER | SELLER |
| TURNOVER LIMIT TO DETERMINE APPLICABILITY | PREVIOUS YEAR TURNOVER/ GROSS RECEIPTS OF BUYER EXCEEDS 1 0CR | PREVIOUS YEAR TURNOVER/ GROSS RECEIPTS OF SELLER EXCEEDS 10CR |
| EFFECTIVE DATE | 1ST JULY, 2021 | 1ST OCTOBER 2020 |
| THRESHOLD LIMIT | PURCHASE IN EXCESS OF 50 LACS FROM EACH SELLER DURING THE YEAR | SALE IN EXCESS OF 50 LACS TO EACH BUYER DURING THE YEAR |
| TIME OF DEDUCTION/ COLLECTION | BILL OR PAYMENT WHICHEVER IS EARLIER | AT THE TIME OF RECEIPT |
| PRESCRIBED RATE | 0.10% | 0.10% |
| HIGHER RATE WHERE PAN IS NOT AVAILABLE | 5% | 5% |
| RETURN FORM | 26Q | 27EQ |
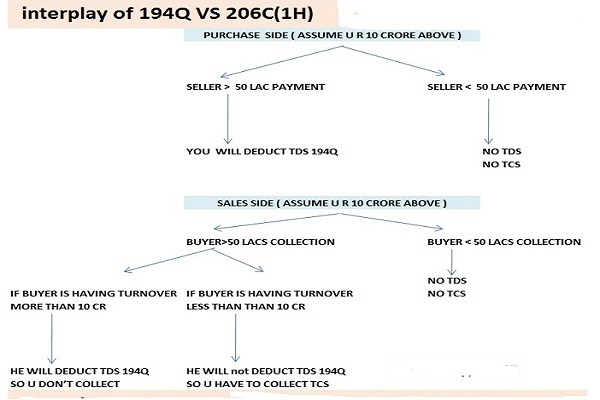
In case, a transaction falls within the ambit of both the sections- 194Q and 206C(1H), the following treatment be done –
| SITUATION | TDS/ TCS APPLICABLE PROVISION |
| TURNOVER IN PRECEDING FY BUYER >10 CR, SELLER<10CR | 194Q: BUYER TO DEDUCT TDS |
| TURNOVER IN PRECEDING FY BUYER <10 CR, SELLER>10CR | 206C(1H): SELLER TO COLLECT TCS |
| TURNOVER IN PRECEDING FY BUYER >10 CR, SELLER>10CR | 194Q: BUYER TO DEDUCT TDS |
| TURNOVER IN PRECEDING FY BUYER <10 CR, SELLER<10CR | NOTHING APPLICABLE |
| ADVANCE PAID BY BUYER ON OR AFTER 1ST JULY 2021 | 194Q WILL BE APPLICABLE AS TRIGGER POINT FOR 1 94Q IS EARLIER OF PAYMENT OR CREDIT OF SUCH SUM TO THE SELLER |
| ADVANCE PAID BY BUYER ON OR BEFORE 30TH JUNE 2021 | SELLER WILL COLLECT TCS ON SUCH TRANSACTION U/S 206C(1H), SINC THE TRIGGER POINT FOR DEDUCTION OF TDS IS PAYMENT OR CREDIT WHICHEVER IS EARLIER. THUS, TDS DEDUCTED U/S 194Q SHALL NOT BE APPLICABLE WHERE PAYMENTS ARE MADE BEFORE 30TH JUNE 2021. |
Before the introduction of sections 194Q and 206C(1H), sales and purchases of products were out of the purview of TDS/ TCS. However, now Form 26 AS is further audit evidence to verify/ confirm the numerous revenues and buy of products transactions.
Under clause 34a of the shape 3CD, where auditor is required to investigate overall TDS/ TCS compliances by the assessee, detailed reconciliation may need to run for these newly added sections.
In case of non-compliances with the provisions of these sections, disallowances, interest and penalty will be welcomes by the taxpayer.
Auditors are required to diligently consider the identical for creation of provision for taxes within the books of account and also for the calculation of income tax liability and its consequent impacts in deferred taxes.
Reservation in CA, CS & CMA: A Detailed Debate Perspective The discussion around introducing reservation in professional courses such as… Read More
DCF Is Out: Rule 57 Prescribes Only NAV for Valuation of Unquoted Equity Shares The introduction of the Income-tax Rules,… Read More
Advertisement Enabled Era of CA Practice: ICAI Relaxes Publicity Norms Effective 1 April 2026, the revised ICAI Code of Ethics,… Read More
Aadhaar Authentication for Good Governance : Dept of Development-IT The Department of Development-IT, Government of India, has issued a public… Read More
TDS on Purchase of Property from an NRI: PAN-Based Compliance Replaces TAN from 1 October 2026 The Government has significantly… Read More
RBI Relaxes FEMA Export-Import Reporting for Service Exporters and Importers Reserve Bank of India (RBI) has simplified FEMA compliance requirements… Read More