Page Contents
micro small and medium enterprises
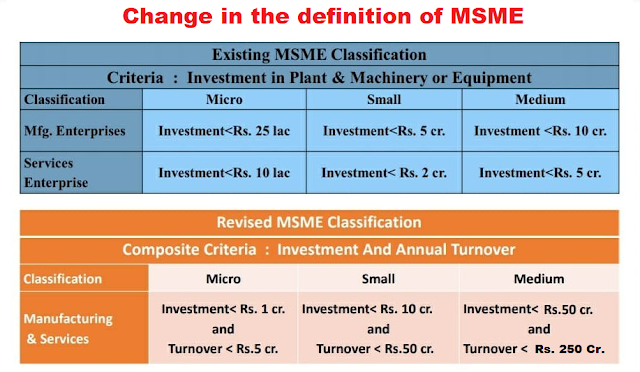
The Micro Small & Medium Enterprises (MSMEs) are defined in India in the MSME Act 2006 according to the capital investment made in plant and machinery, excluding investments in land and building.
For multiple kind of industries which come under classification criteria, an MSME license is preferred since it has the below incentives scheme & benefits:
Below types of business entities covered under the MSME are:
According to the rules, every specified companys are required to file MSME Form I with Roc in the situation mentioned below:
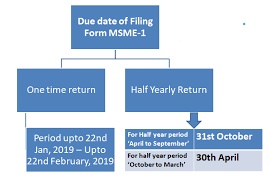
Every specified company shall file in MSME Form I details of all outstanding dues to Micro or small enterprises suppliers existing on the date of notification of this order within thirty days from the date of publication of this notification which is 22nd January.
All the specified MSME Company shall file a return as per MSME Form I annexed to this Order, by 31st October for the period from April to September and by 30th April for the period from October to March.
Specified Company means Every Company “Public or Private” who Received Goods or Services ‘from’ Micro or Small Enterprises ‘of which’ Payment Due or Not Paid till 45 days.
For more reading: MSME CONSULTANCY & REGISTRATION SERVICE
The Ministry of Corporate Affairs has updated the definition of a small company, effective from 01.12.2025. The new criteria are as follows:
Every Company within 30 days from the date of the notification i.e. 22nd February 2019 (22nd January 2019 + 30 days) is required to file this form as Initial Return.
All MSME Company within 30 days from the last day of half-year shall file the regular half-yearly return.
INITIAL RETURN:
Total outstanding amount, Details of suppliers, and payments due (PAN of Suppliers)
REGULAR HALF YEARLY RETURN
Total outstanding due for the period and particulars of suppliers therein for the period, Reasons for delay in payment.
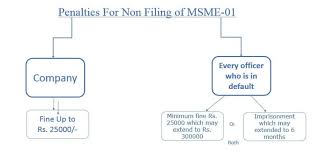
Penalty Provision as per Section 405 (4) of the Companies Act, 2013, if the said details are not submitted to MCA on or before 20/02/2019 or the information submitted is incorrect or incomplete.
Fine
NOTE: Non-compliance with such provisions will lead to punishment and penalty under the provision of the Act
https://youtu.be/PG48SK_4YQ8.
Popular Articles :
New TDS Framework for Purchase of Property from NRIs Effective 1 October 2026 Income Tax Notification: The CBDT has notified… Read More
Statutory Tax Compliance Calendar – October 2026 October 2026 is one of the busiest compliance months of the year. Businesses… Read More
Unpaid Audit Fees and Auditor Independence: What the ICAI Code of Ethics Really Says No, an auditor is not barred… Read More
Moving to the UAE: What Actually Decides Your Indian Tax Residence Documents show where you live, not your tax status… Read More
Depreciation Rate Chart (Income-tax Act, 1961) (As shown in the above applicable from FY 2025-26 onwards on WDV basis) Asset… Read More
Summary of August 2026 GST Revenue Review The AUG 2026 gst revenue report final for publishing monthly shows a strong… Read More