Page Contents
Moreover, in the Budget Exemptions to rule due to the amendments made in the Income-tax Act, 1961, which stipulates the below person will not be exempted from the penalty
Submit the ITR dues also ensure that interest payable on the income tax refund is calculated from April 1 of the relevant AY. In the case of belated filings, the individual loses out on some amount of interest.
“In view of the continued challenges faced by taxpayers in meeting statutory compliances due to outbreak of COVID-19, the government further extends the dates for various compliances,” said the CBDT in a statement.
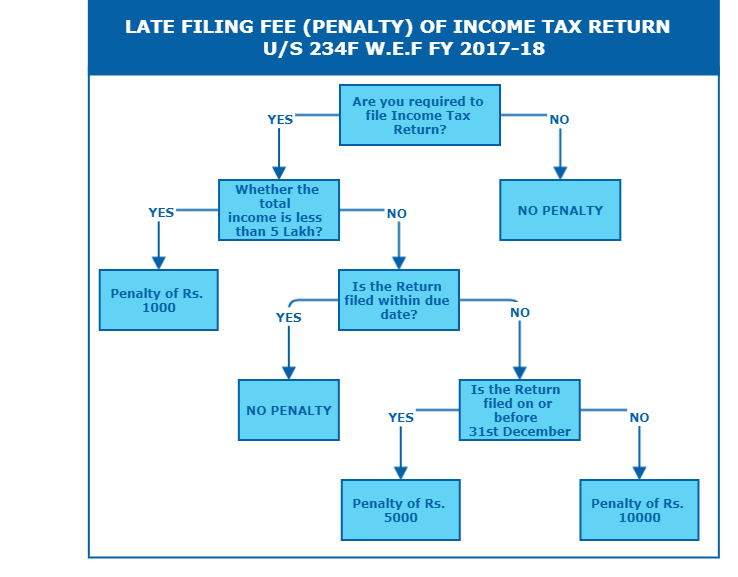
| Applicable Late Filing Fee Details as per section 234F | ||
| E- Income tac Filing Date | Total income Below INR 5 lakhs | Total income Above INR 5 lakhs |
| Up to 31st August 2020 | Rs 0 | Rs 0 |
| Between 1st September 2020 to 31st December 20 | Rs 1,000 | Rs 5,000 |
| Between 1st January 21 to 31st March 21 | Rs 1,000 | Rs 10,000 |
| ITR 1 (SAHAJ) | Individuals with Salary & interest Income only |
| ITR 2 | Individuals and HUF not having income from business/profession |
| ITR 3 | Individuals/ Hindu Undivided Families being partners in firms & not carrying out business or profession under any proprietorship |
| ITR 4 | Individuals & Hindu Undivided Families having a proprietary business or profession income |
| ITR 4S (SUGAM) | Individuals or Hindu Undivided Families having presumptive business Income |
| ITR-5 | In order for AOP & BOI, LLP, & Partnership firms to report their income and tax computation. |
| ITR-6 | Co that are registered in India use this form. |
| ITR-7 | In case entities are claiming an exemption as colleges, scientific research institutions, political parties or universities, and religious or charitable trusts, this form must be used. |
| Installments | Rate of Advance Tax | Total Liability/due under advance Tax |
|---|---|---|
| First Installments | 15 % | 4,80,000*15%= 72,000 |
| Second Installments | 45% | 4,80,000*45%= 2,16,000 |
| Third Installments | 75% | 4,80,000*75%= 3,60,000 |
| Fourth Installments | 100% | 4,80,000*100%= 4,80,000 |
three kinds of Interest payable u/s 234 as below mention hereunder :
Tax returns for AY2023-24 (The FY 2022-23 ) were original to be filed by July 31.
Please Note – All taxpayers opting for old tax regime in AY 2024-25 need to file Form 10IEA before due date of ITR Filing
CSR Policy: Activities under Schedule VII and CSR Implementation through Eligible Agencies The framework of Corporate Social Responsibility (CSR) under… Read More
CSR through Zero Coupon Zero Principal (ZCZP) Instruments: Detailed Analysis of Rule 4A The Ministry of Corporate Affairs (MCA) introduced… Read More
CSR Compliance for Insurance Companies: Detailed Analysis of IRDAI Guidelines The Insurance Regulatory and Development Authority of India (IRDAI) has… Read More
Social Stock Exchange (SSE) & Not-for-Profit Organizations (NPOs): Detailed Explanation The Social Stock Exchange (SSE) is a dedicated platform created… Read More
Social Stock Exchange (SSE): Eligibility, Registration, Fund Raising & Compliance Requirements The Social Stock Exchange (SSE) framework introduced by SEBI… Read More
Key Managerial Personnel (KMP) Under the Companies Act, 2013: Roles, Appointment, Compliance and Remuneration Effective corporate governance begins with strong… Read More